StarHub Limited – Wait for the saviour
- Results were below expectations. 1H26 revenue/EBITDA were 41%/43%, respectively, of our FY26e forecast. The weakness was partly due to the absence of Ensign, which is now an associate. Excluding Ensign, EBITDA dropped 24% YoY to S$158mn. Underlying PATMI collapsed by at least 74% YoY to S$12.4mn in 1H26 (excluding Ensign). StarHub did not provide PATMI excluding Ensign in 1H25.
- Revenue continues to deteriorate, not only in mobile but across all divisions. Mobile service revenue declined 10.5% YoY to S$245mn and a further 2% QoQ in 2Q26. Broadband and entertainment fell 8.5% YoY to S$208mn. Securing EPL rights did not lead to any premier performance.
- We lower FY26e EBITDA by 10% to S$325mn and removed cybersecurity revenue from our forecast. Ensign is currently a 38.92% associate. Our target price is raised to S$1.07 (prev. S$0.95) as we incorporate Ensign’s book value at a 50% discount. Our NEUTRAL recommendation is maintained. We expect StarHub to dispose of the remaining stake in Ensign back to its parent, potentially in FY26. We believe the proceeds can then be used to fund acquisitions and refuel the mobile operations.
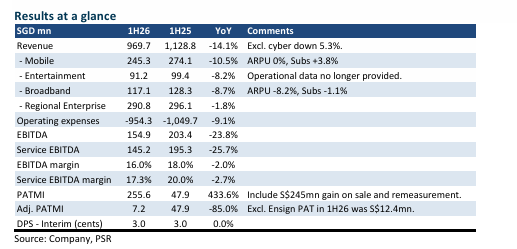
The Positive
+ 5G plus supposed traction. The company mentioned mobile was enjoying improved metrics due
to 5G+ unlimited plans. Moving customers to these plans also leads to higher customer
satisfaction and fewer service issues. We have not seen the benefits. ARPU has declined 5% QoQ
to S$20/month.
The Negative
- Not just mobile suffering. All four segments are experiencing declining revenue, led by mobile,
which fell 10.5% YoY to S$245mn. On a QoQ basis, there was a 9% improvement in regional
enterprise, which is affected by lumpy projects. Mobile competition is pressuring roaming, IDD,
voice and data subscriptions, and VAS revenues.
StarHub Limited – Pursuing all pain, no gain strategy
- Results were below expectations. 1Q26 revenue/EBITDA were 22% and 20%, respectively, of our FY26e forecast. PATMI plunged 81% YoY to S$5.9mn in 1Q26. Weakness spread across all consumer segments, mobile, broadband and entertainment.
- StarHub's pursuit to be the clear number two (by revenue) in the mobile market comes at a high cost. There is limited price elasticity and only market-share rotation, with all the value accruing to consumers. Mobile revenue fell 11% YoY (and 4% QoQ) in 1Q26 to S$124mn. Revenue weakness is also intensifying in other sectors, namely broadband and entertainment, amid widening price competition.
- We lower FY26e EBITDA forecast by 4% to S$363.1mn. Our target price is lowered to S$0.95 (prev. S$1.01) and NEUTRAL recommendation is maintained. StarHub will look to further pare down its remaining 38.9% stake in Ensign, worth S$322mn, to its parent. The parent support can be used to strengthen the balance sheet and rearm StarHub for its quest to be the number two leader in mobile market share. With limited ability to optimise costs, the next expedition is to build services and differentiate the brand.

The Positive
+ Jump in enterprise order book. The order book for regional enterprise jumped more than 50%
YoY. Limited details on the size or value of the projects, except that they involve managed services
and critical infrastructure with cybersecurity needs.
The Negative
- All segments are contracting faster. The pace of revenue decline in consumer is the worst since
the pandemic. Mobile revenue continues to deteriorate due to the 6.6% drop in subscribers.
Broadband is facing more intense price pressure with ARPU dropping 8% YoY.
StarHub Limited – Parents hong bao helps DARE++ déjà vu
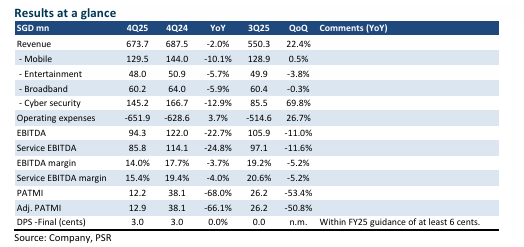
- Results were within expectations. FY25 revenue and EBITDA were 102% and 97%, respectively, of our forecast. Adjusted PATMI declined 29% YoY to S$100.5mn in FY25. StarHub is guiding a 15-20% YoY decline in FY26 EBITDA. Despite weaker earnings, the company is maintaining at least 6 cents dividend for FY26 (>100% payout).
- Mobile revenue declined 10% YoY in 4Q25 to S$129mn. The negative operating leverage will pressure margins in FY26. Despite sluggish revenue, there is a lack of cost control, and CAPEX-to-sales is expected to at least double in FY26. Dare+ (or maybe minus) transformation started in 2022 to rein in costs and improve technology. The utopia of $280mn cumulative cost savings was not apparent. Fixed costs are higher since 2022. The company is now positioning a new Dare++ with S$70mn identified cost savings and higher CAPEX.
- We lower FY26e EBITDA forecast by 8% to S$377mn. There is a downside to our forecast as mobile competition remains intense. We expected the share price to be supported by StarHub’s use of its balance sheet to maintain dividends. Our NEUTRAL recommendation is maintained with a lower target price of $1.01 (prev. S$1.05). A potential special dividend or deleveraging event is expected from disposing of ~17% of Ensign's assigned rights under a put/call option with its parent. After seven years, Ensign's core operating profit is est.S$800k.
The Positive
+ Maintained dividend. FY25 dividends met expectations of at least 6 cents. To maintain
dividends, the balance sheet was leveraged up for a 103% payout ratio. Free cash flow excluding
S$188mn spectrum (and S$29mn leases) was S$134mn.
The Negative
- Mobile revenue contracting. Mobile revenue continues to weaken with a 10% YoY drop to
S$129.5mn.The pace of decline has slowed on a QoQ basis, with ARPU remaining stable at S$22.
Aggressive offers by competitors in the value segment appear to be stabilising, with plans priced
at $ 10–$12 per month, but free-month offers remain.
StarHub Limited – Still munching popcorn
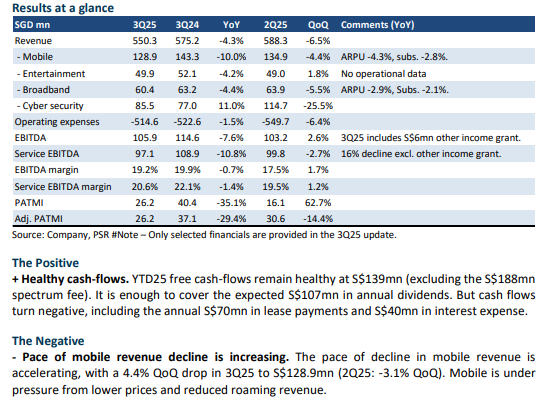
- Results were below expectations. 9M25 revenue and EBITDA were 72% and 71%, respectively, of our FY25e forecast. Earnings were propped up by S$6mn other income grant. 3Q25 PATMI was down 30% YoY to S$26.2mn following the 9% fall in EBITDA and higher depreciation.
- Mobile competition remains intense, especially at the low-end price plans and increased bundling of roaming packages. We think competition has intensified as unlimited mobile data and voice plans have been launched, targeting the premium user. Competition is also spreading to broadband, with 3Q25 revenue declining 4% YoY.
- We lower FY25e EBITDA forecast by 4% to S$418mn. Our NEUTRAL recommendation is maintained with a lower target price of $1.05 (prev. S$1.08). We assume mobile price competition in Singapore will not abate until the end of 2026. We believe StarHub will attempt to narrow its revenue market share with Simba Telecom as it turns 2nd largest operator and focused on integrating networks and synergies. A potential special dividend opportunity for StarHub will be a 20% (currently 56%) sale of Ensign under a call option.
StarHub Limited – Munch popcorn, just watch the fight
- Results were within expectations. 1H25 revenue and EBITDA were 48% and 46%, respectively, of our FY25e forecast. Headline PATMI was down 63% YoY to S$16.1mn in 2Q25, due to a S$14.1mn spectrum right forfeiture fee. Excluding the fee, PATMI decline would be 29% YoY.
- Mobile revenue and ARPU continue to weaken, falling 7% and 13% YoY, respectively. Competition in the mobile market is intensifying, with mobile plans now bundling significantly more local and roaming data. Price aggression is also appearing from the market leader.
- We maintain our FY25e forecast and NEUTRAL recommendation. Our target price of $1.08 is unchanged. StarHub will ramp up its aggressive pricing despite the planned acquisition of M1 by Simba. It is unclear what Simba’s pricing strategy is post-acquisition. StarHub has revised its FY25e EBITDA guidance downward from stable to a 12% to 16% decline (PSR: -5%).
StarHub Limited – Still in hyper-competition mode
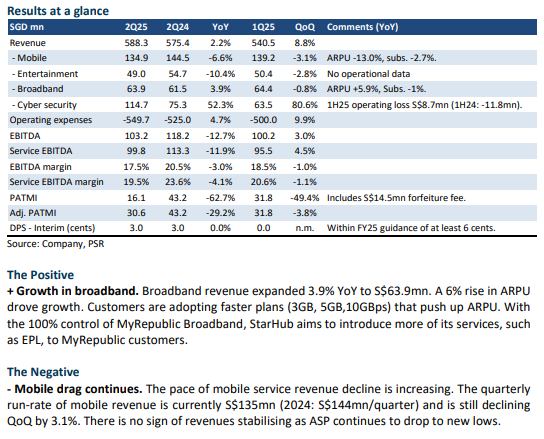
- Results were below expectations. 1Q25 revenue and EBITDA were 23% and 22%, respectively, of our FY25e forecast. Mobile ARPU continues to suffer from intense competition. On a QoQ basis, ARPU slipped 4.5%.
- Mobile price competition is across categories, including roaming and MVNO. The economics of the business will only worsen with the additional capacity and S$282mn payment for the 700MHz spectrum due 1 July.
- Our FY25e EBITDA is lowered by 5% to S$438mn as we reduce our mobile ARPU assumptions. We lowered our recommendation to NEUTRAL from ACCUMULATE. The target price is cut to S$1.08 (prev. S$1.29), from lower earnings and valuations (6.5x to 6.0 EV/EBITDA). There has been no let-up in the competitive pressure. The intense price competition and bulking up are driving the sector into consolidation and forcing incumbents to realign their cost structure.
StarHub Limited Mobile competition clouds outlook
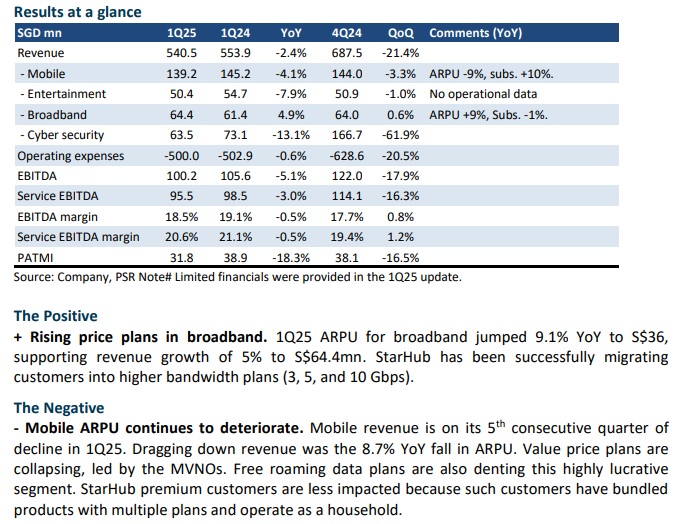
- Revenue was within expectations at 102% of our FY24 forecast. But EBITDA was below at 96%. Mobile continues to face intense competition, with 4Q24 ARPU declining 12.1% YoY. The final dividend per share was down 24% YoY to 3.2 cents.
- Mobile postpaid subscribers are still ramping up by 94k in 4Q24 (4Q23 -5k). However, it is at the expense of revenue declining 6% YoY to S$144mn in 4Q24. Market share has crept up 1.4% points YoY to 23.9% in FY24. StarHub is guiding stable EBITDA for FY25.
- We lower our FY25e EBITDA by 13% to S$461mn due to the intense competition in mobile. Our target price of S$1.29 (6.5x FY25e EV/EBITDA) and ACCUMULATE recommendation are unchanged. Earnings recovery is expected in FY26e as DARE+ cost savings materialise. Intense mobile price competition has no winners in the industry except for quickening the urgency for consolidation. We believe the consolidator will face the distraction and cost of an acquisition. StarHub has the financial capacity to consolidate but is not the only aspirant.


StarHub Limited – Spike in mobile subscribers
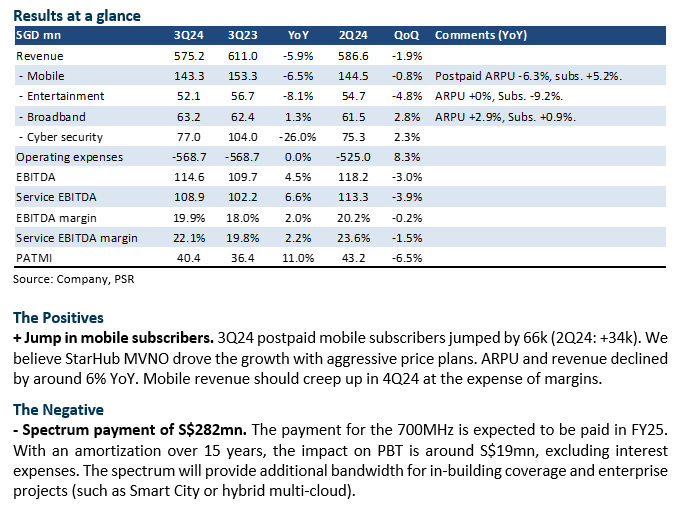
- 3Q24 results were marginally below expectations due to project timing in the enterprise business. 9M24 revenue and EBITDA were 72%/71% of our FY24 estimates. StarHub has not changed FY24e guidance in revenue and EBITDA.
- Mobile postpaid subscribers spiked by 66k in 3Q24 to 1.66mn. This is more than a decade high in quarterly subscriptions and taking market share from peers (Singtel’s -16k, M1 -23k). The 700MHz spectrum payment of S$282mn is payable in FY25. We find minimal value creation opportunities from this additional bandwidth to justify the price tag. It is a S$19mn p.a. amortisation or 10% drag on earnings, wiping most Dare+ benefits.
- The mobile operating environment remains intense. Most of the mobile subscriber gains were from Mobile Virtual Network Operators (MVNOs) on the StarHub network (i.e. wholesale pricing). We believe margins will be impacted. We maintain our FY24e forecast and target price of S$1.29 (6.5x FY24e EV/EBITDA). We upgrade our recommendation from NEUTRAL to ACCUMULATE due to the recent weakness in share price. Consolidation in the mobile industry is rational, as the current competitive intensity and upcoming spectrum payments only depress the return profile of the entire industry. However, any price repair from consolidation still depends on the behaviour of competitors.
StarHub Limited – Service revenue stalling
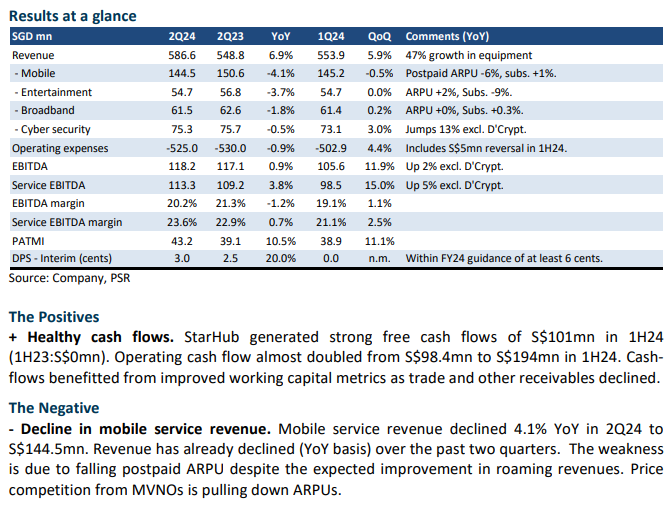
- 2Q24 results were within expectations and management full-year guidance. 1H24 revenue and EBITDA were 47%/46% of our FY24 estimates, excluding D’Crypt (disposed in Feb24). Interim dividend rose 20% to 3 cents and within guidance of at least 6 cents full year.
- 2Q24 service EBITDA expanded 5% YoY to S$113mn excluding D’Crypt. Margins benefited from a S$5mn reversal of overseas lease circuits. Excluding this reversal, 2Q24 service EBITDA will be flat or up 0.4% YoY.
- Competition from lower priced mobile MVNOs price plans is dragging down ARPU. Broadband is faced with new competition from SIMBA. Our forecasts are largely unchanged. The target price of S$1.29 is maintained (6.5x FY24e EV/EBITDA) in line with other mobile peers. We downgrade from ACCUMULATE to NEUTRAL due to the share price performance. We believe the competitive environment in mobile and broadband will place pressure on revenue in the near term. With DARE+ investments, cost savings will be more evident in FY25.
StarHub Limited – Mobile competition intensifying
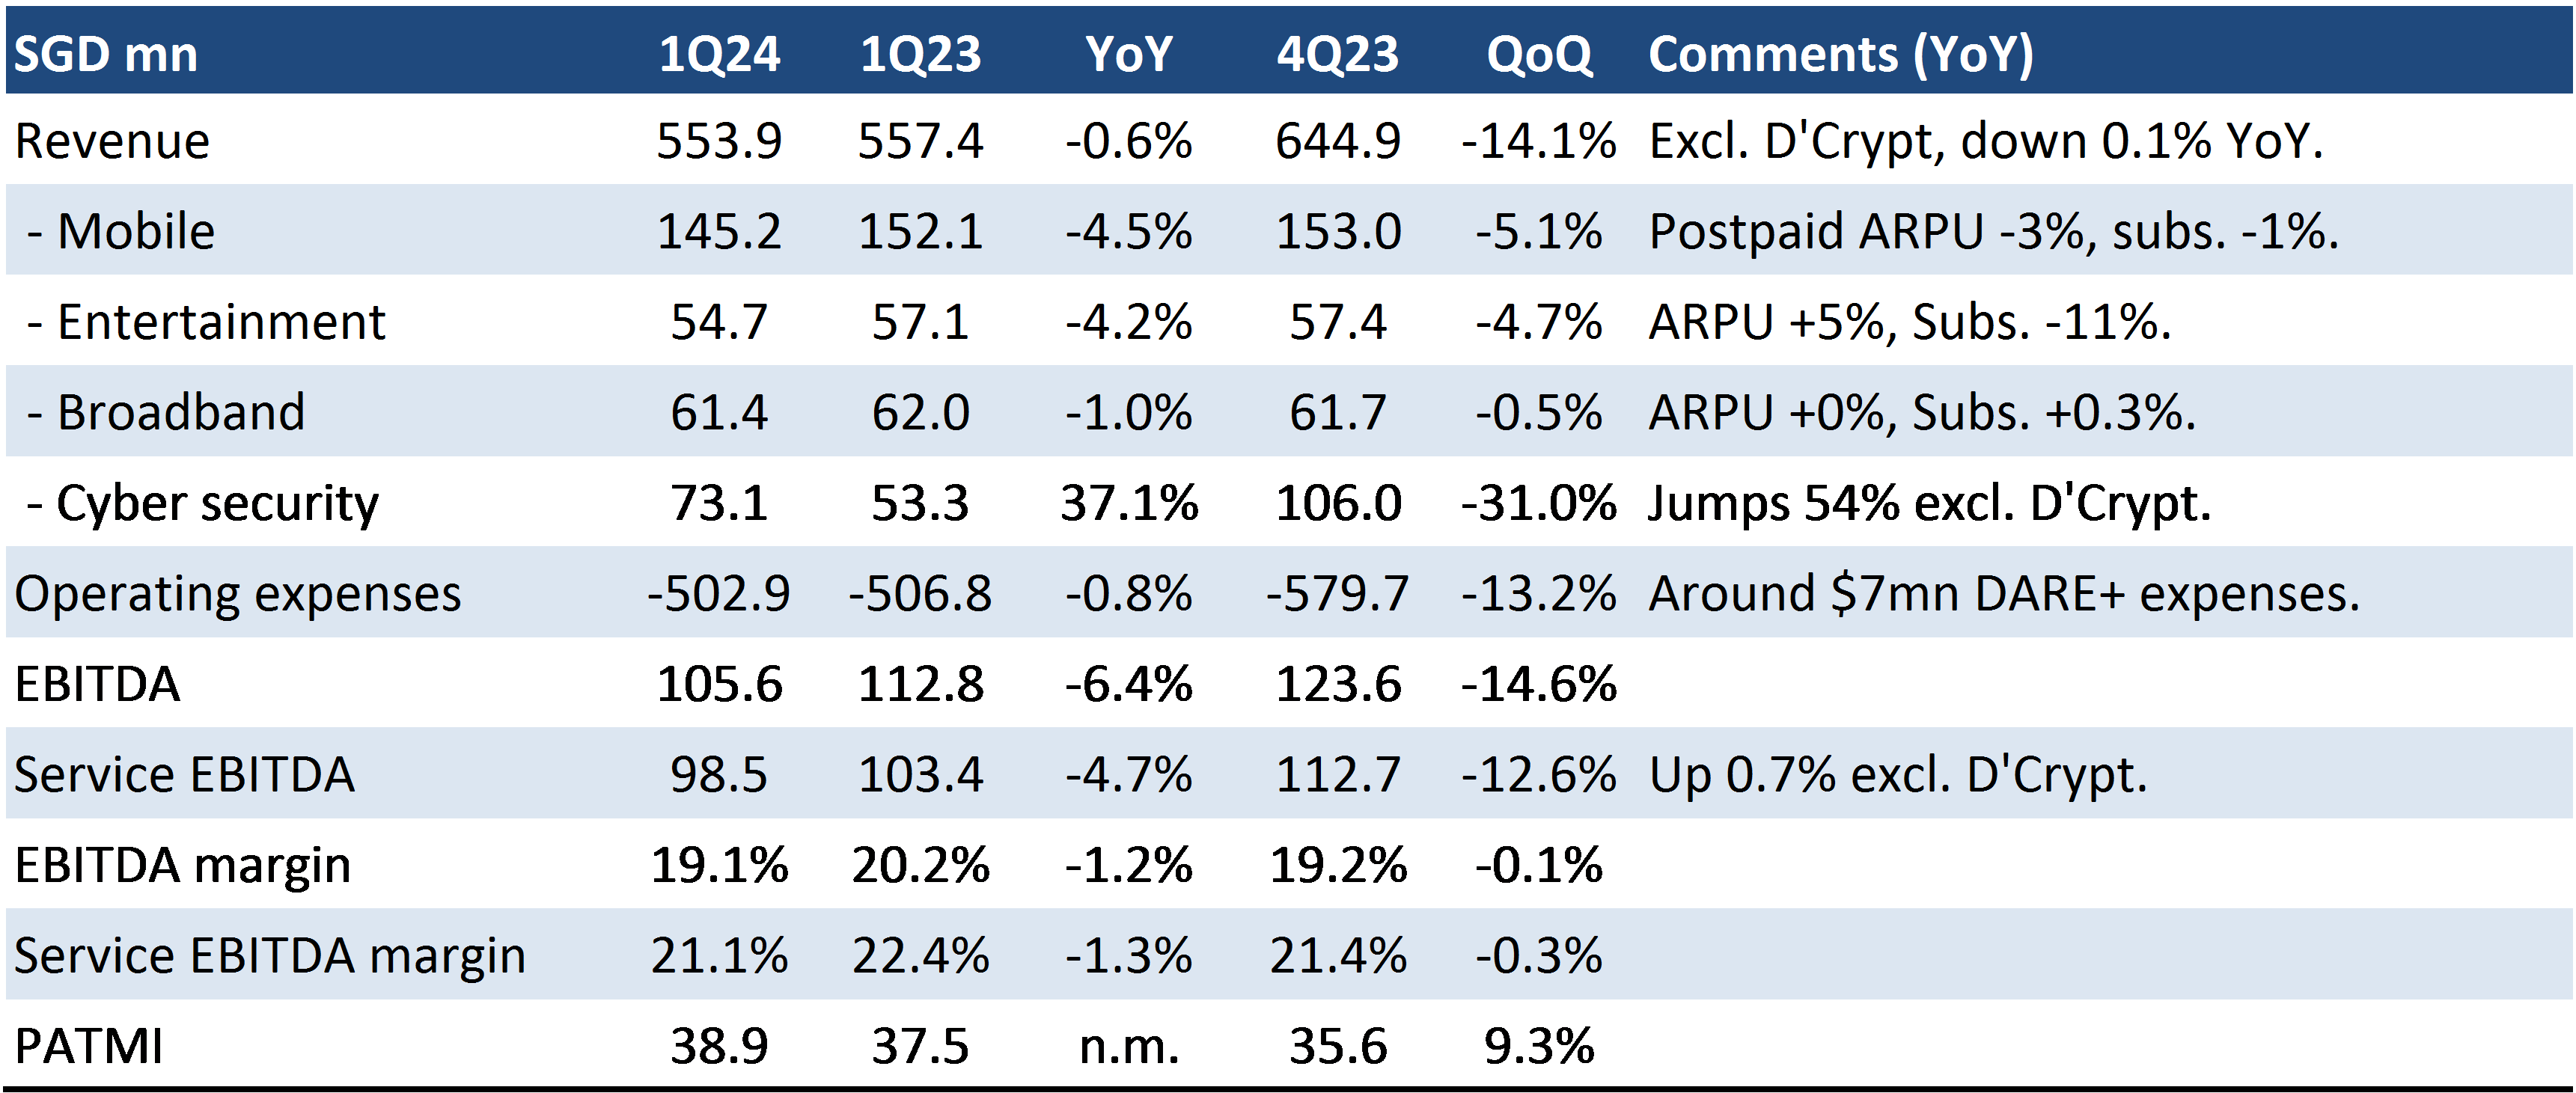
- 1Q24 results were within expectations and management full-year guidance. FY24 revenue and EBITDA were 23%/22% of our FY24 estimates.
- Service EBITDA was up 0.7% YoY to S$108.4mn excluding D’Crypt which was disposed of in February 2024. Earnings were pulled down by a contraction in mobile and entertainment revenue.
- Mobile competition is more intense than expected. 1Q24 mobile decline is the highest in 11 quarters, or since the pandemic began. We believe competition from MVNOs and MNOs has affected the lucrative roaming segment. Our forecasts are largely unchanged. The target price of S$1.29 is maintained, 6.5x FY24e EV/EBITDA, in line with other mobile peers. And ACCUMULATE recommendation maintained. This year, around 90% of the DARE+ S$270mn investments will be completed. Earnings this year are expected to be sluggish, with DARE+ opportunities in cost and revenue materialising only next year.
Results at a glance
The Positives
+ Strong cybersecurity revenue. Cybersecurity expanded 37% YoY to S$73mn. Excluding D’Crypt, Ensign's revenue would have jumped 54% to S$64.7mn. The surge in revenue was due to project delivery, and 1Q is typically weak on a seasonal basis. Ensign continues to add headcount and fixed costs, which affect its profitability.
The Negative
- Weakness in mobile APRU. Mobile revenue declined 4.5% to S$145mn. The large drag in revenue stems from lower postpaid ARPU and competition. Apart from competition, excess data and voice usage charges have been falling as packages enjoy higher bandwidth.
Get access to all the latest market news, reports, technical analysis
by signing up for a free account today!
Login
The full article is only available for premium content subscribers. To continue reading this article, please log in:
Not a Premium Content Subscriber yet? Sign up here!
- Home >
- Phillip Research Report