Spotify Technology S.A.- Navigating AI risk with strong growth
-
3Q26 revenue was within expectations while 3Q26 PATMI underperformed slightly, with 9M26 revenue/PATMI at 73%/70% of our FY26e forecasts. 3Q26 revenue grew 16% YoY, primarily driven by stronger Premium revenue growth (+17% YoY), supported by both subscriber growth and higher ARPU. 3Q26 PATMI underperformed due to lower net finance income, driven by higher foreign exchange losses and a higher effective tax rate.
-
User growth remained resilient, with MAUs reaching 788mn (+11% YoY), while Premium subscribers increased to 306mn (+9% YoY).
-
We downgraded our recommendation from BUY to ACCUMULATE with an unchanged target price of US$650 due to recent share price movement. Our estimates remain unchanged, with a WACC of 7.5% and a terminal growth rate of 3.5%. SPOT is turning AI from a disruption risk into a growth and monetisation lever. AI-creation tools, audiobooks and other products with higher average revenue per user broaden the path for mid-teens revenue growth and further monetisation, extending SPOT's lead as the world's largest audio platform.

The Positives
+ Strong Premium growth supported by subscriber additions and pricing power. Premium
revenue +17% YoY, driven by 9% subscriber growth and 7.5% ARPU expansion. (Figure 2).
Premium subscribers reached 306mn (+6mn QoQ), exceeding guidance by 1mn. We view the
resilience in Premium subscriber additions despite price increases positively, reinforcing
pricing power as SPOT's key growth lever. Notably, SPOT has implemented three US price
hikes since 2023 with minimal disruption to subscriber growth. Management guided for a
further 10mn premium subscriber addition in 4Q26e.
+ Advertising momentum improving following platform revamp. Advertising revenue
growth accelerated to 9% YoY in 3Q26, from 3% in each of the previous two quarters,
reflecting early benefits from SPOT's ongoing rebuild of its advertising technology stack.
Growth was primarily driven by automated biddable channels, which now account for 40% of
advertising revenue (3Q25: 30%), alongside growing podcast sponsorships. Management
expects advertising growth to continue accelerating towards double digits in 4Q26e. SPOT's
499mn ad-supported MAU takes 63% of MAUs but generates only 10% of total revenue. We
see huge monetisation potential in the gap, e.g. a lower-priced ad-free subscription tier.
+ Navigating the AI risk well. SPOT is addressing AI-related risks through partnerships with
major record labels, including Sony, Universal Music Group and Warner Music Group, to
develop responsible AI products, alongside tighter policies against unauthorised AI voice
cloning and AI-generated spam. Meanwhile, integrations with AI platforms such as ChatGPT,
Claude and Meta's Muse help SPOT maintain its relevance as AI reshapes music discovery.
Continued expansion into audiobooks, creator tools and the Partner Program also diversifies
its offering beyond music, strengthening user engagement and reducing its reliance on
traditional music streaming.
Spotify Technology S.A.- Strengthens the long-term story
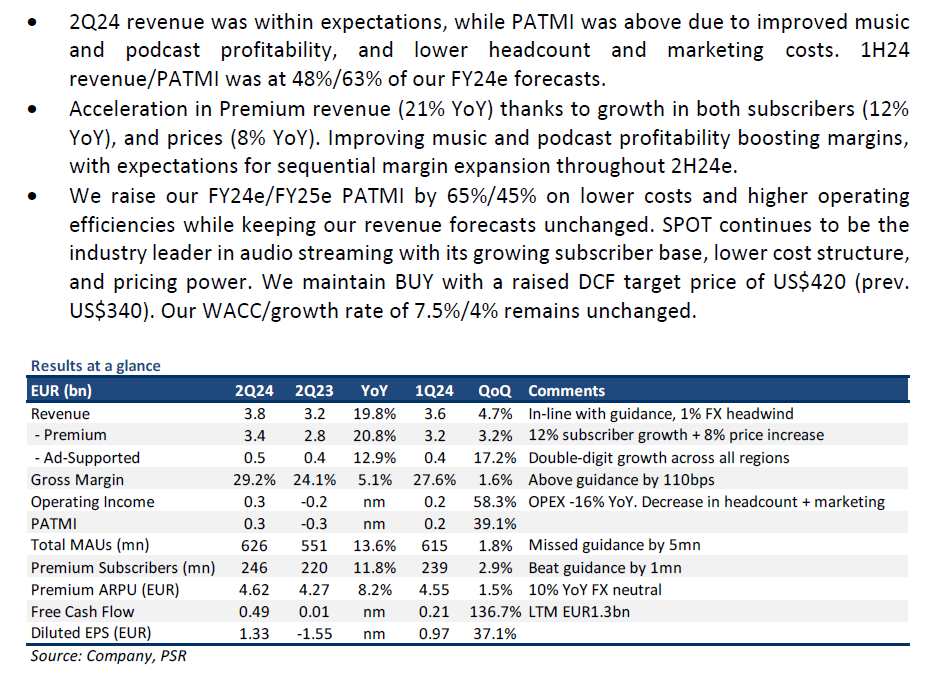
- Both 2Q26 revenue and PATMI were within expectations. 2Q26 revenue grew 14% YoY, primarily driven by stronger Premium revenue growth (+16% YoY) following recent price increases. 2Q26 revenue/PATMI were at 49%/48% of our FY26 forecasts.
- User growth remained resilient, with MAUs reaching 777mn (+12% YoY), while Premium subscribers increased to 300mn (+9% YoY, +2% QoQ).
- We maintain our Buy recommendation with an unchanged target price of US$650. Our estimates remain unchanged, with a WACC of 7.5% and a terminal growth rate of 3.5%. SPOT continues to deliver strong user momentum and improve profitability. Revamped advertising is also expected to further support margins. Its key competitive advantage lies in its large, proprietary dataset of user listening behaviour, which allows superior personalisation and discovery, strengthens platform stickiness, and supports continued pricing power.

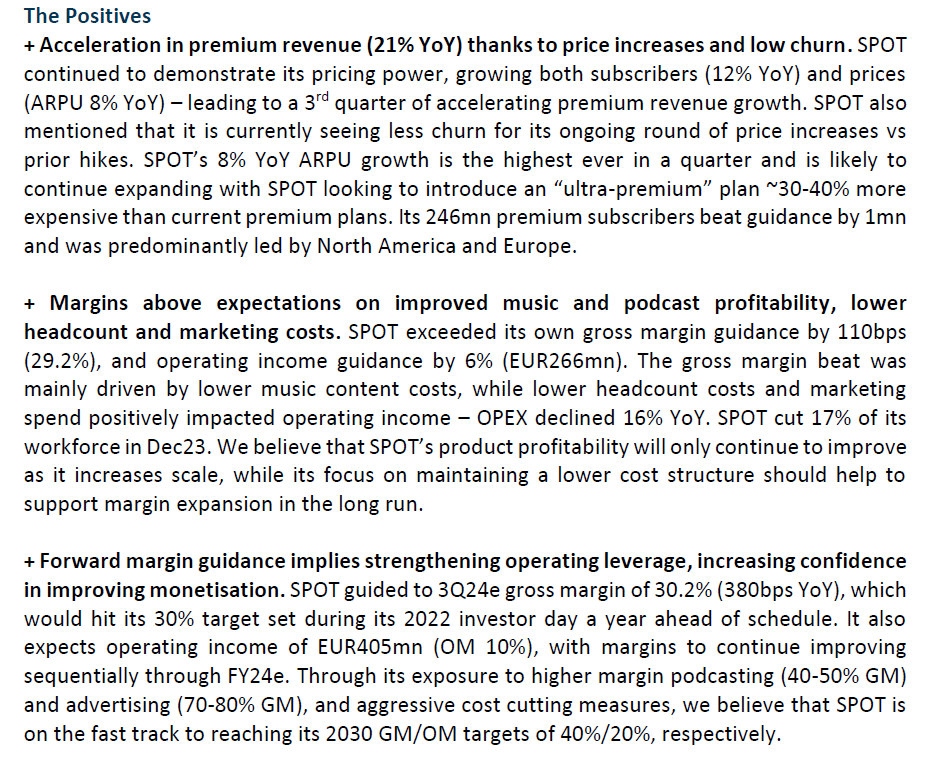
The Positives
+ Revenue growth accelerates on resilient subscriber growth and pricing. Revenue growth
accelerated to 14% YoY (1Q26: +8%; 4Q25: +7%), driven by strong Premium revenue growth
of 15% YoY. Premium ARPU increased 7% YoY, benefiting from the 8% U.S. price increase
implemented in Feb 2026, while Premium subscriber growth remained resilient at 9% YoY and
beat guidance by 1mn, highlighting healthy demand despite recent price increases. Gross
margin reached a record 33.4%, exceeding guidance by 30bps, supported by improvements
across both Premium and Ad-Supported segments.
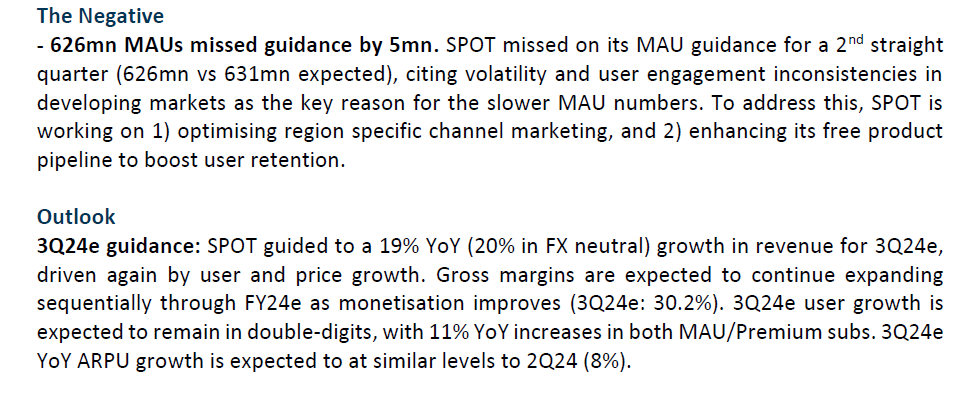
+ Priority shifting from scale to growth. MAUs reached 777mn (+12% YoY), providing SPOT
with a sizeable base of free users, particularly across emerging markets. Management is now
shifting its focus from maximising MAU growth toward improving monetisation, including
higher ad loads and greater friction within the free tier to drive Premium conversion. While
these initiatives are expected to moderate near-term MAU additions, management does not
expect Premium subscriber growth to be affected. 3Q26 revenue is guided to €5.0bn, implying
a 17% YoY growth (200bps FX tailwind).
+ Advertising at the point of inflection. While Ad-Supported revenue growth remained
modest at +1.4% YoY, SPOT has largely completed its two-year advertising infrastructure
overhaul, with 99% of impressions now served through its proprietary ad stack. Automated
channels increased to 40% of Ad-Supported revenue (1Q26: 30%), while active advertisers
surged 60% YoY. With direct-sales declines stabilising and automated buying continuing to
scale, management reiterated its expectation for advertising growth to inflect toward
double digits in 2H26. Increased automation could also support Ad-Supported gross margin
expansion from the current 20% to 40% over the long term.
Spotify Technology S.A.- From music app to data powerhouse
-
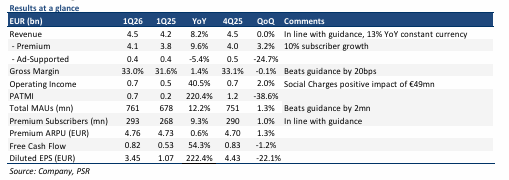
1Q26 revenue grew 8% and was within expectations. 1Q26 PATMI exceeded our estimates and jumped 220% YoY, driven by a €49mn benefit from social charges (due to share price movements) as well as a favourable revenue mix and cost discipline. 1Q26 revenue/PATMI were at 23%/30% of our FY26 forecasts.
-
User metrics ramped up to 761mn MAUs (+12% YoY). Premium subscribers grew to 293mn (+10% YoY, +1% QoQ).
-
We maintain our Buy recommendation with an unchanged target price of US$650. Our estimates remain unchanged, with a WACC of 7.5% and a terminal growth rate of 3.5%. SPOT continues to deliver strong user momentum and improve profitability, and its unique and hard-to-replicate dataset is its biggest advantage. Near-term margins may face some pressure from ongoing investment in AI and ad-tech, but these are strategic steps that position the company to emerge stronger with improved monetisation over the long term.
The Positives
+ Strong top-line growth, user momentum still intact. SPOT continued to deliver solid top
line user momentum in 1Q26, with MAUs reaching 761mn (+12% YoY), exceeding guidance
by 2mn. Growth was led by Rest of World and North America, supported by the enhanced
free-tier rollout, which improved engagement, with users “listening and watching more days
per month”. Management highlights the number of days per month as a key driver of
retention and lifetime value, reinforcing the company’s broader monetisation framework.
+ Margins continue to expand. Spotify delivered a gross margin of 33% (+133bps YoY),
surpassing guidance. The margin expansion was driven by the favourable cost of revenue and
revenue mix. This marks continued progress in SPOT’s multi-year profitability journey,
supported by Premium ARPU expansion (+5.7% YoY) and disciplined cost management,
including stable headcount. Management reiterated expectations for full-year margin
expansion in FY26, despite near-term reinvestment in AI and product initiatives, highlighting
confidence in sustaining operating leverage as the business scales.
+ AI-driven personalisation is accelerating engagement and reinforcing long-term
monetisation. SPOT continues to deepen its AI capabilities across the platform, with
features such as AI DJ reaching 94mn users (out of 293mn subscribers) and new launches
like SongDNA scaling to 52mn users within just four weeks, reflecting rapid adoption. AI is
enabling faster product iteration, lower cost per feature, and deeper personalisation. We
see SPOT increasingly evolving from a music app into a data powerhouse, leveraging its
0.76bn user base and decades of listening data to build highly granular “taste” profiles that
are difficult to replicate, providing a structural advantage.
Spotify Technology S.A.- Record MAU addition
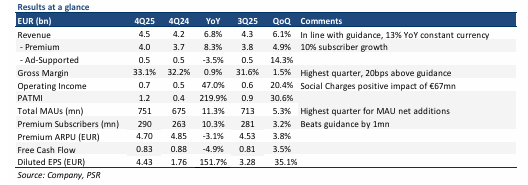
- 4Q25 revenue grew 7% and was within expectations. 4Q25 PATMI exceeded our estimates and jumped 220% YoY, driven by favorable content costs and a €67mn benefit from social charges. FY25 revenue/PATMI were at 99%/130% of our FY25 forecasts.
- User metrics ramped up to 751mn MAUs (+11% YoY), the highest quarter for MAU net additions. Premium subscribers grew in double digits to 290mn (+10% YoY).
- We upgrade our rating from ACCUMULATE to BUY rating due to recent price performance while maintaining a DCF target price of US$650 as we roll over our valuations to FY26e. Our FY26e forecast, terminal growth, and WACC assumptions remain unchanged. SPOT has demonstrated strong pricing power and monetization. AI-driven personalization should further deepen user attachment.
The Positives
+ Engagement is strong with record MAU addition. SPOT continued to expand its user base,
adding a record 51mn MAUs in 4Q25 to reach 751mn MAUs by year-end (+11% YoY), while
Premium Subscribers also grew solidly (+10% YoY). Management attributed the healthy
growth to stronger engagement-led conversion, particularly from product moments such as
the Wrapped campaign (300mn users engaged, +20% YoY; 630mn social shares, +42% YoY),
which delivered the highest single-day subscriber intake in the company’s history. The
enhanced free-tier rollout also helped tighten the funnel by improving retention and
downstream monetization, reinforcing the MAU → engagement → monetization cycle.
+ Margins are improving across both premium and ad-supported. SPOT showed continued
margin expansion alongside growth, with gross margin improving to 33.1% (+150 bps YoY), its
highest level to date. Margin expansion is across both Premium and Ad-Supported businesses.
The expansion was supported by favorable content costs, reflecting better monetization
relative to royalty costs and mix benefits from higher-margin formats. Management also
guided that Jan 26’s U.S. price increase (+8.3%) is expected to lift ARPU (guided at +5–6% in
1Q26), allowing revenue growth to outpace content cost growth. We expect both gross and
operating margins to continue improving in FY26 as pricing and scale efficiencies strengthen
operating leverage.
+ AI is a structural tailwind. New features such as AI DJ and Prompted Playlists show how
natural-language interaction can deepen personalization, increase engagement, and
ultimately improve retention and lifetime value. What we think differentiates SPOT is its
proprietary “language-to-taste” dataset, built from hundreds of millions of listener data
points, which is difficult to replicate and unlikely to be achieved with generic AI models. As
such, AI acts as a catalyst, strengthening the company’s existing monetization framework by
enhancing discovery, engagement, and pricing power.
Spotify Technology S.A. – Strong pricing power in play
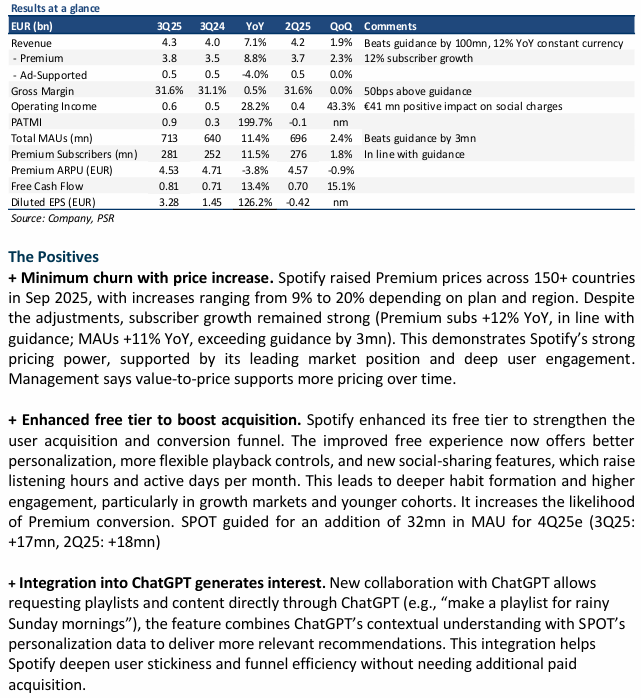
- 3Q25 revenue/PATMI grew 7% and 200% YoY respectively and were within expectations. PATMI’s big jump is mainly due to royalty accounting adjustment and reduced social charges. 9M25 revenue/PATMI were at 75%/70% of our FY25e forecasts.
- User metrics ramped up to 713mn MAUs (+11% YoY), beating guidance by 3mn. Premium subscribers grew in healthy double digits to 281mn (+12% YoY) despite a 9%-20% price increase in multiple markets.
- We increased FY25e/FY26e revenue and PATMI by 1%/1% and 3%/4% respectively to account for the recent increase in pricing. We have also lower SPOT’s beta to 0.75 to reflect improving revenue stability and demonstrated pricing power. We upgrade our recommendation from REDUCE to ACCUMULATE and our DCF target price is raised to US$650 (prev. US$600).
Spotify Technology S.A.- Strong user growth, but soft guidance
-
Both 2Q25 revenue and adj. PATMI fell short due to execution delays in scaling ad capabilities. 1H25 revenue/adj. PATMI were at 45%/30% of our FY25e forecasts.
-
User metrics ramp up to 696mn MAUs (+11% YoY), in line with guidance. Premium subscribers grew in healthy double digits to 276mn (+12% YoY). Margins are improving across both premium and ad-supported. Guidance for 3Q25e, however, remains soft (revenue +5% YoY) due to near-term investments.
-
We keep our FY25e revenue assumption unchanged. We decrease FY25e PATMI by 12% to account for the extra social charges after share price strength. Our DCF target price remains unchanged at US$600. We upgraded our recommendation from REDUCE to NEUTRAL due to the recent share price performance. While user and subscriber growth remain robust, lower 3Q25e guidance due to near-term investments —combined with high operating costs and currency drag—has tempered near-term expectations.

Spotify Technology S.A.- Growth story remains intact, yet full valuations
- 1Q25 revenue was within expectations while PATMI fell short due to €76mn in social charges - €58mn above forecast - driven by a surge in the share price. 1Q25 revenue/PATMI were at 24%/10% of our FY25e forecasts.
- User metrics ramp up to 678mn MAUs (+10% YoY), in line with guidance. Premium subscribers grew in healthy double digits to 268mn (+12% YoY). Management has indicated no change in demand due to macro-economic conditions and guided continued strong growth in revenue, MAUs, and premium subs for 2Q25.
- We keep our FY25e revenue assumption unchanged. We decrease FY25e PATMI by 4% to account for the extra social charges after share price strength. Our DCF target price remains unchanged at US$600. We downgraded our recommendation from NEUTRAL to REDUCE due to the recent share price strength. SPOT continues to be the industry leader in audio streaming with its growing subscriber base, lower cost structure, and pricing power. Yet we do not see much upside due to full valuations.
Spotify Technology S.A. – First year of profitability
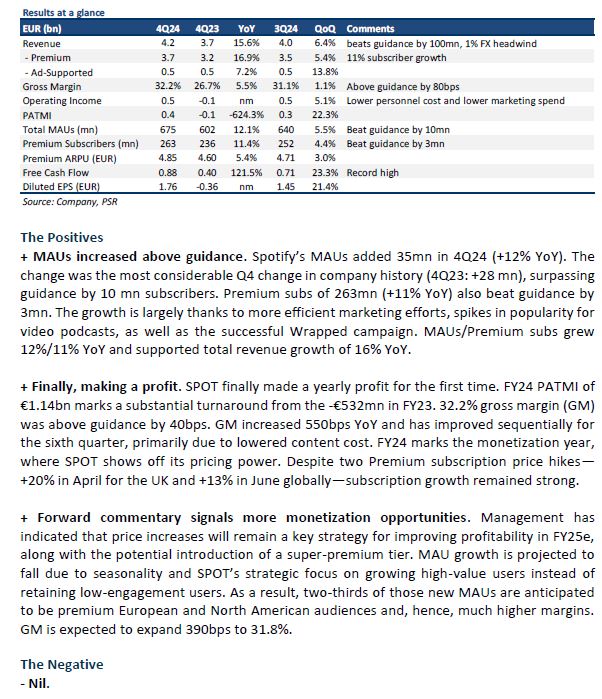
- 4Q24 results were within expectations. FY24 revenue/PATMI were at 100%/102% of our FY24e forecasts. Revenue grew 16% YoY, while net margin expanded 5.5% YoY.
- User metrics ramp up, with 675mn MAUs above guidance by 10mn. Premium subscribers are still growing healthy double digits to 263mn (+11% YoY). Further margin expansion is expected into FY25e due to gaining greater scale, lowering costs and prioritization on premium subscribers.
- We roll over another year of valuations and keep our FY25e assumptions unchanged. Our DCF target price has been raised to US$600 (prev. US$485), but we downgraded to NEUTRAL from ACCUMULATE due to recent share price gains. SPOT continues to be the industry leader in audio streaming with its growing subscriber base, lower cost structure, and pricing power. Yet we do not see much upside due to full valuations.
Spotify Technology S.A. – More monetisation the key driver
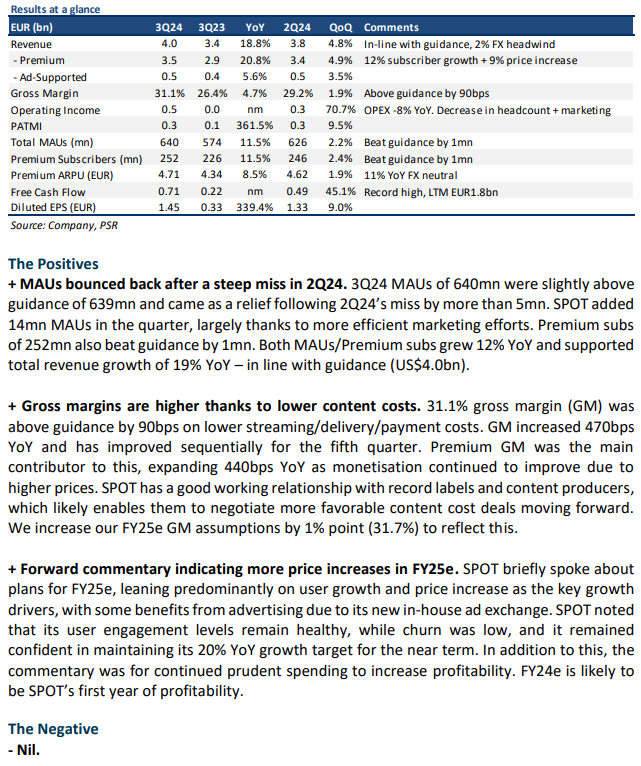
- 3Q24 results were within expectations. 9M24 revenue/PATMI was at 74%/62% of our FY24e forecasts. Revenue grew 19% YoY, while net margin expanded 6% points YoY.
- User metrics still improving, with 640mn MAUs above guidance by 1mn. Premium subscribers are still growing healthy double digits to 252mn (12% YoY). Further margin expansion is expected into FY25e due to gaining greater scale and lowering costs.
- We keep our FY24e assumptions unchanged, but raise FY25e PATMI by 9% on higher profitability. Our DCF target price has been raised to US$485 (prev. US$420), but we downgrade to ACCUMULATE from BUY due to recent share price gains. SPOT continues to be the industry leader in audio streaming with its growing subscriber base, lower cost structure, and pricing power.
Spotify Technology S.A. – Prime example of pricing power
Get access to all the latest market news, reports, technical analysis
by signing up for a free account today!
Login
The full article is only available for premium content subscribers. To continue reading this article, please log in:
Not a Premium Content Subscriber yet? Sign up here!
- Home >
- Phillip Research Report