Sea Ltd.- Significant runway ahead
- 2Q26 revenue exceeded expectations slightly due to stronger-than-expected Shopee and Monee growth, while PATMI was in line as elevated sales & marketing expense and provision for credit losses (+52%, +65% YoY, respectively) weighed on earnings. 1H26 revenue/PATMI was at 52%/48% of our FY26e estimates.
- Revenue delivered strong growth of 48% YoY, supported by strong Shopee growth (+49% YoY) and rapid loan-book expansion at Monee (+59% YoY). Garena shows a slight slowdown, with books +16% YoY.
- We maintain our BUY recommendation, with an unchanged target price of US$170.00. We increase our FY26e revenue assumptions by 3% to account for stronger-than-expected growth at Shopee and Monee. We also increase our sales and marketing expense and the provision for credit losses by 5% and 3%, respectively, to account for elevated investment and credit expansion. Terminal growth and WACC assumptions remain unchanged. Both fulfilment and Monee are still in the early stages of penetration; we believe the significant runway across both businesses should support continued margin improvement and greater earnings scalability over time.

Positives
+ Shopee growth remains healthy. GMV grew 28% YoY to US$38.3bn, marking eight
consecutive quarters of sequential growth, supported by strong user acquisition and
engagement (monthly active buyers +18% YoY, new active buyers +35% YoY, and purchase
frequency +8% YoY). Advertising remains a driver of growth (ad revenue +70% YoY and ad
take rate +90 bps YoY). Investments in logistics, fulfilment, ShopeeVIP and content are gaining
scale (fulfilment volume grew +20% QoQ, VIP membership reached +25% QoQ, and
livestream/short-video orders grew +50% YoY). Shopee maintained its 25% FY26 GMV
growth.
+ Refined credit-risk model helps unlock further Monee expansion. Monee further enhances
its credit-risk models by combining transactional data with a growing pool of external data,
enabling it to better assess users with limited history. Its latest models improved approval
rates by 10% while maintaining similar risk levels, and AI-based income document verification
reduced review time by 95%. These improvements allow Monee to aggressively expand its
borrower base. Its loan book reached US$11.1bn (+52% YoY) while the 90-day NPL ratio
remains low at 1.0%. Monee added 5.3mn first-time borrowers during the quarter and active
credit users grew 34% YoY to 40mn, providing further runway to expand both within and
beyond the Shopee ecosystem.
Sea Ltd.- 2026 an investment year
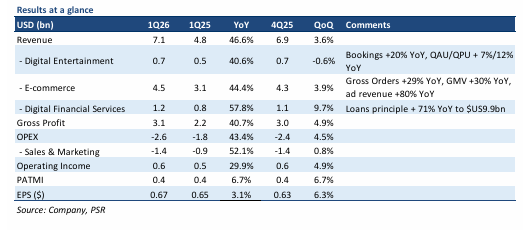
- Both 1Q26 revenue was in line with expectations, while PATMI underperformed slightly due to sharply increased growth investments in Shopee. (Sales & Marketing expense +52% YoY). 1Q26 revenue/PATMI was at 24%/22% of our FY26e estimates.
- Revenue delivered strong growth of 47% YoY, supported by strong Shopee growth (+44% YoY), rapid loan-book expansion at Monee (+41% YoY), and continued strength at Garena (bookings +20% YoY).
- We maintain our BUY recommendation, with an unchanged Target Price of US$170.00. We increase our FY26e and FY27e sales and marketing expense assumptions by 3% and 2% (56 % of OPEX) to account for the increase in investment. Revenue, Adj. PATMI, terminal growth and WACC assumptions remain unchanged. We believe the investments are strategically beneficial over the longer term as they support user acquisition, merchant retention and ecosystem engagement, strengthening Shopee’s competitive moat.
Positives
+ Aggressive investment pushing Shopee expansion. Shopee continued delivering strong
growth (1Q26 GMV +30% YoY, gross orders +29% YoY) as management aggressively ramps up
investments in FY26, with Sales & Marketing expenses rising +52% YoY (vs. +30% YoY in both
3Q25 and 4Q25 despite similar GMV growth). Shopee continues to deepen ecosystem
stickiness through content-commerce initiatives, with ShopeeVIP subscribers +40% QoQ (20%
of Asia GMV), live-streaming and short-video orders +50% YoY (>25% of SEA physical orders),
and YouTube-driven orders more than doubling YoY. Logistics capabilities also continued to
improve, with stronger adoption of instant delivery. Management maintained its FY26e
guidance of 25% GMV growth and reiterated its continued investments in fulfilment, logistics,
and the VIP ecosystem to further strengthen Shopee’s long-term competitive moat.
+ Strong Monee growth with stable NPLs. Loan principal outstanding grew +71% YoY to
US$9.9bn, supported by stronger borrower acquisition, deeper user engagement and
expansion into broader credit use cases. Monee is expanding into more affluent borrowers
with higher credit limits and longer loan tenures. Off-Shopee lending penetration also
continues to scale, with Monee pushing for higher-ticket consumption scenarios. The 90-day
NPL ratio remained stable at 1.1%, close to high-quality traditional bank levels. We believe
Monee’s key competitive advantage continues to lie in its rich e-commerce ecosystem data,
which enables more effective underwriting, better risk assessment and lower customer
acquisition costs compared to many standalone fintech lenders. (DBS: 1.1%, Affirm: 2-3%)
+ Garena delivered its strongest quarter since FY21. Garena 1Q26 revenue +41% YoY, with
bookings growing +20% YoY, driven by continued strength in Free Fire alongside record
contribution from Arena of Valor. Free Fire’s Jujutsu Kaisen collaboration generated over 700
million official content views, demonstrating Garena’s continued ability to execute successful
global IP partnerships and sustain user engagement through localised content strategies. Arena
of Valor also achieved record quarterly bookings in its 10th year of operation, with management
explicitly stating the recovery is “not a one-off” and expecting 2026 to be a record year for the
franchise.
Sea Ltd.- Investment strengthens Shopee’s competitiveness
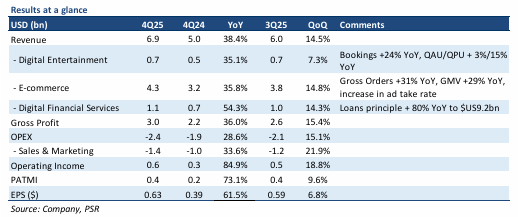
- 4Q25 revenue was in line with expectations, while PATMI underperformed due to elevated logistics, fulfilment, and user-engagement investments at Shopee. FY25 revenue/PATMI was at 103%/89% of our estimates.
- Revenue grew 38% YoY while PATMI grew 73% YoY, supported by strong Shopee momentum (GMV +29% YoY) with higher ad take rates, rapid loan-book expansion at Monee (+80% YoY), and continued strength at Garena (bookings +24% YoY).
- We maintain our BUY recommendation. We roll forward our valuations to FY26e and reduce our FY26e PATMI by 1% to account for increased investment in e-commerce. Our DCF target price remains unchanged at US$170, with a terminal growth rate of 4.0% and a WACC of 7.6%. Increased investment should further strengthen Shopee’s competitive positioning, supporting GMV growth and higher monetization through ads and commissions.
Positives
+ Strong Shopee momentum to continue. Shopee continued strong growth (4Q25 GMV +
29% YoY, gross orders +30% YoY), supported by stronger monetisation as ad revenue + 70%
YoY (ad-paying sellers +20% YoY and average ad spend +45% YoY). Shopee continues to
strengthen its ecosystem through logistics scale, higher user engagement (monthly active
buyers +15% YoY), and initiatives such as Shopee VIP membership (subscribers doubling in
just one quarter) and a growing content ecosystem (orders driven by YouTube content >3x
YoY). Management expects momentum to continue, guiding 25% GMV growth in FY26e,
supported by further investments in fulfilment, logistics and user engagement to deepen
Shopee’s long-term competitive moat.
+ Strong Monee growth with stable NPLs. Loan principal +80% YoY to US$9.2bn, driven by
stronger user acquisition, deeper engagement, and broader credit use cases. Active credit
users reached +40% YoY after shifting from a whitelist model to an “all-can-apply” approach.
Engagement also improved, with average loan outstanding per user up 27% YoY as SE offered
higher limits and longer tenures to users with stronger credit histories. In addition, off-Shopee
SPayLater loans + 300% YoY, accounting for >15% of the total SPayLater portfolio (around 30%
in Malaysia), reflecting expansion beyond the Shopee ecosystem into offline consumption
scenarios. The 90-day NPL ratio remains stable at 1.1%, supported by improved underwriting
models that leverage ecosystem data and AI. Monee remains a key profit driver, with FY25
adjusted EBITDA exceeding US$1bn, now surpassing Shopee and second to Garena.
+ Garena remains durable and monetizable at scale. FY25 bookings +37% YoY to US$2.9bn.
Management highlighted two consecutive years of >30% YoY bookings growth for Free Fire,
strong content execution via major IP collaborations, and encouraging traction from newer titles
such as EA SPORTS FC Mobile, supporting confidence that gaming can remain a meaningful profit
pillar into FY26. (50% of group EBITDA in FY25 vs. 63% in FY24)
Sea Ltd.- All rounded growth continues
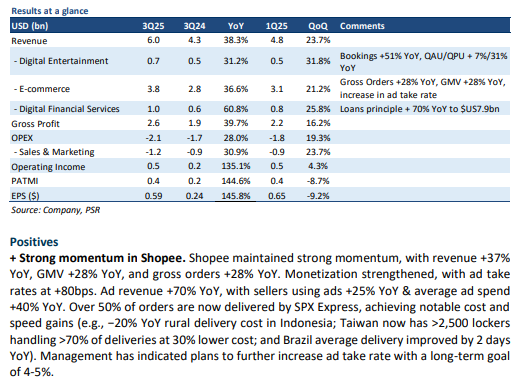
- 3Q25 revenue was in line with expectations, while PATMI underperformed mainly because Shopee’s higher logistics, fulfilment, and user-engagement investments. 9M25 revenue/PATMI was at 75%/60% of our FY25 estimates.
- Revenue rose 38% YoY, driven by Shopee’s strong momentum with higher commission and ad take rates, Monee’s rapid loan-book expansion (+70% YoY), and Garena’s best performance since 2021 on the back of successful IP collaborations.
- We raised our FY25/26 revenue by 3%/4% to reflect improved growth in all three segments. We increase FY25/26 selling & marketing expense by 5% to account for the elevated investment. Our DCF target price remains unchanged at US$170, with a terminal growth rate of 4.5% and a WACC of 7.6%. We upgrade our recommendation from NEUTRAL to BUY due to recent share price movement.
Sea Ltd.- Profitability surge and Garena slowdown
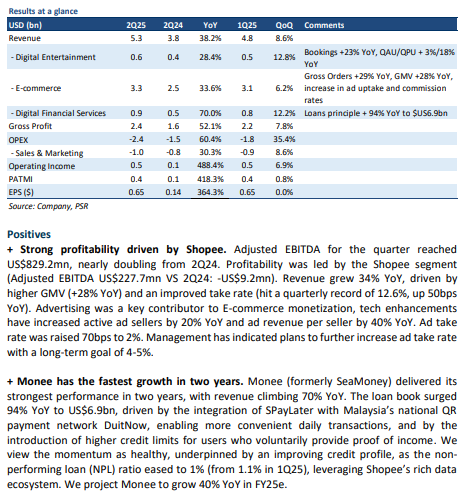
- 2Q25 revenue/PATMI were in line with expectations, with its 39% YoY growth primarily driven by strength in Shopee (+34% YoY in revenue) and Monee (+70% YoY in revenue). 1H25 revenue/PATMI was at 48%/46% of our FY25 estimates.
- PATMI grew 418% YoY to US$414mn. Shopee and Monee maintained strong momentum, fueled by higher take rates in commissions & ads, as well as robust loan book growth. Garena shows signs of a slowdown in growth.
- We maintain our NEUTRAL recommendation. We raised our FY25 revenue/PATMI by 1%/9% to reflect growth in Monee, Shopee, as well as the improvements in take rates. We raised our DCF target price to US$170 (previously US$160) given the strong momentum in e-commerce and financial services as well as improved monetization, with an unchanged terminal growth rate of 4.5%, and a WACC of 7.6%. We see limited upside due to stretched valuations.
Sea Ltd. – Outperformance likely to continue, but valuations stretched
Recommendation: NEUTRAL (Downgraded) , Last done: US$162.72, TP: US$160, Analyst: Helena Wang
- 1Q25 revenue/PATMI were in line with expectations, with its 30% YoY growth primarily driven by strength in Shopee (29% YoY) and Monee (58% YoY). 1Q25 revenue/PATMI was at 23%/25% of our FY25 estimates.
- All three segments —Shopee, Monee, and Garena —maintained their strong momentum, fueled by higher take rates in commissions and ads, robust loan book growth, and strong bookings.
- We downgrade our recommendation from Accumulate to Neutral due to the recent share price rally. We raised our FY25 revenue/PATMI by 2%/13% to reflect growth in Monee, Garena, and continued improvements in cost efficiency. We also raise our terminal growth rate assumption to 4.5% (previously 4%), reflecting the long-term growth potential of Monee as it penetrates the large unbanked population in Southeast Asia. We have raised our DCF target price to US$160 (previously US$140), with an unchanged WACC of 7.6%. After the significant price rally, we see minimal upside.


Sea Ltd. – Further growth ahead
- Shopee and SeaMoney maintained their growth momentum, driven by higher take rates
in commissions and ads, as well as robust loan book growth. We believe ad and off-
Shopee loans are good growth opportunities for SE.
- Garena has experienced strong 20% YoY in user metrics throughout FY24, with revenue
typically lagging. 4Q24 marks its first YoY revenue increase since 2Q22; we believe the
decline has bottomed out and expect revenue growth of 9% in FY25.
- We upgrade our recommendation from Neutral to Accumulate due to recent share price
movement. We maintain our DCF target price at US$140, with an unchanged terminal
growth rate of 4% and WACC of 7.6%. SE has demonstrated strong growth momentum
and monetization capabilities in Shopee and SeaMoney, and we expect growth in Garena
in FY25.
Sea Ltd. – Growth momentum continues
- 4Q24 revenue was in line with expectations, with its 37% YoY growth primarily driven by strength in Shopee (41% YoY) and SeaMoney (55% YoY). PATMI missed due to a higher-than-expected investment loss of $0.25bn. Excluding the investment loss, FY24 revenue/PATMI was at 103%/98% of our FY24 estimates.
- Shopee and SeaMoney maintained their strong momentum, fueled by higher take rates in commissions and ads, along with robust loan book growth. Garena's metrics remain positive, but the impact on top and bottom-line growth has been less significant than expected.
- We upgrade our recommendation from Reduce to Neutral after rolling over the results for another year. We raise our DCF target price to US$140 (prev. US$100), with an unchanged terminal growth rate of 4% and WACC of 7.6%. SE has demonstrated strong growth momentum and monetization capabilities in Shopee and SeaMoney, yet we see limited upside to valuations due to recent share price strength.


Sea Ltd. – High growth across all businesses
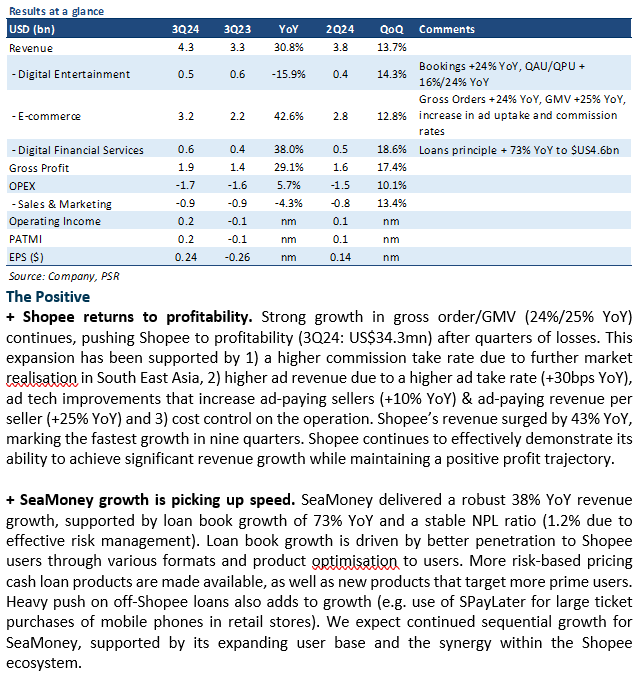
- 3Q24 revenue exceeded expectations, with its 30% YoY growth primarily driven by strength in Shopee (43% YoY) and SeaMoney (38% YoY). PATMI was missed due to continuously high sales and marketing spending that ate into profitability. 9M24 revenue/PATMI was at 76%/33% of our FY24 estimates. We expect PATMI to be backloaded into 4Q24e as the ramp-up of Shopee and SeaMoney continues and the late recognition of gaming revenue.
- All three key business segments show strong growth, driven by increased take rates in Shopee, strong loan book growth in SeaMoney, and a highly engaged user base for Garena’s Free Fire (growth reflected in user metrics due to late recognition of revenue).
- We downgrade our recommendation from Neutral to Reduce after considering recent share price movement. We raised our FY24e revenue/PATMI by 4%/1% to account for higher Shopee and SeaMoney growth. We raise our terminal growth rate assumption to 4% (prev. 3.5%) to reflect higher long-term revenue from Shopee and SeaMoney and raise our DCF target price to US$100 (prev. US$80), with an unchanged WACC of 7.6%. The company's triple-sided growth in SeaMoney, Shopee, and Garena shows potential to deliver returns for long-term growth.
Sea Ltd. – Raised Shopee Guidance
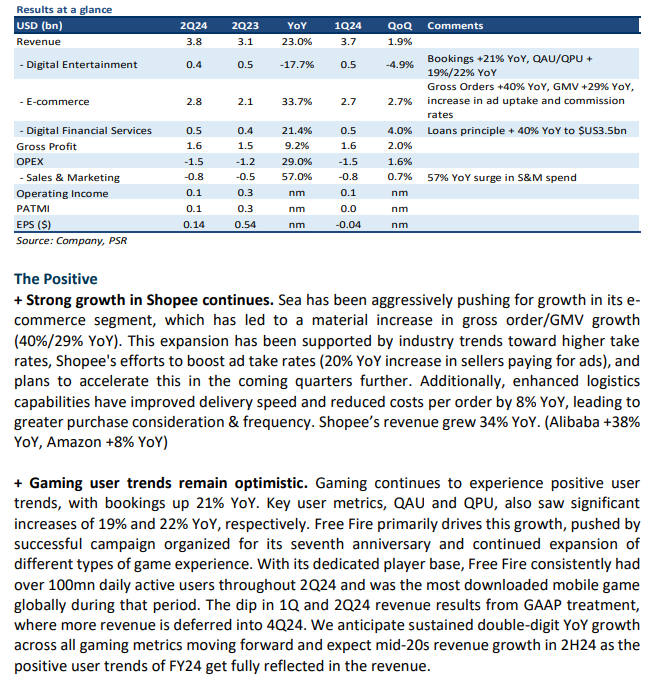
- 2Q24 revenue was slightly above expectations, with its 23% YoY growth primarily driven by strength in Shopee (34% YoY). PATMI missed on 57% YoY jump in S&M spending. 1H24 revenue/PATMI was at 49%/9% of our FY24 estimates. We expect PATMI to be backloaded into 2H24e as the ramp-up of Shopee continues as well as the late recognition of gaming revenue.
- For 3Q24e, Sea expects positive EBITDA for Shopee and has raised its FY24 GMV growth rate guidance from the high teens to the mid-20s. The company is benefiting from less competition. Shopee's emphasis on operational priorities, coupled with the industry trend of rising take rates, is anticipated to drive both top- and bottom-line growth.
- We maintain a NEUTRAL rating. We raised our FY24e revenue/PATMI by 1%/1% to account for higher e-commerce growth. Our DCF target price is raised to US$80 (prev. US$75), with an unchanged WACC/growth rate of 7.6%/3%. The company's triple-sided growth in SeaMoney, Shopee and Garena shows potential to deliver return for long-term growth. However, short-term growth remains challenged by competition as SE currently needs to maintain its high sales and marketing expenses in order to keep market share.
Get access to all the latest market news, reports, technical analysis
by signing up for a free account today!
Login
The full article is only available for premium content subscribers. To continue reading this article, please log in:
Not a Premium Content Subscriber yet? Sign up here!
- Home >
- Phillip Research Report