Q & M Dental Group Ltd – Waiting for inorganic growth
-
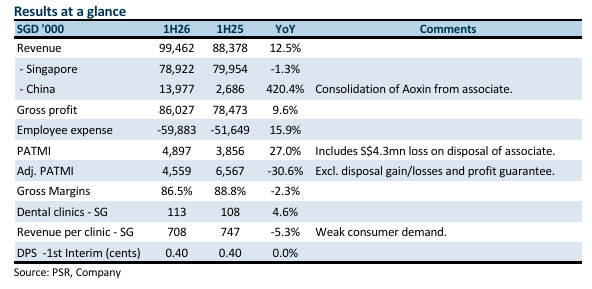
1H26 results were below expectations - revenue/adj. PATMI were 45%/25% of our FY26e forecast. Revenue in Singapore and China has been softer than expected. Higher finance costs pending acquisitions in Australia and Thailand are also weighing on earnings.
- Discretionary demand for dental services was weak in Singapore, especially in 1Q26, with recovery underway in 2Q26. China is facing pressure from price controls and weak demand due to the economic environment. Q&M Dental is pursuing an aggressive initiative to elevate the complexity of dental care and normalise revenue intensity.
- We lower our FY26e adj. earnings by 30% to S$12.7mn. We expect a seasonal recovery in 2H26 for Singapore together with improving revenue intensity. China will launch a new hospital in 2H26. We roll forward our valuations to FY27e to incorporate profit-guaranteed earnings from Australia and Thailand (at a 50% discount). We maintain our BUY with an unchanged target price of S$0.71.
The Positive
+ Acquisitions to deliver growth. There are S$146mn in pending acquisitions of dental clinics in
Australia (S$107mn) and Thailand (S$39mn), payable in cash (S$92mn) and shares (86.7mn @
S$0.70). The acquisition will boost EPS by at least 1 cent post-new-share issuance.
The Negative
- Weakness in revenue. Revenue grew 12.5% to S$99.5mn, but this includes the consolidation of
Aoxin Q&M Dental (from an associate) into China’s revenue. Aoxin recorded a 21% revenue
decline in 1H26.
Q & M Dental Group Ltd – One huge step in scale and growth
- Q & M Dental will acquire an Australian (100% stake) and Thailand (51%) dental group for around S$107mn and S$39mn, respectively. The purchase will be satisfied by a combined S$92mn cash and 86.7mn new shares (9.1% of existing shares). The shares are placed under a 15-year moratorium. The new shares are issued at a consideration price of S$0.70 per share.
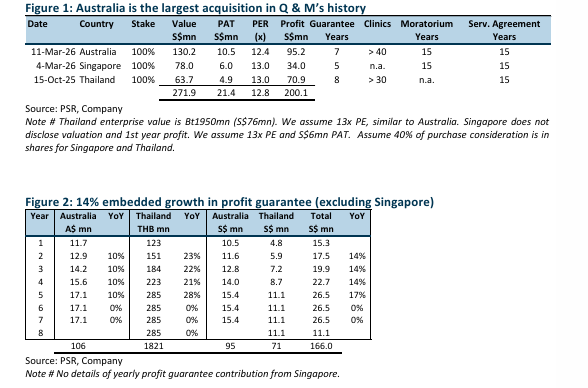
- The combined acquisition is valued at 11.4x PE ratio (Australia 10x, Thailand 16x). The total purchase of S$146mn is backed by a six-to eight-year profit guarantee totalling S$126mn. The implied earnings growth from the profit guarantee is around 13%, with Thailand the highest at 22% CAGR.
- We view the acquisition positively. Firstly, the acquisitions can increase our FY26e EPS by 1.04 cents (+54%) to 2.96 cents (excluding amortisation of intangibles). Valuation is pushed down to 18x PE. Secondly, it raises the growth trajectory of the company with the faster-growing geographies of Australia and Thailand, backed by profit guarantees. Thirdly, the 15-year share moratorium cum service agreement and profit guarantees ensure alignment of interests to build and grow this Asia Pacific franchise. There are also synergies through group procurement, training, and best practises. We maintain BUY with an unchanged target price of S$0.71.

Maintain BUY with unchanged TP of S$0.71
We peg valuations at 25x PE FY26e, in-line with Singapore healthcare sector. Aoxin Q & M Dental
is valued at market valuation. The acquisitions have not been incorporated into our target price.
Q & M Dental Group Ltd – Establishing an Asia-Pacific dental franchise
- Q & M Dental can double its earnings upon completion of the acquisition of more than 70 dental clinics in Australia, Singapore and Thailand. The estimated value of the acquisitions is S$272mn, backed by five to eight-year profit guarantees totalling S$200mn.
- The acquisition will be satisfied by cash and shares. Using the Australia acquisition template, shares issued will be 40% of the purchase consideration at the issue price of S$0.70. There will be a 15-year moratorium on the shares and a 15-year service agreement to align the vendors' interests. The acquisitions are pending financial and legal due diligence. The embedded earnings growth from profit guarantee is around 14% p.a. for next three years.
- We estimate the acquisition could boost FY26e EPS by 80% to 3.5 cents. Our fair value post acquisition (excluding amortisation of intangibles) is S$0.95. However, we apply a 50% discount on the earnings accretion from the pending completion of the acquisitions. Our target price is raised to S$0.71 (prev. S$0.545). We peg valuations at 25x PE FY26e, in-line with Singapore healthcare sector. Aoxin Q & M Dental is valued at market valuation. Q & M Dental is building a dental franchise across the Asia Pacific through acquisitions. We view the long tenure of the share moratorium, service agreement and profit guarantee as equivalent to a permanent partnership to grow and scale up a new franchise and platform.
Key Highlights
Three proposed acquisitions. After securing S$130mn 3.95% medium term notes (MTN) in July
2025, Q & M has announced a non-binding memorandum of understanding for three proposed
acquisitions (Figure 1). The acquisitions are pending financial, legal and operational due diligence.
The largest acquisition is Australia for A$144.5mn (~S$130mn) on 11 March, followed by
Singapore clinics on 4 March and Thailand on 15 October. We have assumed the valuations,
proportions, and pricing of shares to be issued for the Singapore and Thailand acquisition will be
similar to those in Australia. In the Australia acquisition, the Q & M shares issued to the vendor
are priced at S$0.70. Our assumed net profit contribution does not include an amortisation of
intangibles from the acquisition.
Operational benefits of the acquisition. The Australian dental target operates more than 40
clinics and 120 dentists. The aim is to aggressively grow the network towards 400 clinics over the
next five years, organically or through acquisition. Rolling up more Singapore clinics is part of Q &
M Dental’s objective to grow towards 300 dental clinics over the next five years. Q & M Dental's
standalone clinic count is currently 110. Thailand has more than 30 clinics focused on cosmetic or
aesthetic dentistry. There will be opportunities for revenue and cost synergies, together with best
practices in marketing, advanced dentistry and operations. The wider network of clinics is also an
avenue to roll out EM2AI solutions.
FY25 earnings review. FY25 revenue exceeded our expectations at 105% with the consolidation
of Aoxin Q & M. Net profit was below at 68% due to the S$2.4mn interest expense from the
S$130mn MTN and S$2mn one-off cost from professional fees and moving costs. Including these
additional costs, adjusted PATMI was 90% of our estimates. Staff costs were higher than expected
due to additional incentive payments. Progress in the rollout of EM2AI has also been slower, with
friction in changing dentists' current processes and behaviour. Rather than undertake the long
sales cycles, a licensing model could be adopted. Additional government subsidies for restorative
dental procedures (crowns, dentures, root canals) rolled out in October have contributed to a 3%
boost to Singapore's revenue in 2H25.
Maintain BUY with higher TP of S$0.71 (prev. S$0.545)
Q & M Dental Group Ltd – More growth after the reorg
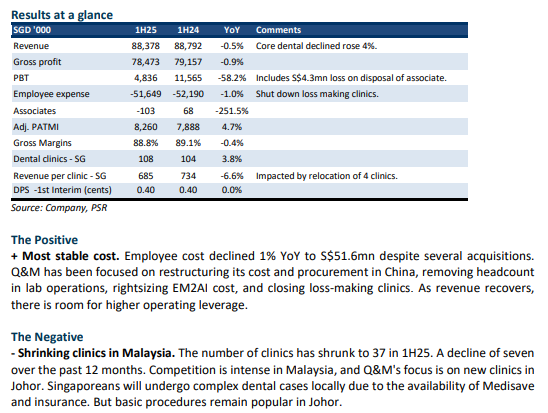
- 1H25 results were within expectations. Revenue and adj. PATMI were 47% and 40%, respectively, of our FY25e forecast. Adj. PATMI expanded 4.7% YoY to S$8.3mn. Q&M has been reorganising its clinics with closures of loss-making locations in Singapore and raising its stake in Aoxin China. 2H is seasonally stronger in China and Singapore.
- Q&M opened eight and closed four clinics in Singapore over the past 12 months. Q&M reported a S$4.3mn loss from consolidating Aoxin and EM2AI from an associate. Core dental revenue rose 4% YoY to S$87.4mn but offset by S$3mn from cessation of the lab business in Sep24.
- We maintain our FY25e earnings. Our target price is raised to S$0.545 (prev. S$0.40) as we peg our valuation to 25x PE from 18x, a 10% discount to the healthcare sector. We expect growth to improve in 2H25 onwards. The company is reorganising its cost structure in China, restructuring the clinic footprint in Singapore, and the S$130mn note raised could fuel earnings accretive acquisitions. 2H25 earnings will be supported by the jump in Singapore government subsidies in dental procedures and EM2AI rollout in 1,100 clinics.
Q & M Dental Group Ltd – Reorganising for future growth
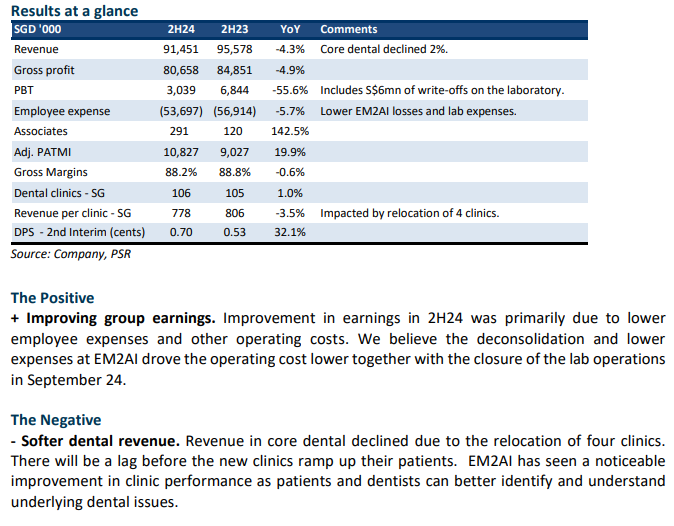
- FY24 profits exceeded our expectations: revenue and adj. PATMI were 97% and 113%, respectively, of our FY24e forecast. There was a turnaround in profitability of EM2AI and Aoxin and lower operating expenses. Adj. PATMI rose 20% YoY to S$10.8mn. The second interim dividend was raised 32% to 0.70 cents, and a 50mn share buyback was announced.
- 2H24 revenue declined 4% YoY to S$91.4mn due to the closure of the Acumen lab and slower core dental revenue. Core dental revenue fell due to the relocation of several older and less profitable clinics, with total clinics in Singapore rising by only one in FY24. Malaysia closed six clinics as the company focused on efficiency. Losses from EM2AI narrowed, and partial disposal on March 24 lowered employee costs. Associate Aoxin Q&M Dental has been turning around following more regulatory support for the large dental hospitals.
- We raised our earnings by 6% on the back of the turnaround in EM2AI, and Aoxin, and improving the profitability of existing clinics. Our BUY recommendation is maintained and target price raised to S$0.40 (prev. S$0.36) as we roll over our valuations. We value the company at 18x PE FY25e earnings, in line with industry peers. There is upside to our earnings if the company pursues a more aggressive acquisition strategy for growth and EM2AI finalises the agreement to sell its software to a network of approximately 1,000 clinics.
Q & M Dental Group Ltd – Growth drivers appearing
- Q & M is undergoing multiple cost initiatives to improve margins. Some of the cost-down efforts include sharing payment charges, consolidating suppliers, and recovering consumable charges.
- EM2AI has signed a memorandum of understanding (MOU) to integrate its dental AI solution into approximately 1,000 dental clinics in Thailand, the Philippines, Vietnam, and Indonesia. EM2AI has been in development for seven years, and this is a transformative milestone for Q & M. It represents a new source of recurrent earnings growth. There is an opportunity to become the essential clinical tool used in dental procedures as awareness and trust grow with the technology.
- We maintain our BUY recommendation and target price of S$0.36. There have been no changes in our forecast. We believe new growth opportunities are appearing for Q & M. Organically, the company aggressively looking to cost down its operations. Associate EM2AI AI is turning around with the commercialisation of its AI software. Inorganic opportunities could arise, especially in China, as the healthcare sector is facing major scrutiny and investigations.
Q & M Dental Group Ltd – Data-driven treatments can commence
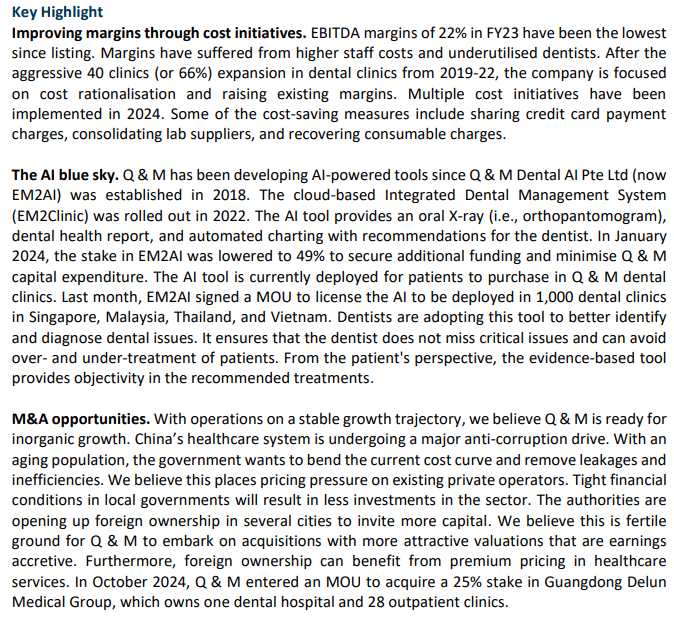
- 1H24 results were within expectations. Revenue and adj. PATMI were 48% and 47% respectively of our FY24e results. Adj. PATMI jumped 48% YoY to S$8mn. Interim dividend jumped 150% YoY to 0.4 cents.
- Core dental revenue rose 4% YoY from an increase in case complexity and revenue intensity aided by EM2AI AI model, despite the closure of 3 clinics over the past 12 months. Other cost saving initiatives were from professional and lab fees. Associate Aoxin Q&M Dental also registered a major turnaround in operations from government policies, reduced competition and cost control measures.
- We maintain our BUY recommendation and target price of S$0.36. No material change to our estimates. We value the company at 20x PE FY24e earnings, in line with industry peers. Listed associate, Aoxin Q & M Dental (S$0.053, Not Rated) is valued at market price with a 20% discount. After the aggressive expansion of 40 clinics from 2020-23, Q&M is focused on consolidating its clinics, turning around its associates and raising revenue intensity. Revenue growth is aided by EM2AI AI software that provides patients with unbiased and evidence-based treatment advice.
Q & M Dental Group Ltd – Data-driven treatments can commence
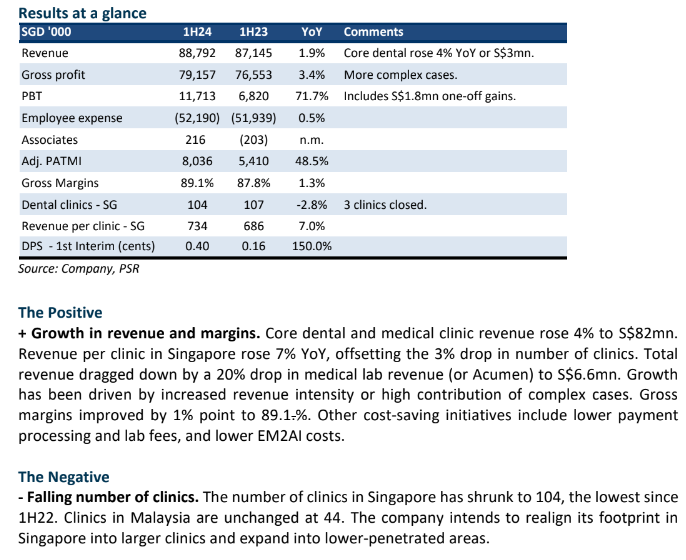
- 2023 adjusted PATMI exceeded our expectations at 121% of forecasts. Operating margins recovered from higher revenue per patient and more stable employee expenses. Associates also turned around from losses the prior year.
- Q&M is rationalising their network of clinics and closing poor performing clinics. Revenue intensity per patient is raised by utilising its EM2AI software. Data is drawn from dental scans, medical notes and records to ascertain the necessary level and timeliness of the treatments for patients. We view EM2AI as a critical tool for efficiency and differentiation.
- We upgraded from ACCUMULATE to BUY and raised our target price to S$0.36 (prev. S$0.34). We value the company at 20x PE FY24e earnings, in line with industry peers. Listed associate, Aoxin Q & M Dental (S$0.051, Not Rated) is valued at market price with a 20% discount. We expect Q&M to return to growth in FY24e. The key drivers are higher revenue per patient, more stable employee cost (as staffing levels for nurses normalise), deconsolidation of EM2AI R&D expenses and turnaround in associates.
The Positive
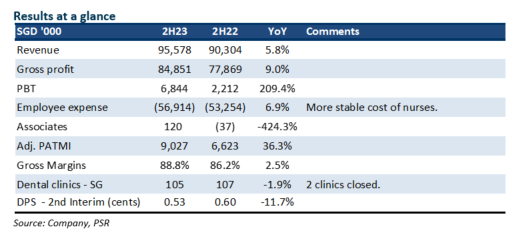
+ Recover in revenue and margins. 2H23 revenue growth is the fastest over the past two years. Despite fewer clinics, revenue expanded from higher revenue per patient. Using data driven treatment, Q&M can ascertain and provide a more intensive treatment for patients. Margins recovered from operating leverage and a stable number of staff or nurses.
The Negative
- Declining number of clinics. 2023 saw the first decline in the number of clinics in six years. Q&M closed two clinics in Singapore. The restructuring was to close loss-making clinics. Q&M is still looking to expand its clinics but for larger sites.
Q & M Dental Group Ltd – Still filling up the new clinics
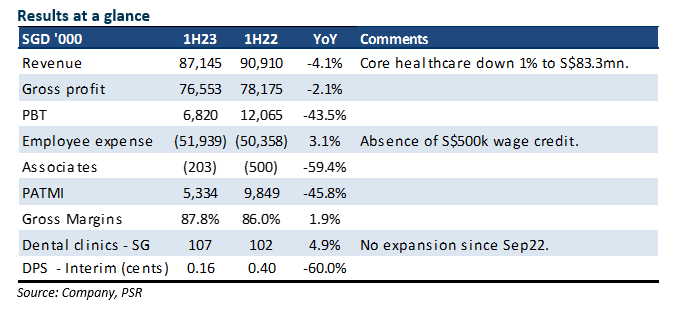
- 1H23 revenue was within expectations, but earnings were below. Revenue and adjusted PATMI were 47%/29% of our FY23e forecast. Post-expansion of clinics, the company is facing operating cost pressure such as staff cost, utilities, rent, finance and development expenditure of AI-guided clinical support software.
- Q&M has not opened any new clinics this year. The aim is to raise the utilisation of existing clinics with dentists and improve skill sets, especially for the loss-making clinics.
- We cut our FY23e PATMI by 34% to S$11.9mn. We lowered revenue by 4% and raised our operating expense assumptions. Our recommendation is downgraded from BUY to ACCUMULATE. The target price is lowered to S$0.34 (prev. S$0.47). We value the company at 25x PE FY23e earnings, in line with industry peers. Listed associate, Aoxin Q & M Dental (S$0.125, Not Rated), is valued at market price with a 20% discount. After building out a record 34 clinics or 30% more, Q&M needs to raise profitability by recruiting new dentists to fill its existing chain of clinics, installing new equipment and upgrading the poorer performing dentists.
The Positive
+ Growing the number of dentists. 1H23, the company has grown the number of dentists by 40 to 320 currently. This expansion in headcount will support revenue in 2H23. The company has stopped expanding into new clinics since September 2022. The aim is to grow the number of dentists or chairs in the existing chain.
The Negative
- Negative operating leverage. 1H23 operating expenses rose 3.7%, or S$2.1mn. Around 70% of the increase was higher employee expenses. Wages rose due to higher nurse wages and absence of a S$500k wage credit. Other increases were expansion-related fixed costs such as rental and depreciation. Q&M will suffer from negative operating leverage as fixed costs have elevated.
Q & M Dental Group Ltd – Pursuing operating leverage post-record expansion
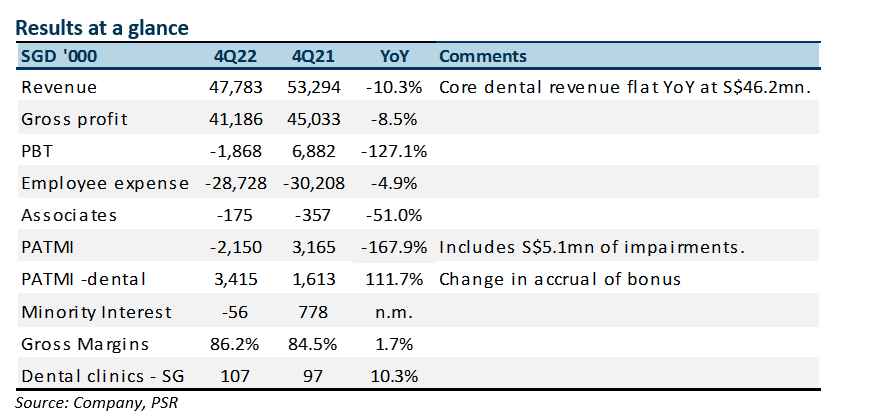
- Revenue met expectations but earnings were below. FY22 revenue and adjusted PATMI were 99%/90% of our forecast. The significant drop in COVID-19 related earnings and higher expenses in the development of AI-guided clinical support systems were the drag.
- Our adjusted PATMI excludes S$5.1mn of impairment of inventories (S$4.9mn) and plant and equipment (S$0.2mn) incurred in 4Q22.
- We are lowering our FY23e PATMI by 17% to S$17.9mn. After increasing the number of clinics by a record 34 (or 30%) over the past two years, the focus is to raise utilisation. Q&M continues to recruit dentists to fill its existing chain of clinics and upgrade the skills of dentists. Our BUY recommendation is maintained but target price lowered to S$0.47 (prev. S$0.52). We value the company at 25x PE FY22 earnings, in line with industry peers. Listed associate, Aoxin Q & M Dental (S$0.115, Not Rated), is valued at market price with a 20% discount.
The Positive
+ Number of clinics expanded. In FY22, Q&M expanded the number of clinics by 16 (or 12%). Most of the new clinics were in Singapore, with 10 new clinics. Profitability from core dental operations tripled to S$3.4mn. This was due to a change in the accrual of staff bonuses from a lumpy 4Q to proportionate provisioning per quarter.
The Negative
- Revenue per clinic declined. 4Q22 revenue per clinic declined by 12% YoY to S$382k. New clinics have not reached maturity, as nurse shortages and the re-opening of borders have dampened visits. Nevertheless, total revenue from core dental was flat YoY at S$46.2mn.
Outlook
The priority in FY23 is to raise the utilisation of the existing clinics. After the aggressive expansion over the past two years (34 clinics), the company will look to raise visits and revenue intensity per patient. Recruitment into the existing network of clinics will boost the availability of dentists. Improving the skill sets of the current dentists is another initiative to increase revenue intensity. Q & M is also pursuing an AI-guided dental software that creates an ethical standard cum procedures that supports dentists.
Get access to all the latest market news, reports, technical analysis
by signing up for a free account today!
Login
The full article is only available for premium content subscribers. To continue reading this article, please log in:
Not a Premium Content Subscriber yet? Sign up here!
- Home >
- Phillip Research Report