Netflix Inc. – Viewing time a big concern
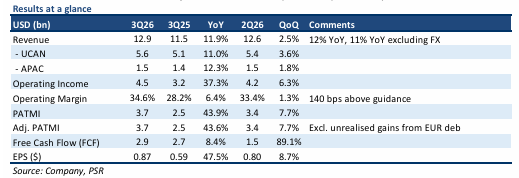
- 3Q26 revenue was in line with expectations, while adj. PATMI slightly outperformed due to the timing of operating expenses. Revenue rose 12% YoY, driven by membership growth, higher pricing, and increased ad revenue. 9M26 revenue/adj. PATMI was at 74% and 75% of our FY26e estimates.
- Weakening engagement is now a main concern for NFLX. 4Q26e revenue growth is guided at 11.5% YoY, implying four consecutive quarters of decelerating growth. Meanwhile, FY26e advertising revenue guidance was lowered by 10%, from US$3bn to US$2.7bn, due to a slower-than-expected rollout.
- Maintain BUY with a lower target price of US$100 (prev. US$110) as we lower FY26e revenue by 1% and terminal growth from 3.5% to 3%, respectively, due to slower growth. We still like NFLX's strong pricing power, advertising potential and industry-leading profitability, but weakening engagement and decelerating growth weigh on the near term. With shares under pressure this year, valuation is much more attractive now, with FY26 forward adj. P/E at 21.4x compared to previously 33.3x.
The Positives
+ Pricing power still on display. NFLX continues to demonstrate strong pricing power. It
implemented subscription price increases across the UK and Germany in Sep and Oct, with
limited impact on subscriber churn; this is consistent with the trend we saw following its US
price increase in Mar. This highlights the platform’s strong customer stickiness. With NFLX still
offering one of the lowest costs per viewing hour among major streaming platforms in the
US, we believe there remains room for further price increases.
+ Advertising remains a key growth driver. Despite a 10% downward revision in FY26
advertising revenue guidance from US$3bn to US$2.7bn due to rollout delays, this still
represents robust growth of approximately 80% YoY. We remain positive on NFLX's
advertising potential, supported by improving monetisation capabilities. The planned rollout
of ad-supported tiers into 15 additional countries in FY27 should further broaden its
addressable market. We believe advertising provides NFLX with an additional monetisation
lever, particularly in price-sensitive markets, supporting revenue growth and diversification
beyond subscription fees.
Netflix Inc. – Softer guidance, but we see no signs of slowing engagement
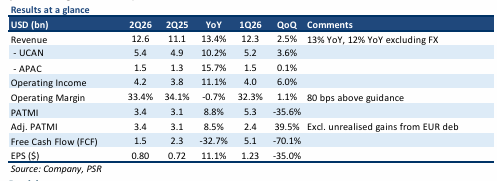
- 2Q26 revenue was in line with expectations while adj. PATMI underperformed due to the timing of title launches, causing content amortization to be front-loaded into 1H26. Revenue rose 13% YoY, driven by membership growth, higher pricing, and increased ad revenue. 1H26 revenue/adj. PATMI was at 49% and 44% of our FY26e estimates.
-
View hours +2% YoY in 1H26 vs. +1.5% YoY in 1H25, despite the competitive impact of the Winter Olympics and the World Cup this year. Ad remains on track to double in FY26. Management has projected 12% YoY growth for 3Q26e.
-
We upgrade our recommendation from ACCUMULATE to BUY due to recent stock price movement, with an unchanged target price of US$110. Our estimates remain unchanged, with a WACC of 11.6% and a terminal growth rate of 3.5%. We still see a healthy membership trend, resilient pricing power, expanding advertising monetisation, and industry-leading profitability, with no signs of slowing engagement. As advertising monetisation continues to scale, we believe earnings growth will reaccelerate, creating an attractive entry point for long-term investors (Forward FY26 P/E ratio at 18.8x vs 5-year average of 36.25x).
The Positives
+ Pricing power remains a key strength. NFLX’s Mar 2026 price increase across key markets,
including the U.S., Mexico and Spain (+8% to 12.5% across major plans), has been absorbed
with no indication of elevated churn. Its multi-tier pricing strategy, including a lower-priced
ad-supported plan, gives consumers the flexibility to trade down rather than churn,
supporting long-term ARM growth. We continue to view the stickiness of NFLX's content
offering as its key competitive strength.
+ No signs of slowing engagement. Despite tougher comparisons and competition from the
Winter Olympics and FIFA World Cup, NFLX’s engagement remained healthy. Viewing hours
reached 97bn in 1H26 (+2% YoY, vs 1.5% YoY in 1H25). Membership growth, together with
pricing and advertising, supported 13% YoY revenue growth, with double-digit revenue
growth across all regions. Advertising also continues to scale, on track to double its revenue
in FY26. Meanwhile, NFLX plans to increase investment in films and series by 10% YoY this
year, reinforcing confidence in its long-term content pipeline. Taken together, these
indicators point to sustained consumer engagement and continued monetisation strength.
The Negative
- Slightly softer 3Q26 outlook amid tougher content comparisons. NFLX guided for 3Q26
revenue growth of 12% YoY, a slight deceleration from recent quarters, likely due to a less
compelling 2H26 content slate relative to 2H25, which benefited from blockbuster releases
such as Stranger Things, Wednesday, and Squid Game that drove exceptionally strong
engagement. In addition, management did not announce any new initiatives, such as a FAST
(free ad-supported TV) platform. The lack of new catalysts contributed to a more muted near
term outlook.
Netflix Inc. – Execution remains strong, but growth is moderating
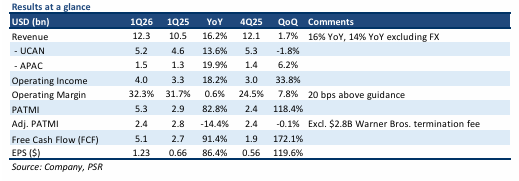
- Both 1Q26 revenue was in line with expectations, slightly exceeding the company’s own guidance for 1Q26. 1Q26 PATMI exceeded expectations, driven by $2.8B termination fee related to the Warner Bros. transaction. 1Q26 revenue/adj. PATMI was at 25% and 21% of our FY26e estimates.
- Revenue rose + 16% YoY, driven by membership growth, higher pricing, and increased ad revenue (expected 2x in FY26e). Management has projected 13% YoY growth for 2Q26e.
- Maintain ACCUMULATE with a higher target price of US$110 (prev. US$100). We raise FY26e revenue and PATMI by 1% respectively to account for the price increase. There is no change in terminal growth or WACC assumptions. NFLX is still building on its leadership position in the VoD streaming industry through a strong subscription base, quality content and strong pricing power. Its ARPU is ~2x more than its nearest competitor, Disney.
The Positives
+ Strong pricing power on display. NFLX continues to demonstrate robust pricing power, with
recent price increases (8–13% across plans) well absorbed, and early indicators pointing to
stable retention and churn. NFLX delivers one of the lowest costs per viewing hour among
SVOD platforms (we estimate NFLX: $0.31/hour, DIS: $0.35/hour, Hulu: $0.40/hour),
supporting further pricing headroom. The company continues to layer monetisation levers
across its large user base, including differentiated plans, improved discovery, and expansion
into new formats (live events, podcasts, gaming). We view sustained pricing execution,
supported by strong engagement and value perception, as a key driver of long-term earnings
growth.
+ Ad on track to double in FY26e. NFLX’s advertising business continues to scale, supported
by improved ad-tech capabilities and a rapidly expanding advertiser base. The company now
works with >4,000 advertisers (+70% YoY). Management reiterated its expectation for
US$3bn in ad revenue in FY26e (2x YoY). The ad-supported tier remains a key entry point,
accounting for >60% of sign-ups in ad markets, while delivering engagement levels
comparable to ad-free plans. In parallel, NFLX continues to invest in its proprietary ad-tech
stack, enabling better targeting, improved measurement, and new ad formats, which are
attracting a broader pool of advertisers and driving monetisation efficiency.
Netflix Inc. – Content, ads, and scale drive the next leg of growth
- Both 4Q25 revenue and PATMI were in line with expectations, exceeding the company’s own guidance for both 4Q25 and FY25. FY25 revenue/PATMI was at 100%/99% of our FY25e estimates.
- Revenue rose + 17% YoY, driven by membership growth (+8% YoY), raised prices, improving plan mix pricing adjustments, as well as the scaling of ad revenue (2.5x YoY). Management has projected 15% YoY growth for 1Q26.
- Upgrade to ACCUMULATE from SELL with a higher target price of US$100 (prev. US$95) as we roll over our valuations to FY26e. There is no change to our FY26e forecast, terminal growth, or WACC assumptions. NFLX continues to demonstrate clear leadership in the VOD space and strong pricing power. Volatility is expected due to the Warner Bros. deal, but we believe NFLX is well-positioned structurally and financially for long-term growth.


Netflix Inc.-Margin pressure raises concern
• 3Q25 revenue was in line with expectations, while PATMI missed on US$619mn dispute with Brazilian tax authorities. Excluding this effect, 9M25 revenue/PATMI was at 73%/83%, in line with our FY25e estimates.
• Membership growth, pricing adjustments, and increased ad revenue drove revenue growth of 17% YoY. Management has projected 17% YoY growth for 4Q25.
• Our valuation remains unchanged with a DCF target price of US$950. No change in our FY25e forecast. We maintain our SELL recommendation. Our terminal growth and WACC assumptions remain unchanged. NFLX continues to demonstrate clear leadership in the VOD space and strong pricing power. However, we maintain a cautious view given its elevated valuation and ongoing margin pressures.
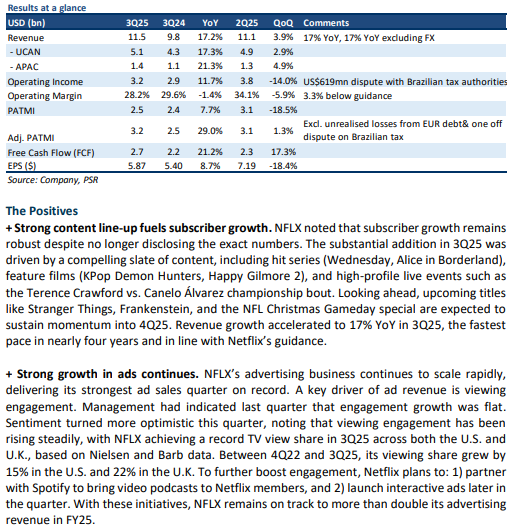
Netflix Inc.- Tough to surpass high expectations
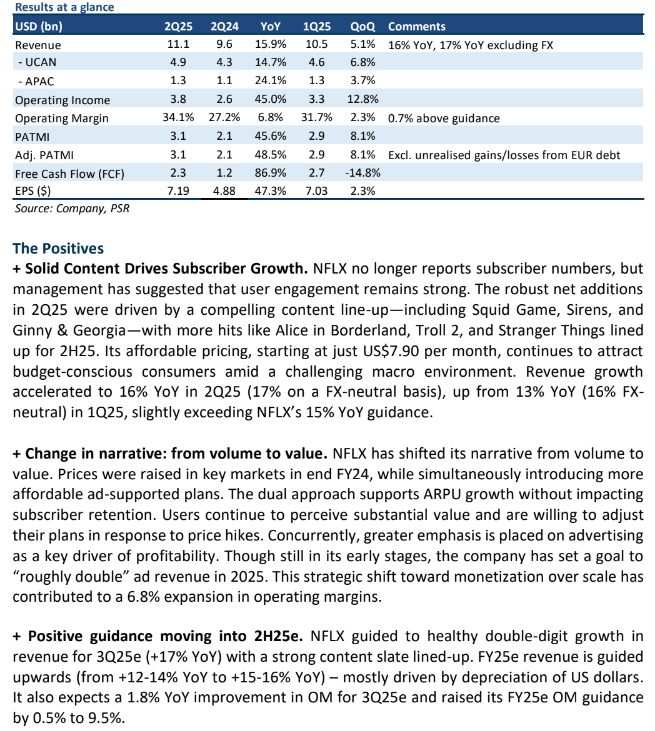
- 2Q25 revenue/PATMI met our estimates. 1H25 revenue/PATMI was at 48%/54% of our FY25e forecasts.
- Revenue growth of 17% YoY was driven by higher subscription revenue (due to a strong content slate and flexible pricing of subscription plans). Management has projected 17% YoY growth for 3Q25. FY25e revenue growth is advised upwards but mainly due to US dollar depreciation.
- Our valuation remains unchanged with a DCF target price of US$950. No change in our FY25e forecast. We downgrade our recommendation from NEUTRAL to SELL, due to the recent share price rally. Our terminal growth and WACC assumptions remain unchanged. NFLX showcases leadership within the VODS and strong pricing power. We remain cautious given the stretched valuation.
Netflix Inc.- Ability to withstand recession
- 1Q25 revenue met our estimates while PATMI outperformed due to better monetization and favourable timing of expenses. 1Q25 revenue/PATMI was at 24%/26% of our FY25e forecasts.
- Revenue growth of 13% YoY was driven by higher subscription and recent price adjustment (+16% for standard plans & +14% for ad plans). This growth is partially attributed to NFLX's continued focus on its ad-supported business. Management has projected strong growth for 2Q25, anticipating minimal impact from the broader economic slowdown.
- We raise our FY25e revenue/PATMI by 1% each to account for gradual price increases, thriving ads business, and increasing operating leverage. We raised terminal growth from 3.0% to 3.5% due to its long-term monetization potential through advertising. We raise our DCF target price to US$950 (prev. US$870), and upgrade from REDUCE to NEUTRAL. Our WACC assumptions remain unchanged. A strong content pipeline and the expansion of its ad-supported tier position will enable NFLX to navigate potential economic slowdowns. However, trading at 37x FY25e P/E—well above the industry average of 17x—NFLX’s current valuation suggests limited near-term upside.


Netflix Inc. – Stretched valuations
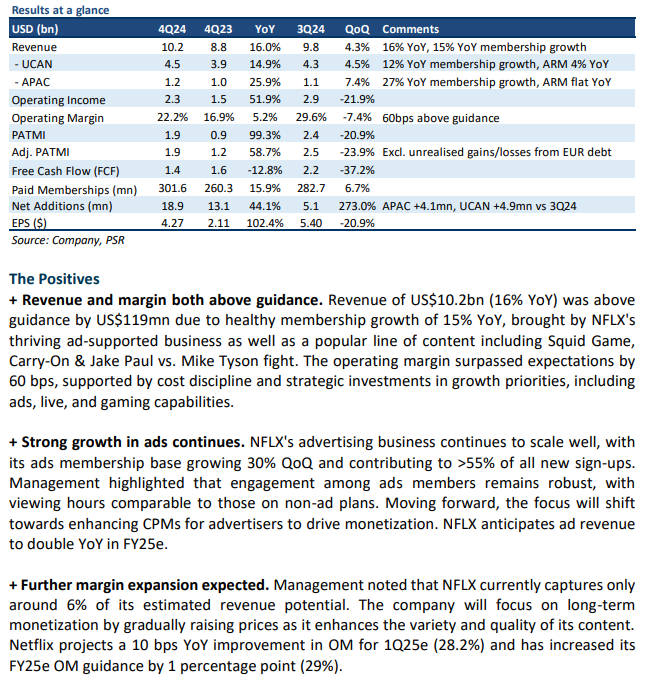
- 4Q24 revenue/PATMI were in line with our estimates. FY24 revenue/PATMI was at 101%/101% of our FY24e forecasts.
- Revenue growth of 16% YoY was driven by a 19mn new membership additions (+15% YoY), the largest quarterly increase in company history (followed by 13mn in 4Q23 & 5mn in 3Q24). This growth is partially attributed to NFLX's thriving ad-supported business (30% QoQ vs 35% QoQ in 3Q24). NFLX raised prices by 16% for standard plans and 14% for ad plans.
- We raise our FY25e revenue by 4% due to robust membership additions and thriving ads business. We raise PATMI by 6% to account for the higher margins due to increasing operating leverage, cost discipline, and continued gradual price increases. We raise our DCF target price to US$870 (prev. US$695), but downgrade to REDUCE from NEUTRAL to account for recent share price strength. Our WACC/growth rate assumptions remain unchanged. NFLX continues to solidify its dominance in the VoD streaming market, expanding its user base while increasing average revenue per member (ARM) through a combination of premium content and strategic pricing.
Netflix Inc – Solid results, but valuations look full
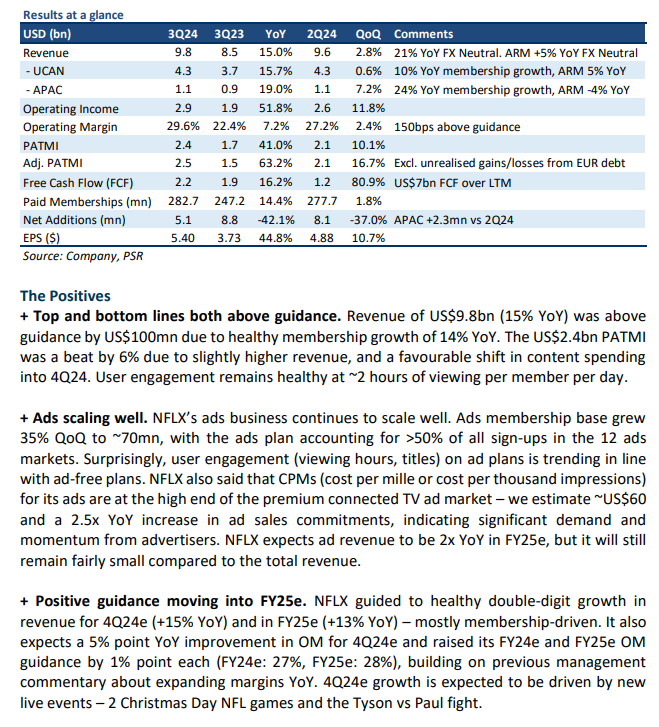
- 3Q24 revenue was slightly above our estimates, while PATMI was higher due to better topline growth and favourable timing of content spend. 9M24 revenue/PATMI was at 74%/84% of our FY24e forecasts.
- Revenue continues to grow in healthy double-digits YoY, while 41% PATMI growth beat estimates by 6% on higher revenue and better operating leverage.
- We raise our FY24e PATMI by 6% on higher margins due to price increases, increasing operating leverage, and cost discipline. We raise our DCF target price to US$695 (prev. US$675), but downgrade to NEUTRAL from ACCUMULATE to account for recent share price strength. Our FY24e revenue and WACC/growth rate assumptions remain unchanged. NFLX is still building on its leadership position in the VoD streaming industry, growing both users and ARM through quality content and effective pricing. Its ARM is ~2x more than its nearest competitor, Disney.
Netflix Inc. – All according to plan
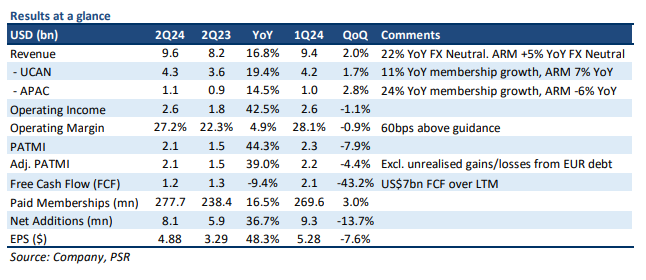
- 2Q24 revenue aligned with our estimates, while PATMI was above due to higher operating leverage. 1H24 revenue/PATMI was at 49%/59% of our FY24e forecast.
- Better-than-expected 8.1mn net additions (or +37% YoY) continue to support growth, partly due to NFLX’s thriving ads business (ad tier 34% QoQ). Revenue growth accelerated to 17% YoY.
- We raise our FY24e PATMI by 6% on higher margins due to better-than-expected membership growth, increasing operating leverage, and cost discipline. We maintain ACCUMULATE with a raised DCF target price of US$675 (prev. US$640). Our FY24e revenue assumptions remain unchanged. We continue to expect NFLX to drive user growth through its wide range of affordable subscription plans. We believe ARM growth will begin to accelerate due to increasing advertising revenue because of its growing scale. Our WACC/growth rate assumptions remain the same at 12.2%/3%, respectively.
The Positives
+ Better-than-expected net additions are driving an acceleration in revenue growth. NFLX added 8.1mn net membership additions, driven by beats in all markets (particularly in India). The net additions outperformance was attributed to 1) a strong content slate, 2) some positive impact from paid sharing, and 3) a lower price point appealing to more cost-conscious consumers. Revenue growth in 2Q24 accelerated to 17% YoY (22% FX neutral) vs 15% YoY (18% FX neutral) in 1Q24, modestly above NFLX’s guidance of 16% YoY.
+ Ads business continues to scale meaningfully. NFLX continues to scale its ads business rapidly, increasing its ad tier membership base 34% QoQ to ~52mn (~19% of NFLX’s total membership) in 2Q24. Ad tiers now account for >45% of all new signups in markets where NFLX has rolled out its Ad tiers. NFLX continues to also grow its Ad inventory to support the business. It still does not expect advertising to be a primary driver of revenue for FY24e or FY25e due to 1) near-term challenges in monetisation – NFLX lacks adequate features for advertisers, and 2) an outsized proportion of existing subscription revenue. We view advertising as the next big margin driver for NFLX (behind price increases).
+ Positive forward guidance for FY24e. Given the better-than-expected membership additions so far this year, NFLX again revised upwards its FY24e targets for revenue growth (13%-15% to 14%-15%) and operating margin (from 25% to 26%). Its 26% OM target would be a YoY improvement of 540bps, indicating significant operating leverage due to its larger scale and cost discipline. NFLX expects consistent YoY margin expansion moving forward. We increase our FY24e operating income and PATMI estimates by 6% each as a result.
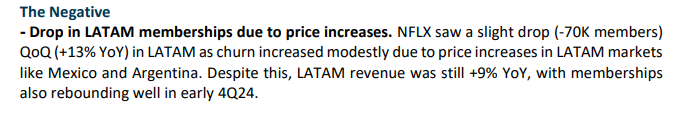
The Negative
- Nil
Get access to all the latest market news, reports, technical analysis
by signing up for a free account today!
Login
The full article is only available for premium content subscribers. To continue reading this article, please log in:
Not a Premium Content Subscriber yet? Sign up here!
- Home >
- Phillip Research Report