Microsoft Corp – Efficiency gains led Azure acceleration
- 4Q26 revenue met our expectations, while PATMI exceeded. Revenue and PATMI were at 101% and 107% of FY26e forecasts, respectively. Revenue rose 18% YoY, led by Cloud Azure revenue growth (+43% YoY). PATMI beat our expectations on a net gain from the Anthropic investment.
-
We forecast FY27e revenue growth of 17.2%. Azure is expected to grow 45% in 1Q27e, driven by OpenAI backlog conversion, enterprise AI adoption, and capacity expansion, with demand continuing to outpace supply. Productivity growth should remain strong, supported by Copilot, M365 E5 and E7 monetisation, and usage-based billing, while the PC segment is likely to remain weak amid higher pricing and elevated inventory.
-
We maintain our ACCUMULATE recommendation, with a higher DCF-based target price of US$515 (prev. US$485), driven by better-than-expected revenue and earnings, as well as lower than our forecasted CAPEX in FY26. We roll our valuation forward, while our FY27e forecasts are unchanged. Our WACC and g remain unchanged. We see strong long-term Cloud and AI earnings visibility, backed by a US$678bn commercial RPO, accelerating cloud AI-driven growth and monetisation of SKUs Productivity offerings.

Microsoft Corp – Another quarter, another CAPEX bump
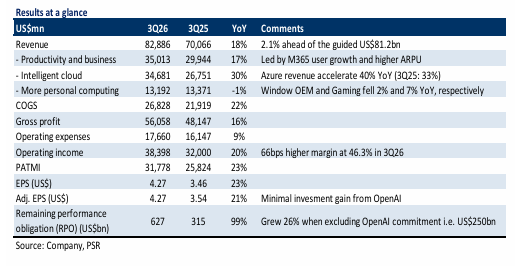
- 3Q26 revenue met our expectations, while PATMI exceeded. 9M26e revenue and PATMI at 76%/81% of FY26e forecasts, respectively. Revenue rose 18% YoY, led by Cloud Azure revenue growth (+40% YoY).
- We expect FY26e group revenue to grow 16.7% with Azure growing 29%, supported by a faster ramp-up as additional data centre capacity comes online. The AI business e.g. AI tools exceeded a US$37bn annual run-rate, up 123% YoY. Revenue recognition from OpenAI-related backlog is expected to materialise meaningfully from 2027. Productivity and Business Processes is expected to grow 15%, supported by the July 2026 price increase and new E7 Copilot package. M365 and Copilot upgrades should sustain usage and offset competition, with commercial paid seats above 450mn in 2Q26 (+6% YoY).
- We downgrade our recommendation to ACCUMULATE from BUY, with a lower TP of US$485 (prev. US$540), due to higher CAPEX by US$40bn to US$190bn because of higher component costs, investments in AI infrastructure and growing AI product usage. We raise our revenue forecasts by 3% and 5%, and PATMI by 9% and 17% for FY26e and FY27e, respectively. We expect a step-up in growth as new data centre capacity comes online. Our WACC and terminal growth rate remain unchanged.
The Positives
+ Productivity demand stayed strong. The productivity and business processes segment
was up 17% to US$35bn, driven by 19% YoY growth in Microsoft 365 Commercial Cloud
revenue. ARPU expansion was supported by the uptake of higher-tier offerings such as
Microsoft 365 Copilot and E5 enterprise subscriptions. Paid Copilot seats have surpassed
20mn (vs. 16mn in 2Q26) at 5% of total paid M365 commercial seats that grew 6% YoY, led
by SMBs and frontline worker adoption. The segment operating margin grew 18% YoY
(3Q25: 10%) despite continued AI investment and higher Copilot advertising spend.
+ Azure cloud climbed higher. Intelligent Cloud revenue up 30% YoY to US$34.6bn and
Azure up 40% YoY (3Q25: 33%), supported by Fairwater data centre capacity in Wisconsin
coming online six weeks early. The AI business e.g. AI tools exceeded a US$37bn annual run
rate, up 123% YoY. Microsoft cloud revenue (cloud-delivered services) rose 29% to
US$54.5bn, driven by strong demand across Azure and first-party AI services. We expect
Azure to remain slightly margin-dilutive near term due to AI buildout, but to turn accretive
as capacity is absorbed and monetisation improves. Segment margin eased to 39.6% (3Q25:
41.5%) on higher AI spend and Copilot usage.
Microsoft Corp – Prioritising Azure amid supply shortages
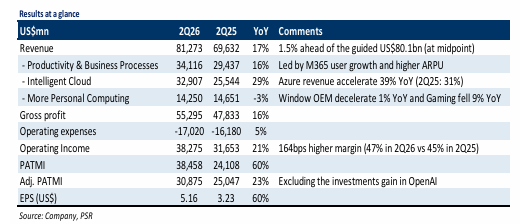
- 2Q26 revenue met our expectations with revenue/adj. PATMI was at 50%/51% of our FY26e forecasts. Revenue grew 17% YoY driven by 40% YoY growth in Azure cloud revenue. Adj. PATMI rose 23% YoY to US$30.9bn, driven by higher operating leverage.
- For 3Q26e, Microsoft expects revenue to rise 16% YoY to US$81.2bn, driven by continued strong growth across commercial businesses. Azure is projected to grow 37%, as the company continues to prioritise supply amid demand exceeding capacity. Commercial RPO rose 110% YoY to US$625bn and are expected to be recognised over the next 2.5 years.
- We upgrade our recommendation to BUY from ACCUMULATE with an unchanged DCF target price of US$540, due to recent price performance. There are no changes to our forecast. The company is currently valued at a blended forward PE of 23.9x, below the -1 standard deviation of 27.2x.
The Positives
+ Strong cloud services performance drives results. Azure accelerated 40% YoY, driving
Intelligent Cloud growth of 29% to US$32.9bn. Monetization was supported by efficiency
improvements across Microsoft’s flexible server fleet, which allowed additional computing
capacity to be allocated to Azure. Management noted strong demand across workloads,
with demand still exceeding supply.
+ Productivity suite demand remains robust. Productivity and Business Processes rose 16%
to US$34.1bn (42% of group revenue). M365 Commercial Cloud revenue increased 17% YoY,
supported by higher adoption and ARPU growth from M365 Copilot and E5. Paid M365
commercial seats grew 6% YoY, primarily in small and medium businesses and frontline
workers.
+ Commercial RPO soared. Commercial remaining performance obligations rose 110% YoY
to US$625bn and are expected to be recognised over the next 2.5 years. 45% of it was from
OpenAI’s US$250bn multi-year Azure commitment, and US$30bn from Anthropic. The
remaining 55% grew 28% YoY, reflecting broad-based demand across the portfolio and a
healthy and diversified orderbook.
The Negative
- Nil
Microsoft Corp – US$35bn CAPEX exceeds expectations
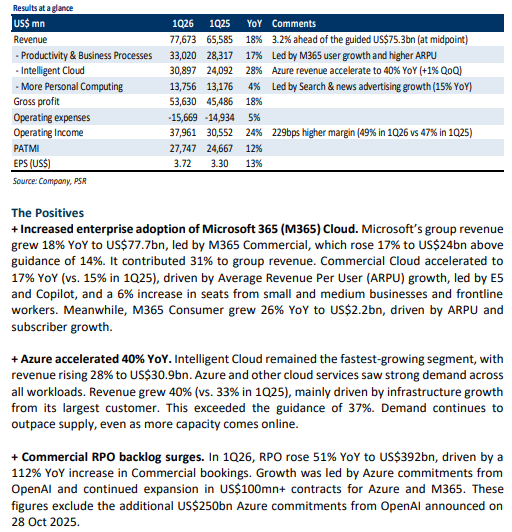
- 1Q26 revenue/PATMI met our expectations at 24%/26% of our FY26e forecasts. Total revenue grew 18% YoY, driven by cloud services, with Azure revenue up 40% YoY.
- The Microsoft–OpenAI new agreement reinforces Microsoft’s Cloud and AI leadership, supported by IP rights through 2032 and a US$250bn Azure commitment. RPO backlog surged 51% YoY to US$392bn, fuelled by 112% YoY growth in Commercial bookings.
- We maintain ACCUMULATE recommendation at a lower target price of US$540 (from US$550). For FY26e, we raised PPE purchases paid in cash from US$80bn to US$83bn following CAPEX exceeding expectations. Net income remains slightly lower due to elevated OPEX from higher CAPEX, but is partially offset by higher M365 margins and workforce reductions.
Microsoft Corp – Cloud services accelerate
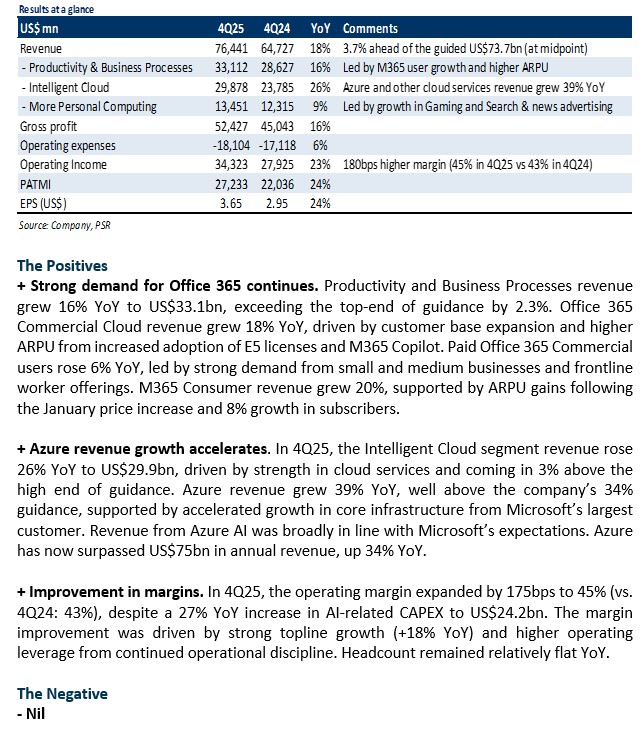
• FY25 revenue and PATMI met our expectations at 101% of our forecasts. 4Q25 revenue
rose 18% YoY, driven by strength in the Cloud services business (Azure +39% YoY).
PATMI increased by 24% YoY to US$27.2bn due to higher operating leverage.
• For 1Q26e, Microsoft expects revenue to grow by 15% YoY to US$75.3bn, fuelled by a
37% YoY rise in Azure revenue and a 13% YoY increase in Office 365 commercial cloud
revenue. Microsoft's 1Q26e implied operating margin is ~46.6%, flat YoY despite
increased CAPEX for AI capacity expansion.
• We maintain our ACCUMULATE recommendation and raise our DCF-based target price
to US$550 (from US$480), reflecting a higher terminal growth rate of 4.7% (previously
4.5%) and WACC of 7.2%. We have rolled over to a new year. Microsoft continues to
anticipate higher earnings from Azure (+37% YoY), despite facing supply constraints.
However, we see upside potential given the backlog of US$368bn (1.3x FY25 revenue).
Microsoft Corp – Strong earnings despite uncertainty
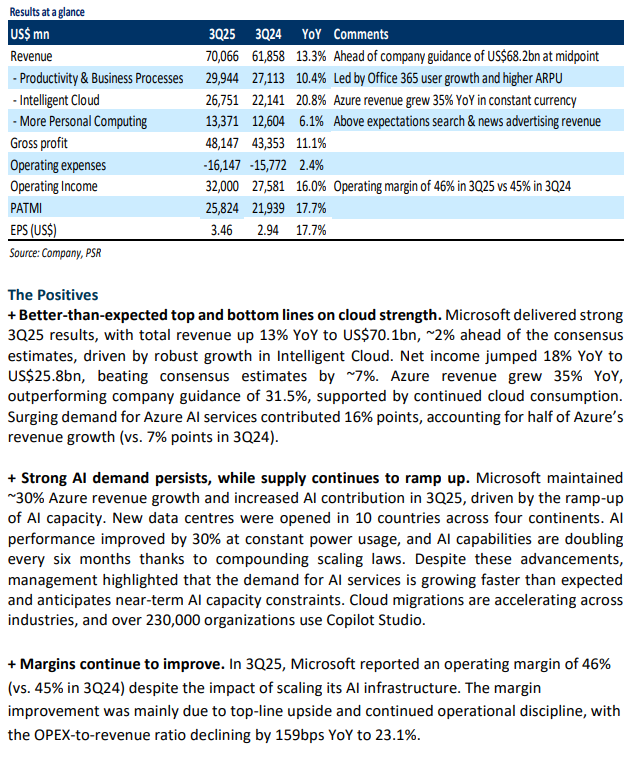
- 3Q25 revenue/PATMI met our expectations at 74%/74% of our FY25e forecasts. Total revenue grew 13% YoY, driven by strong demand for Azure and cloud services.
- For 4Q25e, Microsoft expects total revenue to grow by 14% YoY to US$73.7bn, driven by 34.5% YoY rise in Azure revenue and 14% YoY increase in Office 365 commercial cloud revenue.
- We downgrade to ACCUMULATE from BUY due to recent price performance. Our DCF target price of US$480 (WACC 7.2%, g 4.5%) and FY25e estimates remain unchanged. We believe Microsoft is well-positioned to benefit from the rising demand for large AI models, boosting Azure’s appeal and driving incremental revenue through Copilot AI tools. Microsoft remains less impacted by tariffs, as its strong growth is driven by cloud-based offerings and supported by a broad base of enterprise customers.
Microsoft Corp – Cloud and AI-powered growth
-
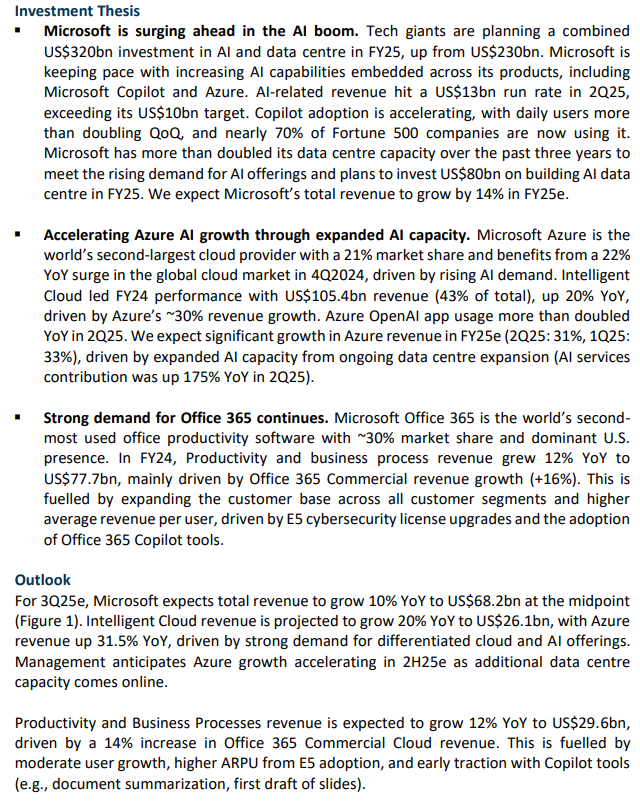
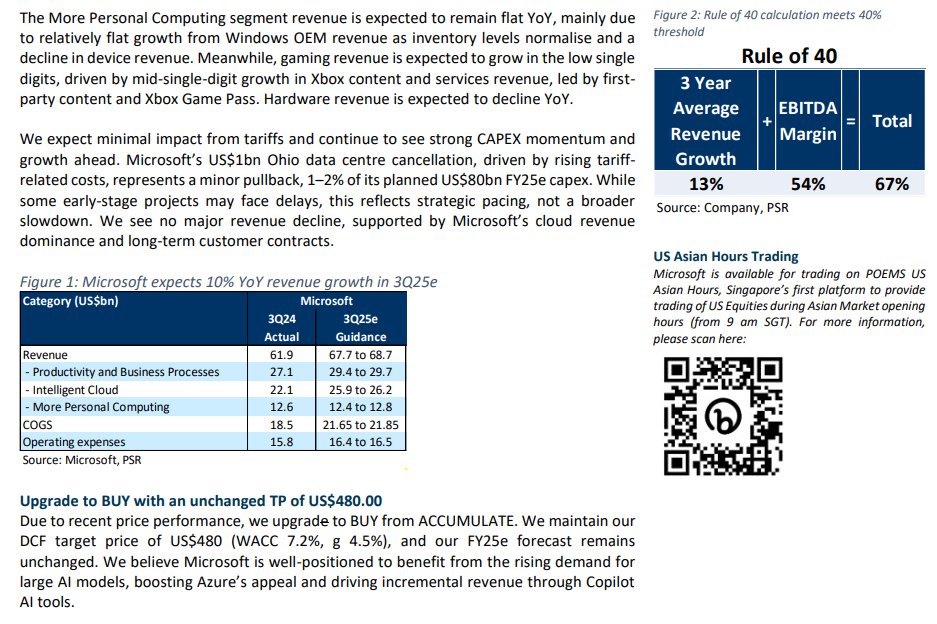
Microsoft’s Intelligent Cloud segment leads performance, with Azure AI growth set to accelerate as new data centre capacity comes online in 2H25e.
-
Strong demand for Office 365 continues, driven by higher ARPU and increasing adoption of E5 upgrades and Copilot tools.
-
We upgrade to BUY from ACCUMULATE recommendation due to recent price performance. We maintain our DCF target price of US$480 (WACC 7.2%, g 4.5%), and our FY25e forecast remains unchanged. We believe Microsoft is well-positioned to benefit from the rising demand for large AI models, boosting Azure’s appeal and driving incremental revenue through Copilot AI tools.
Microsoft Corp – Azure remains a key growth engine
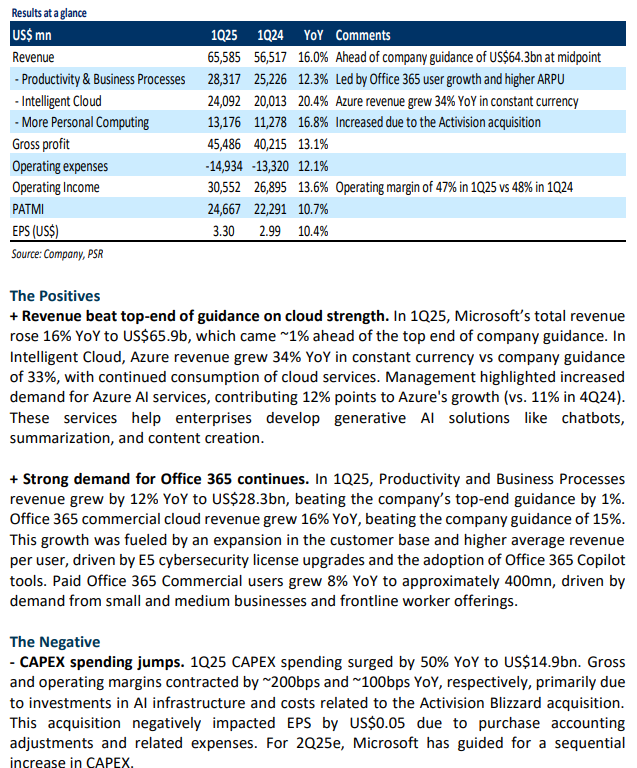
- 1Q25 revenue/PATMI was in line with expectations at 24% of our FY25e forecasts. Total revenue grew 16% YoY, driven by strong demand for its cloud and AI-enabled services.
- For 2Q25e, Microsoft expects revenue to grow by 11% YoY to US$68.6bn, fueled by a 32% YoY rise in Azure revenue and a 14% YoY increase in Office 365 commercial cloud revenue. Microsoft's 2Q25e implied operating margin is ~44%, flat YoY despite increased CAPEX for AI capacity expansion.
- We maintain our ACCUMULATE recommendation with an unchanged DCF target price of US$480 (WACC 7.2%, g 4.5%). Our FY25e forecast remains unchanged. We believe Microsoft is well-positioned to benefit from the rising demand for large AI models, boosting Azure’s appeal and driving incremental revenue through Copilot AI tools.
Microsoft Corp – Continued strength in cloud services
- FY24 revenue/PATMI met our expectations at 100% of our forecasts. 4Q24 revenue growth of 15% YoY was supported by strength in its cloud services and gaming segments, led by Azure and Xbox.
- For 1Q25e, Microsoft expects total revenue to grow by 14% YoY to US$64.3bn fueled by a 29% YoY rise in Azure revenue and a 14% YoY increase in Office 365 Commercial revenue. Microsoft’s implied operating margin for 1Q25e is ~45%, down from 48% in 1Q24 due to rising CAPEX on capacity expansion.
- We maintain our ACCUMULATE recommendation but raise our DCF target price to US$480.00 (prev. US$465.00), with an unchanged WACC of 7.2% and terminal growth rate of 4.5%. We nudge lower our FY25e revenue estimates by 1% due to moderating client spend, while increasing our PATMI by 2% to account for lower operating expenses. We roll over an additional year of valuations but increased our FY25e CAPEX by about 30%. We believe Microsoft is well-positioned to benefit from the rising demand for large AI models, boosting Azure’s appeal and driving incremental


Microsoft Corp – Azure strength fuels revenue growth
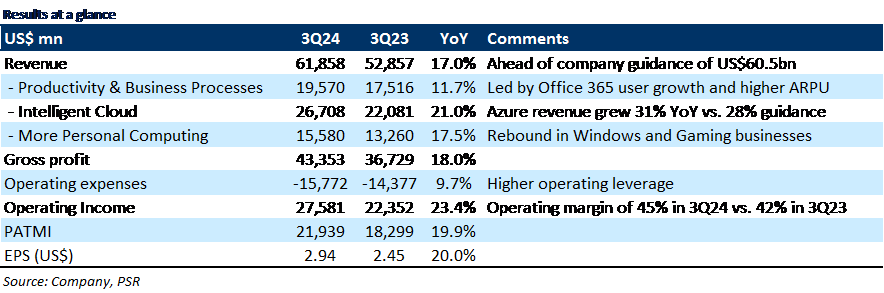
- 9M24 revenue/PATMI was in line with expectations at 74%/77% of our FY24e forecasts. 3Q24 revenue growth of 17% YoY was supported by strength in cloud computing business Azure. PATMI rose by 20% YoY to US$21.9bn due to higher operating leverage.
- For 4Q24e, Microsoft expects total revenue to grow by 14% YoY to US$64bn fueled by Azure revenue growth of 31% YoY and Office 365 Commercial revenue growth of 14% YoY. Microsoft’s implied operating margin for 4Q24e is ~42%.
- We maintain ACCUMULATE recommendation but raise our DCF target price to US$465.00 (prev. US$450.00), with an unchanged WACC of 7.2% and terminal growth rate of 4.5%. Our FY24e revenue estimates remain unchanged, while we increased our PATMI by 2% to account for lower expenses. We believe that the growing demand for large AI models could help attract customers to Microsoft’s Azure platform for storage and computing solutions.
The Positives
+ Azure revenue growth accelerates. In 3Q24, Intelligent Cloud segment revenue grew 21% YoY to US$26.7bn led by strength in cloud services. Azure revenue grew 31% YoY, beating the company’s guidance of 28% YoY growth. The significant growth was primarily driven by an increase in the size and duration of the deals as customers migrated workloads (e.g., SAP/Oracle) from on-premises to the cloud. Management noted accelerating demand for its Azure AI services, which contributed 7% points to Azure growth (vs. 6% in 2Q24). Azure AI services help enterprises create their own generative AI solutions, including the development of chatbots, summarization, and writing documents.
+ Windows and Gaming continued to rebound. In 3Q24, More Personal Computing segment revenue grew 18% YoY to US$15.6bn, 3% above the top end of company guidance. Notably, Windows OEM revenue grew by 11% YoY, beating the company’s guidance that it would be relatively flat. The growth was mainly driven by a recovery in the PC market and a shift to developed markets. Meanwhile, Gaming segment revenue grew by 51% YoY to US$5.5bn as the integration of Activision Blizzard titles like Call of Duty into Xbox Gamepass drove higher player engagement.
+ Improvement in margins. In 3Q24, the operating margin expanded by 300bps YoY to 45% despite elevated AI-related CAPEX, beating the company’s guidance of 43%. The margin improvement was mainly due to top-line upside, higher operating leverage from prudent headcount control (down 1% YoY), and lower sales-related costs. CAPEX jumped 66% YoY to US$11bn due to cloud and AI infrastructure build-out.
The Negatives
- Nil
Get access to all the latest market news, reports, technical analysis
by signing up for a free account today!
Login
The full article is only available for premium content subscribers. To continue reading this article, please log in:
Not a Premium Content Subscriber yet? Sign up here!
- Home >
- Phillip Research Report