Lendlease Global Commercial REIT – Retail strength continues, AEI upside next
- 2H26/FY26 DPU met 50%/98% of our expectations (up 2.7% YoY). 2H26 GRI/NPI rose 6.8%/6.6% YoY to S$110.0mn/S$78.7mn, forming 57%/55% of our FY26e forecast. This was supported by i) full-half contribution following the acquisition of PLQ mall, ii) strong rental reversion of 11.7% and portfolio occupancy of 98.5% across the Singapore retail portfolio.
- Gearing has improved from 42.6% to 38.9% from i) partial equity funding of PLQ acquisition (funded via S$280.0mn private placement and S$196.6mn preferential offering), which expanded equity while limiting incremental leverage, ii) repaying debt using proceeds from JEM Office sale (sold at S$462mn). Adjusted gearing was also reduced to 44.3% from 50.8%, as outstanding perpetual securities declined from S$319.5mn to S$240.6mn, with S$200mn of 4.20% perps redeemed and replaced by S$120mn of new 4.28% perps issued.
- We maintain our BUY recommendation and increase our target price to S$0.77 (prev. S$0.73) as we roll forward our forecasts. We have incorporated full-year PLQ mall contribution from FY27e onwards, with DPU estimate unchanged for FY27e. LREIT is trading at a FY27e P/NAV of 0.84x, with a dividend yield of c. 6.89%. Future performance depends on i) the PLQ AEI completing on schedule (16,000 sq ft across Level 1 & 2, targeting completion by Dec 26), (ii) successful divestment and capital recycling of Sky Complex Building 3 divestment proceeds, (iii) Singapore retail reversions continuing at a strong pace.

The positives
+ Strong operational performance. Retail rental reversion stood at 11.7% (FY25: 10.2%), with
committed occupancy at 98.5% (down 1% YoY). Tenant sales grew 24.0% YoY (up 4.0% ex-PLQ
Mall), and cumulative visitation rose 16.4% YoY (up 5.2% ex-PLQ Mall), reflecting resilient
suburban retail demand. The F&B, sports, and jewelry/watches tenants had strong retail
performance, while gifts and ancillary-use tenants lagged. Management is reconfiguring c. 16,000
sq ft at PLQ Mall, Levels 1 and 2 (former H&M, Uniqlo, and Foot Locker space), into 3-5 new
tenancies, including two anchor F&B concepts in advanced discussions, targeting high-teens rental
reversion on completion by Dec 26.
+ Strong capital management. S$120mn of the S$200mn perp securities maturing in Jun26
were refinanced at 4.28% (from 4.2%), with the remaining S$80mn funded through cheaper
bank debt. The cost of debt of 2.75% (down 71 bps YoY) also came in lower than the 2.9%
guidance provided by management. Weighted average debt maturity is extended to 2.8 years
(from 2.6 years), with no substantial refinancing till FY28 (EUR223.0mn of term loans and
S$100mn of loans are due). Management expects potential interest savings from future
refinancing, as the euro-denominated debt hedges (expiring at the end of FY28) were locked
in during 2023 when base rates were elevated. However, we have not modelled any savings
given rate uncertainty.
Lendlease Global Commercial REIT – Singapore retail portfolio fundamentals sound
- No financials were provided for 3Q26. Retail rental reversion for YTD renewed leases increased 12.2%. Portfolio occupancy stood at 95.3% (+0.4 ppts QoQ). Milan office Buildings 1 and 2 had CPI-linked rental uplift of 1.5% from Apr26. We expect retail rental reversion to remain in the low-double-digit range into 4Q26.
- PLQ mall enhancement works on c. 16,000 sqft across levels 1 and 2 have been progressing, with level 1 space already pre-leased. Level 2 leasing is in progress. Income contribution from the reconfigured spaces is expected to begin in 2H27, with peak downtime anticipated in Oct27/Nov27. The PLQ Mall acquisition is expected to deliver 2% DPU accretion.
- We maintain our BUY recommendation. There are no changes to our forecast. LREIT is trading at a FY26e P/NAV of 0.70x, with a dividend yield of c. 5.86%. We see the strengthening capital structure and PLQ Mall reconfiguration as key drivers, partially offset by the drag from Milan Building 3.

The positives
+ Retail rental reversion strong. Singapore retail rental reversion was +12.2%. Jem and
313@somerset delivered mid- to high-single-digit reversions, while PLQ Mall is expected to
achieve higher reversions than legacy assets. Reversion was driven by resilient Chinese F&B
operators, gold and jewellery, sporting goods, and athleisure tenants. We expect high-single
to low-double-digit reversion to persist into 4Q26.
+ PLQ mall integration progressing well. With 100% of PLQ mall acquired as of Mar26, asset
enhancement initiatives have been progressing on c. 16,000 sq ft across levels 1 and 2. Level
1 is pre-leased, whereas level 2 leasing is in progress. The reconfigured spaces are expected
to generate income starting in 2H27. PLQ Mall loans have also been refinanced, securing c.
S$2mn in annual all-in debt cost savings. The conversion of PLQ Mall to a limited liability
partnership structure is targeted for completion by end Jun26. The PLQ Mall acquisition is
expected to deliver 2% DPU accretion.
+ Stronger capital structure. ICR improved to 1.8× from 1.5× in 3Q25, supported by i)
divestment of Jem office in Nov25, ii) refinancing of PLQ Mall loans, iii) replacement of the
S$200mn perpetual securities with cheaper funding. The weighted average cost of debt fell
to 2.89% p.a. from c. 3.5% a year ago. The S$8.9mn disposal gain from the Jem office sale is
being held in reserve for potential future AEI initiatives.
Lendlease Global Commercial REIT – PLQ Mall strengthens suburban retail portfolio
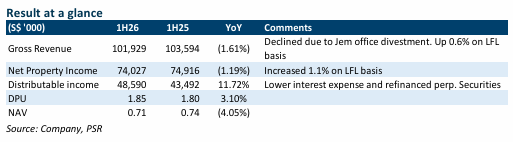
- 1H26 DPU of 1.85 cents rose 3.1% YoY, forming 51% of our full-year FY26e forecast. The resilient performance of the retail portfolio (rental reversion up 10.4% YoY) and strong capital management (gearing down 430 bps to 38.4%) resulted in a 11.7% YoY increase in distributable income to S$48.5mn.
- Retail rental reversion was 10.4% (c.7% ex-PLQ Mall). PLQ Mall had a strong reversion contribution given that the asset has been under-rented since its Covid-period opening, when occupancy was prioritised over rent optimisation. Portfolio tenant retention was 64.5% by NLA, weighed by the Cathay Cineplexes exit (ex-Cathay: 76.8% retention).
- We maintain BUY with a higher DDM-based TP of S$0.73 (prev. S$0.70), taking into account PLQ Mall’s contribution and associated c. S$234.5mn private placement. Upside catalysts include a potential accretive divestment of Milan Building 3 and a larger-than-expected distribution from the S$8.9mn Jem office divestment gain yet to be deployed. Rental reversion is expected to trend at double digits for the remaining of FY26. LREIT currently trades at a FY26e yield of 5.9% and is at a c. 28% discount to NAV.
The positives
+ PLQ Mall acquisition strengthens retail portfolio. The 70% acquisition of PLQ Mall from
ADIA for S$885mn (a 2.1% discount to appraised value) is 2.5% DPU accretive. PLQ Mall has
over 200 tenants with a committed occupancy of 99.7% and a WALE of 2.3 years. The
acquisition lifts the suburban retail portfolio to 63% of total portfolio value at S$3.9bn (from
55% at S$3.3bn). The retail portfolio’s rental reversion was 10.4% (c.7% ex-PLQ Mall), with
occupancy at 99.5%. PLQ Mall has been under-rented since its Covid period opening, and
ongoing reconfiguration works are expected to drive rental uplift from single digits to the high
teens per cent range.
+ Disciplined capital management. Gross debt has fallen S$500mn to c.S$1.2bn, compressing
gearing 430 bps to 38.4% and expanding ICR from 1.6x to 1.8x. This was driven by the
refinancing of S$200mn of perpetual securities with S$120mn of new issuance at a lower
coupon (down to 4.75% from 5.25% p.a.), and by cheaper loan funding, which compressed
the cost of debt by 19bps to 2.90%. 72% of borrowings are fixed-rate hedged. Near-term
refinancing risk is minimal, with FY26 debt maturity of S$100mn well covered by S$701.2mn
of available facilities.
+ Room for sustained rental reversion. Jem’s acquisition in FY2022 compressed portfolio
occupancy cost by over 600 bps to 23.7%, as seen from Figure 1. This is likely due to suburban
malls typically having lower occupancy costs than prime retail destinations such as
313@somerset. The addition of PLQ Mall could lead to a similar effect, particularly given that
the mall opened during Covid when occupancy was prioritised over high rental rates. The
potentially lower occupancy cost for the portfolio provides greater headroom for rental
upside without straining tenants.
Lendlease Global Commercial REIT – Long waited JEM divestment at valuation
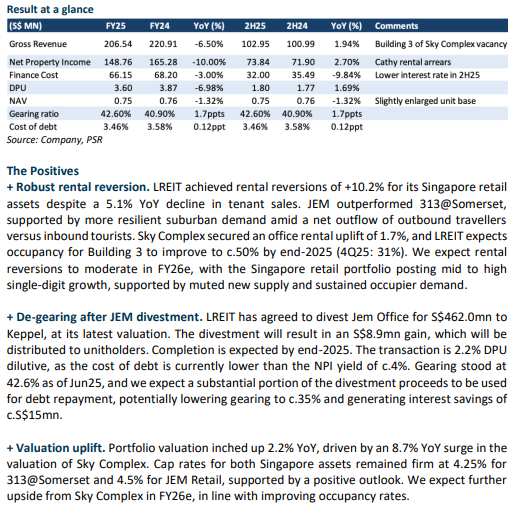
- FY25 DPU declined by 6.9% YoY to 3.6 cents, in line with our estimates and meeting 100% of our FY25e forecast. The drop was mainly due to a 10% YoY decrease in NPI, driven by rental arrears from Cathay, and a higher Euribor rate. However, 2H25 DPU rose 1.8% YoY to 1.80 cents, supported by a 9.8% YoY decline in financing costs.
- LREIT successfully executed the long-awaited divestment of JEM Office at a valuation of S$462.0mn, with completion expected by the end of 2025. We expect c.S$400mn to be used for debt repayment, which will bring gearing down to c.36.7% (-5.9ppts). JEM Office contributes 12.5% of FY25 GRI, and the income vacuum from the divestment is expected to be partially offset by higher occupancy at Sky Complex Building 3 and capital top-up.
-
We maintain our BUY recommendation with a higher DDM-TP of S$0.70 (prev: S$0.69) as we roll our forecasts forward. FY26–27e DPU forecasts have been revised down by 10% to 3.61/4.07 cents, while COE has been lowered by 1.4ppts to 7% to reflect the impact of de-gearing post-JEM divestment. LREIT is trading at an FY26e dividend yield of 6.3%, P/NAV of 0.78x.
Lendlease Global Commercial REIT – Minimal downtime from departure of Cathay
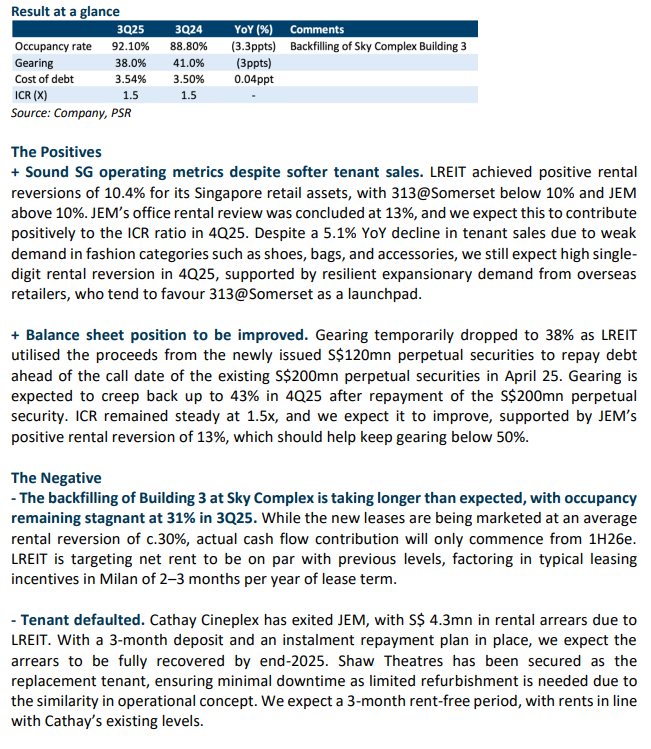
· While no financials were provided for 3Q25, LREIT reported sound operating metrics for its Singapore assets, with retail achieving 10.4% and the rental review for JEM concluded at 13%. We expect rental reversion to remain at high single-digit for 4Q25.
· Portfolio occupancy dipped slightly by 0.2ppt QoQ to 97.1%, with Building 3 of Sky Complex seeing stagnancy in backfilling its space. LREIT successfully replaced Cathay Cineplex with Shaw Theatres at a comparable rental rate and implemented an instalment plan to address the S$4.3mn in rental arrears.
· We maintain our BUY recommendation with a lower DDM-TP of S$0.69 (prev: S$0.74). We revised our FY25e/26e DPU forecasts down by 2%/0% to 3.60/4.05 cents and COE by 0.4ppt to 8.4%, reflecting slower-than-expected backfilling at Building 3 of Sky Complex and a 3-month income vacuum due to Cathay Cineplex’s delinquency. LREIT is trading at an FY25e dividend yield of 7% and P/NAV of 0.69x.
Lendlease Global Commercial REIT – Low-teens rental reversion expected for JEM office
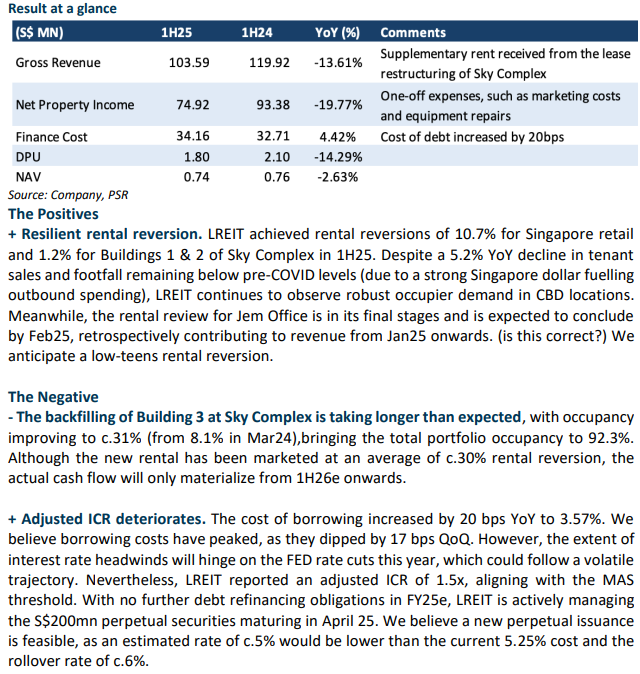
· Gross revenue and NPI declined by 13.6% and 19.8% YoY, respectively, accounting for 46% and 45% of our FY25e estimates. This was due to the absence of pre-termination fee paid by Sky Italia and the longer-than-expected backfilling of Building 3 Sky Complex. NPI margin was impacted by a one-off expense of c.£1mn for equipment repairs, which has yet to be capitalized, along with higher marketing expenses.
· DPU plunged by 14.3% YoY to 1.8 cents, which was in line with our estimates and formed 48% of our FY25e forecast. Higher financing costs dragged down DPU since the cost of borrowing inched up by 20bps YoY.
· Retail rental reversion remained resilient in FY25e, achieving 10.7% for retail and 1.2% for office, despite tenant sales falling 5.2% YoY. We have revised our FY25e/26e DPU forecasts lower by 2%/2% to 3.70/4.05 cents, reflecting the slower-than-expected backfilling of Building 3 at Sky Complex. We maintain our BUY recommendation with a lower DDM-TP of S$0.74 (prev: S$0.76). While FY25e earnings are expected to benefit from low-teens rental reversion of both Singapore retail and Jem Office, DPU growth may be constrained by uncertainty surrounding the interest rate cut trajectory.
Lendlease Global Commercial REIT – Higher for longer interest rate
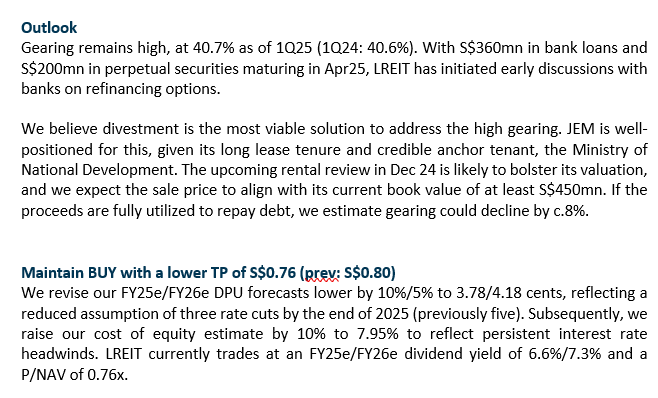
- Although interest rates have peaked, we expect that the all-in cost of borrowing for LREIT will hover at the current high level of c.3.7% in FY25e. This is due to the high proportion of loans tied to fixed rates, which will delay the benefit of any future interest rate cuts for LREITs.
- Sky Complex Milan is taking longer than expected to backfill the vacant building, dragging portfolio occupancy down to 75%. We expect the building to be fully tenanted by the end of the calendar year 2025, resulting in an income vacuum for FY25e.
- We reiterate our BUY recommendation with a revised DDM-TP of S$0.76 (prev: S$0.80). FY25e earnings are expected to be supported by low-teens retail rental reversion, with an upside from the JEM Office rental review, which we estimate at >5%. DPU will likely face another year of erosion due to higher-for-longer interest rates, as the rate cut trajectory under Trump’s presidency remains uncertain. We lower our FY25e/FY26e DPU forecasts by 10%/5% to 3.78/4.18 cents, reflecting a reduced expectation of three rate cuts by the end of 2025 (prev: five). LREIT is trading at an FY25e/FY26e yield of 6.6%/7.3% and a P/NAV of 0.76x.
Lendlease Global Commercial REIT – Cost of borrowing peaks
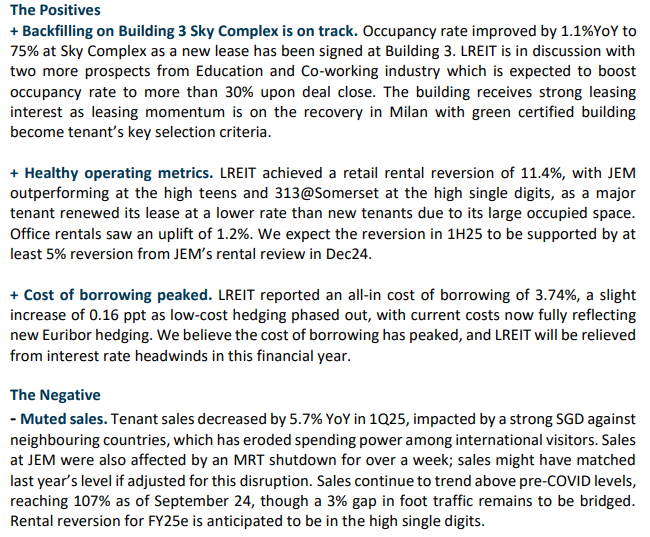
- No financials was provided in 1Q25. LREIT achieved resilient retail rental reversion of 11.4% (4Q24: +12%) and office rental saw 1.2% uplift (4Q24: +1.2%). The portfolio occupancy rate stands at 89.5%, with Sky Complex at 75% occupancy.
- Tenant sales declined by 5.7% YoY due to train disruption and strong SGD, trending at 107% of pre-COVID levels, with a 4% QoQ decrease. We believe rental reversion would moderate from the high level in FY24 and 12.1% of GRI is due for renewal in FY2025.
- We reiterate our BUY recommendation with an unchanged DDM-TP of S$0.80. FY25e rental reversion is expected to be supported by marked-to-market rental upon successful backfilling on Building 3 Sky Complex and rental review of JEM office. DPU catalysts include the peak in borrowing costs and the potential divestment of JEM to deleverage, which could lead to lower financing costs. LREIT is trading at an FY25e/26e dividend yield of 7.31% / 7.60% and a P/NAV value of 0.76x.
Lendlease Global Commercial REIT – DPU is bottoming out
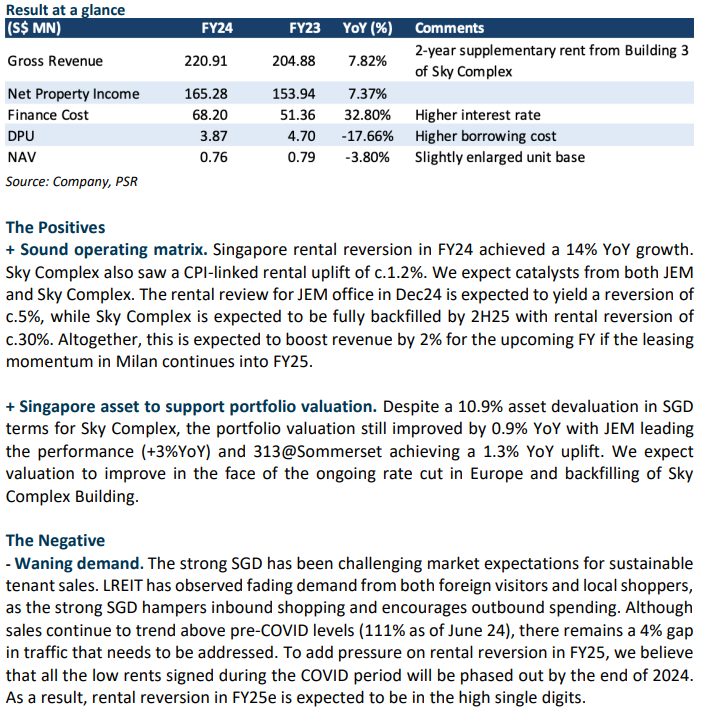
- Gross revenue for FY24 surged by 7.8% YoY to S$220.9mn, in line with our estimates which includes the €10mn pre-termination fee recognized from SKY Complex Building 3.
- NPI and DPU missed our expectations by 6% due to elevated property operating expenses (which increased by 9.2% YoY), and rising financing costs (+32.8% YoY). Although the one-time €10mn pre-termination fee has been recognized, the distributable income will be adjusted to reflect amortization over a 2-year period. As a result, NPI and DPU stood at S$165.3mn (+7.4% YoY) and 3.87 cents (-17.7% YoY), respectively.
- We reiterate our BUY recommendation with a revised DDM-TP of S$0.80 (prev: S$0.83), as retail demand growth is expected to decelerate with the post-COVID recovery tailwinds waning. Moderated rental reversion and tenant sales have been factored in for the upcoming year due to the current macroeconomic backdrop. Nevertheless, we expect revenue to increase by c.3% in FY25e, driven by the c.30% rental reversion upon backfilling of Building 3 and a rental review of the JEM office. We have reduced our FY25e/26e DPU forecasts by 10% to 4.03/4.30 cents on the back of the elevating financing cost. LREIT is currently trading at an FY25e dividend yield of 6.9% and a P/NAV of 0.76x.
Lendlease Global Commercial REIT – Rental upside to come from Sky Complex Milan
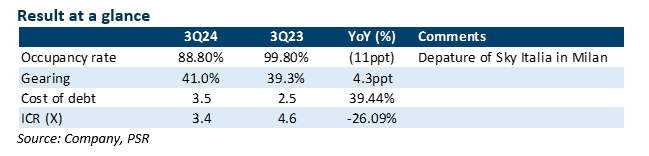
- No financials were provided for 3Q24. Portfolio committed occupancy plunged 11% YoY to 88.8% in the face of the departure of the anchor tenant of Sky Complex, which returned one-third of the space. However, on a QoQ basis, it improved by 0.9% due to the backfilling of Sky Complex by 8.1%.
- Rental reversion for both retail and office remained resilient, achieving 15.3% and 1.5%, respectively. We expect rental reversion to maintain at the current level for FY24e and earnings to be supported by the long-lease office tenant, which accounted for c.22% of the total income.
- We reiterate our BUY recommendation with an unchanged DDM-TP of S$0.83 and FY24e-25e DPU forecast of 4.16-4.59 Singapore cents. We expect potential upside from the high rental reversion upon the successful backfilling of Building 3 Sky Complex Milan and the completion of Live Nation in Grange Road.
The Positives
+ Robust retail rental reversion of 15.3% with 313 achieving c.20% and Jem delivering resilient performance of c.10%. Rental reversion for offices saw a slight cooling down, landing at 1.5% in 3Q24. However, stable support comes from tenants with long lease periods, contributing to c.22% of the total gross rental income. We expect rental reversion for the whole year FY24e to be c.15% (FY23: 4.8%).
+ Potential rental uplift from Jem and Sky Complex. We anticipate rental upside from Building 3 Sky Complex Milan, driven by healthy office demand in the surrounding area and lower-than-average rental rates previously signed by Sky Italia. In 3Q24, LREIT secured 8.1% of the net lettable area (NLA) leases through internal sourcing. LREIT expects backfilling to be completed by 50% by the end of 2024, with the rental reversion of c. 30-40% to match current market rates. Jem is also reviewing its rental at the end of 2024, and the current market rental is c.20% higher than the previous rent signed five years ago. We expect rental escalation to be in the high-teens, resulting in an improvement in revenue by c.2% upon successful negotiation.
The Negative
- NIL
Get access to all the latest market news, reports, technical analysis
by signing up for a free account today!
Login
The full article is only available for premium content subscribers. To continue reading this article, please log in:
Not a Premium Content Subscriber yet? Sign up here!
- Home >
- Phillip Research Report