Keppel Ltd – Surge in asset management
- Key financials disclosed were – 1) 9M26 New Keppel net profit grew >20% YoY (1H26 +25% YoY); 2) 9M26 recurring income rose more slowly, at >10% YoY (1H26 +13%). Integrated power business 9M26 EBITDA grew a disappointingly weaker 7% YoY (1H26 +9% YoY). Maintenance work on a turbine in Keppel Merlimau offset the maiden earnings from Keppel Sakra.
- 3Q26 asset management fees spiked 48% YoY to S$154mn. YTD26 new funds under management (FUM) was S$19.5b (YTD25 S$6.7bn), of which around S$6bn was in 3Q26. Investor breadth and size have been improving. Assets monetised and realised rose by S$380mn in 3Q26 to S$940mn, driven by the S$343mn sale of a 40% stake in Empire City (Vietnam).
- Our FY26e adjusted PATMI is unchanged. We maintain BUY with an unchanged target price of S$13.80. The asset management franchise continues to build strength, with the target to double FUM to S$200bn by 2030 unchanged (CAGR ~15%). Assets monetised in the pipeline are another S$2.8bn (six rigs and Keppel South Central), equivalent to 16 to 24 cents of special dividend. Operationally, electricity spreads have recovered, but maintenance work will dampen near-term earnings.
The Positive
+ Accelerating asset management growth. 3Q26 asset management fees spiked 48% YoY to
S$154mn. Fees were supported by strong new FUM, which jumped to S$19.5bn (YTD25
S$6.7bn), with around S$6bn in 3Q26. Outlook for fees remains robust, with S$23bn of deals
in the pipeline.
+ Large monetisation pipeline. Keppel will realise at least S$1.5bn of assets this year.
Another S$611mn will be recognised in 2Q27 from the 51% sale of Keppel South Central to
KREIT. In the pipeline is the remaining 49% of Keppel South Central (S$1bn), 50% stake in
Rigco’s six operational rigs (S$600mn) and M1 (S$1.2bn).
The Negative
- Weaker than expected EBITDA in power. Despite the commercialisation of the 600MW
Keppel Sakra Cogen power plant in May26, EBITDA has slowed in 3Q26. Planned major
maintenance in one of the four F-Class gas turbine units at Keppel Merlimau contributed.
- Non-Core Portfolio Drag: Overall net profit for 9M26 fell 40% YoY. This was driven by a 4%
reduction in the gross asset value of non-core assets remaining on the books, stemming from
impairments, depreciation, operating, and holding costs.
Keppel Ltd – Stronger 2H26 ahead
- 1H26 revenue was above expectations, but adj. PATMI was within expectations, 57%/50% of our FY26e forecasts, respectively. The higher revenue was due to inclusion of M1 in non-core revenue. Underlying 1H26 PATMI rose 16% YoY from the commercialisation of the Keppel Sakra Cogen 600MW power plant in May26. Interim DPS was unchanged at 15 cents.
- Despite the more turbulent environment, Keppel has monetised S$1.7bn of assets this year and is within the S$2-3bn target for FY26. Another milestone was S$106bn in funds under management (FUM) in Jul26, up around 16% YoY.
- We maintain our FY26e adjusted PATMI. Our SOTP-derived TP of S$13.80 and BUY recommendation are maintained. We expect 2H26 to be stronger operationally. Keppel Sakra's capacity is fully contracted, and it will boost capacity by 45% in 2H26. The jump in FUM will also begin to contribute to asset management fees. Operations and maintenance will gradually rise from the massive order book in DSS and Bifrost cable installations. Special dividends are at least S$117mn (or 6 cts) from the announced realisable divestments. Keppel plans to rationalise costs in M1 at a steeper pace before any disposal, but industry economics may be deteriorating even faster.

Keppel Ltd – Asset gathering and earnings growth intact
- Key financial highlights disclosed were 1) New Keppel - slightly lower net profit YoY (due to lower real estate); 2) Overall net profit - lower YoY due to absence of fair value gains and lower asset monetisation gains.
- Asset management fees grew 13% YoY in 1Q26 (FY25 +14.5%) to S$108mn, with S$2bn commitments being finalised, especially in digital infrastructure. There was no notable impact in fundraising activities from the Middle East conflict. Asian dedicated infrastructure funds continue to gather interest from investors.
- Our SOTP-derived TP of S$13.80 and BUY recommendation are maintained. The Middle East conflict has lifted electricity margins, particularly for longer-dated contracts. We expect customers to place a premium and will look to secure longer-term electricity contracts. 2H26 earnings will be anchored by the commencement of 600MW Keppel Sakra, an increase in funds under management, the sale of Bifrost cables, and the completion of DSS projects. The assets monetisation target in FY26 is S$2-3bn (FY25 S$2.8bn), which will support special dividends. Middle East conflict has essentially lifted electricity spreads and improved the attractiveness of AssetCo rigs.
The Positive
+ Recovery in electricity spreads. Electricity (spark) spreads have climbed significantly since
the Middle East conflict. The company mentioned that blended spark spreads were declining
around S$10 YoY, but post the Middle East conflict, they have been up more than S$20.
+ Better outlook for the S$4.3bn Assetco rigs. The long-dated oil curve has trended up. It
has resulted in very strong inquiries for Assetco’s jackups and rigs. Day rates are also 10-15%
higher upon renewal. There are 13 vessels in Assetco, of which six jackups are completed,
and another seven are at various stages of completion.
The Negative
- Small disruption to gas supply so far. The force majeure on LNG supply due to the Middle
East conflict has impacted a very small percentage of Keppel’s gas supply. The replacement
gas will then be sourced from GasCo at spot JKM rather than the typical Brent-indexed price.
The company did add that blended cost with replacement gas has normalised. We believe
GasCo has a Brent-based LNG long-term contract that can increase its offtake.
Keppel Ltd – Giving more, Growing more
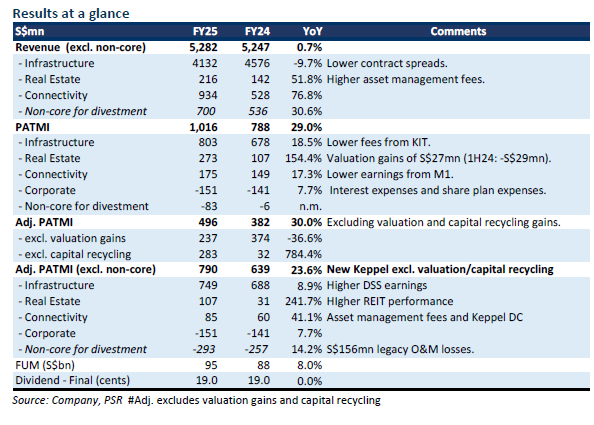
- FY25 adjusted revenue and PATMI were within our expectations at 97%/96%, respectively, of our forecast. FY25 results exclude M1, which is classified as an asset for sale. Ordinary dividend was maintained at 34 cents. A 12.7-cent special dividend was announced (2-cent cash + 1 Keppel REIT for every 9 Keppel shares).
- FY25 underlying or (New Keppel) earnings 24% YoY to S$790mn. All three divisions enjoyed growth led by real estate asset management and operating performance at Keppel REIT. Infrastructure growth was driven by higher demand for decarbonisation & sustainability solutions (DSS), despite a weaker electricity spread.
- We lower our headline earnings due to the incorporation of non-core operations. Our SOTP-derived TP is raised to S$13.80 (prev. S$12.20) and the BUY recommendation is maintained. We raised our earnings and PE multiples for infrastructure and asset management to align closer with global peers. New Keppel earnings growth will be supported by asset management fees, lower interest rates, cost cuts, the Keppel Sakra Cogen power plant, and maintenance income from subsea cables and DSS. Special dividends will be pegged to 10-15% of assets monetised p.a. Assets earmarked for monetisation total S$13.5bn by 2030 (avg. S$2.7bn p.a.).
The Positive
+ Growth in core operations. Core PATMI of New Keppel rose 23.6% YoY in FY25 to S$790mn.
Infrastructure earnings manage to grow despite a softer spread and lower asset
management fees. DSS EBITDA jumped 32% to S$130mn despite a softer spread and higher
contribution from KIT. Real estate earnings surged due to asset management fees, Keppel
REIT's operating performance, and lower interest expenses. Connectivity improvement was
from acquisition fees and earnings from Keppel DC REIT.
Keppel Ltd – Asset management franchise building momentum
- Limited financials were provided, except that the 9M25 core net profit rose over 25% YoY. The growth rate is in line with 1H25 core net profit that climbed 29% YoY to S$444mn (excluding connectivity). More importantly, 9M25 recurring net profit (asset management and operating income excl. corporate) rose 15% YoY, faster than the 7% in 1H25.
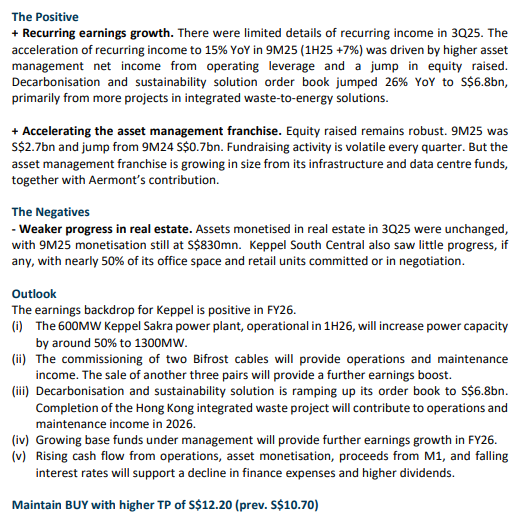
- Asset management fees rose an estimated 8% YoY to S$104mn in 3Q25. The asset management franchise continues to build momentum. Equity raised 9M25 was S$2.7bn, a massive jump from 9M24 S$0.7bn. 3Q25 equity raised was S$0.8bn. Assets monetised jumped by S$1.47bn (M1 S$1.28bn/800 Super S$0.18bn) in 3Q25 (1H25 S$915mn).
- Our FY25e forecast is unchanged. We raised our SOTP-derived TP from S$10.70 to S$12.20 as we roll over our valuations to FY26e earnings. We maintain our BUY recommendation. FY26e will register stronger recurring earnings growth driven by the operations and maintenance income from Bifrost subsea fibre and waste to energy projects, Keppel Sakra Cogen Plant becomes operational 1H26, and rising funds under management. Other drivers of the share price include higher dividends from the planned S$14bn asset monetisation and the outstanding S$407mn share buyback programme. A loss from the M1 disposal will not affect dividends.
Keppel Ltd – Ring ring, come collect your cash
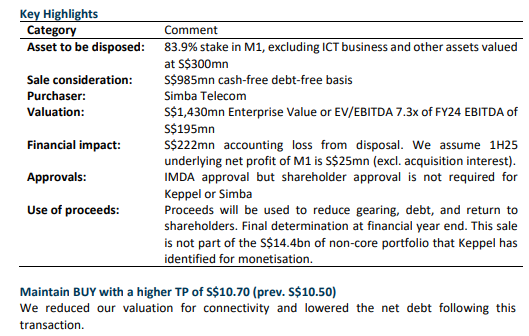
- Keppel will dispose of its 83.9% effective stake in M1’s consumer business for S$985mn cash to mobile operator Simba Telecom. Keppel will retain M1’s information and communication technology (ICT) business that can support the growth in data centre and subsea operations.
- Keppel will recognise a loss of S$222mn from the disposal. The transaction requires approval from the IMDA, but shareholder approval is not required. Detailed use of the proceeds will be decided at the financial year end.
- We view the transaction positively. Mobile competition has turned extremely competitive, capex heavy and a drag on group earnings. We assume M1's underlying earnings in 1H25 is S$25mn (excluding acquisition interest). Our SOTP-derived TP is raised to S$10.70 (prev. S$10.50) and BUY recommendation maintained. We lowered our valuations for the remaining connectivity assets but included the proceeds from sale. Keppel’s asset light model designed to deliver the entire value chain for data centres from power, connectivity, operations, capital and asset management, is reinforced from this transaction.
Keppel Ltd – Clarity in “hong bao” draws
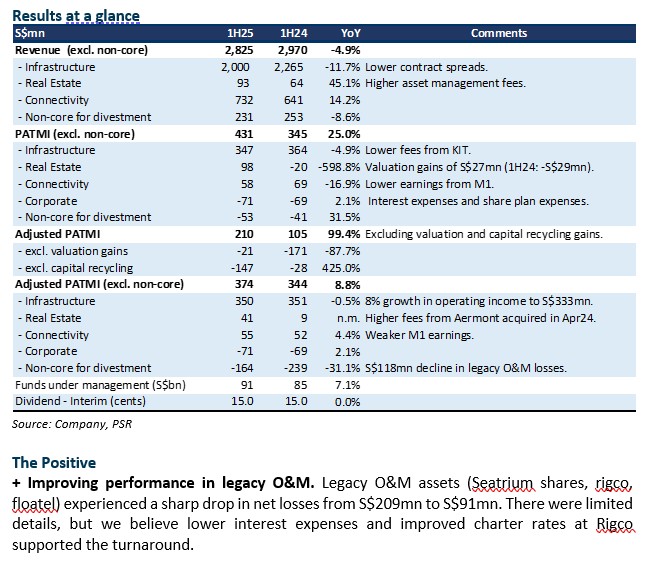
- 1H25 revenue and adjusted PATMI were within our expectations at 44%/43% respectively of our FY25e forecast. Adjusted PATMI (excl. non-core / valuation/divestments) grew 9% YoY to S$374mn primarily due to asset management fees contributed by Aermont.
- Keppel has separated a pool of assets worth S$14.4bn in the balance sheet (with S$4.7bn NAV) deemed non-core that will be monetised. Management is reiterating its target of S$10-12bn asset monetisation by end 2026, of which S$7.8bn has been completed. The management has provided greater clarity on the assets that will be monetised and capital returned to shareholders. A S$500mn share buyback programme was announced whilst the interim dividend was maintained at 15 cents.
- We maintain our FY25e adjusted earnings. Our SOTP-derived TP is raised to S$10.50 (prev. S$8.00) and BUY recommendation is maintained. We raised our valuations for infrastructure and asset management, driven by the expected earnings spurt over the next 2-3 years. We also removed the holding co discount due to the virtuous synergies as asset owner and operator across the key divisions of infrastructure, real estate, asset management, and connectivity. FY26e will be a year of growth from Keppel South Central, Keppel Sakra Cogen power plant, and Bifrost cables completions.
Keppel Ltd – Earnings growth is more visible
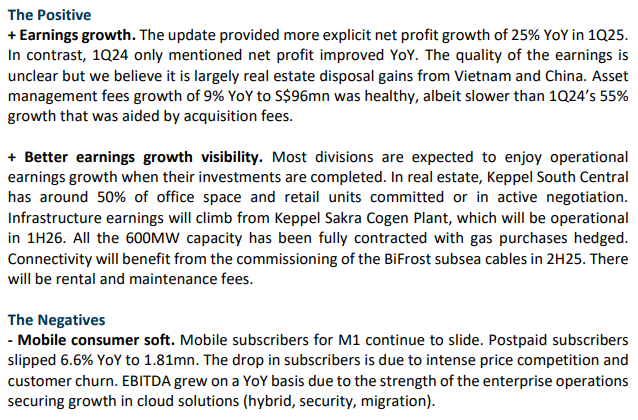
- Limited financials were provided except 1Q25 net profit was up 25% YoY. Growth was driven by infrastructure and real estate. Not disclosed was the contribution of valuation gains in net profit.
- Asset management fees grew 9% to S$96mn, supported by S$1.6bn of equity raised. Asset monetised has been S$347mn YTD. No change to the S$10-12bn monetisation target (cumulative: S$7.2bn). Part of the monetisation will include 63.36mn Seatrium shares available for sale from end Mar25.
- We maintain our FY25e forecast. Our SOTP-derived TP of S$8.00 and BUY recommendation is unchanged. There is improved visibility of (operating) earnings growth from 2H25 onwards from several projects namely leasing of Keppel South Central, commissioning of Bifrost cables and Keppel Sakra Cogen Plant.
Keppel Ltd – Rewarded as the company transitions
- FY24 adjusted PATMI was above expectations at 110% of our FY24e forecast. Adjusted PATMI declined 4.9% YoY to S$357mn. Losses in the real estate division stabilised but infrastructure was weaker than expected due to lower contributions from KIT and MET. Management is reiterating their target of S$10-12bn asset monetization by end 2026. Currently, S$7bn has been completed. The pool to monetize is at least S$17.5bn.
- We nudge our FY25e earnings by 2% from higher asset management income. Our SOTP-derived TP is raised to S$8.00 (prev. S$7.60). Our BUY recommendation is maintained.
- We expect lacklustre earnings in FY25e from muted real estate sales, competitive mobile markets, and softer renewable earnings. Vessel sales in assetco can materialise as charter income as cash flow builds up. Operating earnings will be strong in FY26e as the new Keppel Sakra Cogen power plant and Bifrost cables are operational. Keppel pays an attractive yield of 5% as the company transitions into an asset manager leveraged on data centre infrastructure and operations rollout through its fund management, renewable energy, cooling and subsea cable operations.


Keppel Ltd – Surfing the huge data centre wave
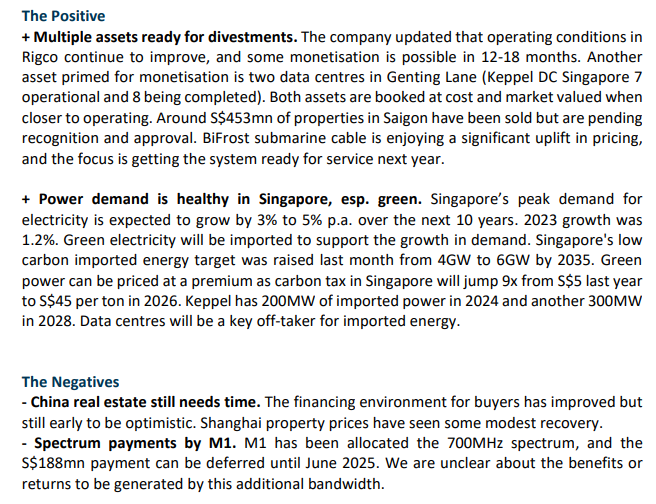
- Limited financials provided except 9M24 net profit comparable YoY. We believe 3Q24 net profit declined due to lower real estate earnings. Monetisation more than doubled by S$453mn to S$733mn.
- The huge wave in data centre demand has catalysed multiple growth drivers for Keppel: 1) Around S$10bn of funds under management are available for greenfield data centres; 2) Prices for Bifrost transmission cable has more than doubled; 3) Imported green power into Singapore will more than double; 4) Huge demand from commercialisation of two data centres in Genting Lane. There are both divestment gains and long-term recurrent asset management, operations and maintenance fees from these opportunities.
- No change to our FY24e forecast and SOTP-derived TP of S$7.60. Our BUY recommendation is unchanged. Asset monetisation target of S$10-12bn from 2020 to end-2026 has not changed (or another S$4-6bn). Leading the asset sale is Rigco where operation conditions continue to improve. In the medium term, we believe the surge in data centre demand in driving demand for power in Singapore, more funds under management and raised the valuations of its greenfield submarine and data centre assets.
Get access to all the latest market news, reports, technical analysis
by signing up for a free account today!
Login
The full article is only available for premium content subscribers. To continue reading this article, please log in:
Not a Premium Content Subscriber yet? Sign up here!
- Home >
- Phillip Research Report