Keppel DC REIT – Deepening Japan presence
- KDCREIT and Keppel have entered into agreements to jointly acquire a 90% effective interest in Tokyo Data Centre 4 and Tokyo Data Centre 5, two freehold, hyperscale fully fitted colocation data centres in Inzai City, Greater Tokyo, from unrelated third-party sellers. The aggregate purchase consideration is JPY190bn (S$1,549mn, 100% basis), representing a c.2.1% discount to the properties’ valuation of JPY194bn (S$1,581mn). KDCREIT will pay JPY168.4bn (S$1,372mn) for an 88.62% effective interest, while Keppel will hold a 1.38% effective interest. The existing third-party operator will retain a 10% interest in each data centre. The properties have a blended NPI yield of 4.5%-5.0%.
- The acquisition is expected to be 2.6% accretive based on FY25 pro-forma DPU. It has a contractual rent escalation of 2.8% per annum and is under-rented by at least 30%. It will be funded through a private placement to raise no less than S$600mn (43%) and JPY debt (57%).
- We maintain ACCUMULATE with an unchanged TP of S$2.46. We have yet to update our financials for the acquisition and private placement. However, the new units from the private placement are expected to increase the unit base by c.12%. We are positive on the deal as it provides exposure to high-quality, fully occupied hyperscale data centres in a key Tokyo data centre market, with strong embedded rental upside and contractual rent escalations. The acquisition is also expected to be 2.6% DPU-accretive despite the equity fund-raising.
Transaction Highlights
The acquisition combines immediate DPU accretion with multiple avenues for long-term
income growth. Tokyo Data Centre 4 and 5 are freehold colocation data centres that are
100% occupied by four investment-grade clients, with a blended WALE of 8.3 years.
Contracted average annual rent escalation is approximately 2.8%, while in-place rents are
under-rented by at least 30%, with more than 5% of rents due for renewal by 2029. WALE is
approximately 4.5 years for Tokyo Data Centre 4 and 10.6 years for Tokyo Data Centre 5,
providing a balance between reversion opportunities and long-term income visibility.
Located in Inzai City, one of Japan’s most established hyperscale data centre clusters, the
acquisition will strengthen Keppel DC REIT’s presence in one of Asia Pacific’s most attractive
data centre markets. Japan’s contribution to portfolio rental income is expected to increase
from c.9% as at 30 June 2026 to c.23% post-acquisition, while portfolio AUM is expected to
grow to S$7.6bn from S$6.3bn. Singapore will remain the largest contributor, accounting for
c.60% of the portfolio’s rental income. Japan’s favourable demand-supply dynamics should
support long-term growth, underpinned by rising cloud adoption, AI-related deployments
and digital transformation. Structural supply constraints, including power constraints,
construction bottlenecks and land scarcity, should further support the market’s growth
prospects.
Following the acquisition, contracted power capacity is expected to increase from 95% to
96%. NAV is expected to rise to S$1.75 from S$1.71, while aggregate leverage is expected to
increase from 34% to 38%. The acquisition is expected to complete in 4Q26.
Method of financing
The acquisition will be funded by ~43% equity through a private placement (at a price
between S$2.096 and S$2.142) to raise at least S$600mn, with the remaining ~57% funded
by JPY-denominated debt. The JPY debt is expected to be fully hedged, with an average
interest cost of 2.9% (1H26: 2.7%).
Keppel DC REIT – Acquisitions and higher rents drive 11% DPU growth
- 1H26 DPU of 5.71 Singapore cents (+11.3% YoY) was in line with our expectations, forming 52% of our FY26e forecast. Growth was driven by the accretive acquisition of Tokyo Data Centre 3, alongside positive rental reversions and escalations across the portfolio, partially offset by the divestment of Kelsterbach Data Centre. DI increased by 18.5% YoY, outpacing DPU growth due to a larger unit base following equity fund raisings to finance acquisitions.
- Rental reversions remained healthy at +10% in 1H26, with 2Q26 reversions moderating to c.5% (1Q26: +51%). 2H26 reversions are expected to be higher, supported by the Gore Hill Data Centre lease renewal, where rents more than doubled and will flow through from 3Q26. Portfolio occupancy declined to 92.5% from 95.6% in 1Q26 due to the expiry of the Cardiff Data Centre contract. Nevertheless, the earnings impact should be less material, as 95% of revenue-generating power capacity remains contracted.
- We maintain ACCUMULATE with a higher DDM-derived TP of S$2.46 (prev. S$2.37). We raise our FY26e/FY27e DPU estimates by 6%/7% to reflect higher rental assumptions and the continued contribution from NetCo Bonds following the termination of the proposed divestment of the Bonds and Preference Shares. Our estimates do not assume any contribution from the Guangdong Data Centres, while the potential recovery of over S$60mn in overdue rent from Bluesea remains a key upside catalyst. We expect FY26e rental reversions to be in the high-teens, driven by the lease renewal at Gore Hill Data Centre, with only 2.6% of rental income due for renewal for the remainder of FY26. The stock currently trades at an FY26e DPU yield of 5.1%.

The Positive
+ Strong balance sheet with ample debt headroom to pursue accretive acquisitions.
Aggregate leverage improved 110bps QoQ to 34% following the repayment of the
consumption tax loan for the acquisition of Tokyo Data Centre 3, leaving c.S$673mn of debt
headroom against its 40% internal cap for future accretive acquisitions. The average cost of
debt increased marginally by 10bps QoQ to 2.7%, due to new SGD loan hedges entered in
end-March 2026, which raised the fixed-rate debt proportion from 84.8% to 87%. We expect
FY26e cost of debt to remain stable at c.2.7%, with only 6% of debt due for refinancing for
the remainder of FY26. In addition, forecasted foreign-sourced distributions have been
substantially hedged through 1H27, limiting exposure to currency fluctuations.
Keppel DC REIT – Strong rental reversions in 1Q26
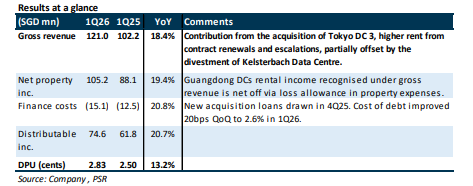
- 1Q26 DPU of 2.833 Singapore cents (+13.2% YoY) was in line with our expectations, forming 26% of our FY26e estimates. Growth was driven by the acquisitions of Tokyo Data Centre 3 and the remaining interests in Keppel DC Singapore 3 & 4, as well as stronger contributions from contract renewals and escalations, partially offset by the divestment of Kaltenbach Data Centre.
- 1Q26 portfolio rental reversion remained strong at +51% (FY25: +45%), though this was based on a very small percentage of total leases (c.0.3%). Cost of debt declined by 20bps QoQ (40bps YoY) to 2.6% and is expected to remain stable through FY26e. Portfolio occupancy eased slightly, by 0.2 ppt, to 95.6%, due to client downsizing of non–data centre space, while portfolio WALE stayed healthy at 6.5 years.
- We maintain ACCUMULATE with an unchanged DDM-derived TP of S$2.37. There is no change to our forecast. Potential recovery of over S$55mn in overdue rent from Bluesea remains a key catalyst, though still unresolved. We expect rental reversions to remain strong, but potentially lumpy for the 6% of rental income due for renewal per annum in FY26 and FY27, depending on lease maturities. There is limited first-order impact from the ongoing Middle East conflict, as electricity costs are fully passed through to colocation tenants; only common areas and vacant spaces are borne by KDCREIT, accounting for less than 3% of operating expenses. The stock trades at an FY26e DPU yield of 4.6%.
The Positives
+ Healthy financial metrics. The average cost of debt declined 20bps QoQ to 2.6%, with
84.8% of loans on fixed rates. Aggregate leverage stood at 35.1%, providing c.S$550mn of
debt headroom against the 40% internal cap to support acquisitions. We expect FY26e cost
of debt to remain stable at 2.6%, with 8.5% of debt due for refinancing in FY26.
The Negative
- Ongoing weakness at the Guangdong Data Centres. KDCREIT will continue to recognise
loss allowances for overdue rent. To date, Bluesea, the master lessee, has accumulated over
S$55mn in unpaid rent. Chip availability continues to be a bottleneck in China.
Keppel DC REIT – Record high DPU
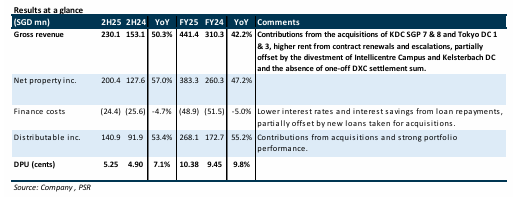
- 2H25/FY25 DPU of 5.248/10.381 Singapore cents (+7.1%/+9.8% YoY) was in line with our expectations, forming 51%/102% of our FY25e estimates. The YoY growth was driven by the acquisitions of KDC SGP 7 & 8 and Tokyo DC 1 & 3, stronger contributions from contract renewals and escalations, and lower finance costs.
- Portfolio occupancy remained stable at 95.8% QoQ. FY25 portfolio rental reversion was strong at +45% (4Q25: +2%, with no major contract renewals). Portfolio valuations rose 25.6% YoY to S$6.1bn, driven by acquisitions. On a same-store basis, it rose 3.7%.
- We upgrade from NEUTRAL to ACCUMULATE due to the recent share price performance, with a lower DDM-derived TP of S$2.37 (prev. S$2.40) as we roll forward our forecasts. We lower our FY26e DPU by 6%, reflecting the loss of income from the divestment of NetCo bonds and slightly higher assumed finance costs. The potential recovery of over S$50mn in overdue rent from Bluesea remains a key catalyst, though still unresolved. Additionally, the granting of tax transparency for SGP 7 & 8 in the coming months should provide further upside to DPU. We expect the strong positive rental reversion momentum to continue into FY26, particularly from Singapore colocation lease renewals. The stock trades at an FY26e DPU yield of 4.8%.
The Positives
+ Stable occupancy at 95.8% with strong rental reversion of +45% for FY25. 4Q25 rental
reversion was +2% due to no major contract renewals. With a large portion of the 6.4% of
leases due for renewal in FY26 by rental income coming from Singapore colocation leases,
we expect the positive reversion momentum to continue into FY26.
+ Lower finance costs. The average cost of debt for the quarter declined further to 2.8% in
4Q25 (3Q25: 2.9%), with the FY25 average cost of debt at 3%. Aggregate leverage stands at
35.3%, providing S$530mn of debt headroom against the internal cap of 40%, supporting
future acquisitions. We expect FY26e cost of debt to decline to c.2.7%, reflecting the full
year impact of lower borrowing costs and the 28.8% of loans on floating rates.
+ Higher portfolio valuations. Portfolio valuations rose 3.7% YoY on a same-store basis and
25.6% including acquisitions, led by Singapore (+6%) and Ireland (+13%) driven by strong
operating performance. This offset declines by 3.5% in Australia, 16% in China, and 7% in the
UK.
Keppel DC REIT – DPU growth despite the preferential offering
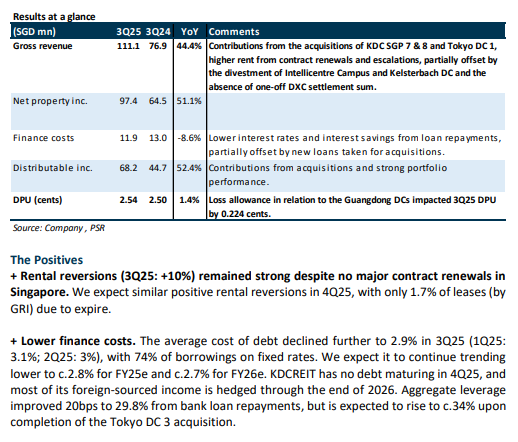
- 3Q25/9M25 DPU of 2.54/7.67 Singapore cents (+1.4%/+11.7% YoY) was in line with our expectations, forming 24/74% of our FY25e estimates. The YoY increase was driven by the acquisitions of KDC SGP 7 & 8 and Tokyo DC 1, stronger contributions from contract renewals and escalations, and lower finance costs. The 180.6mn new units from the preferential offering, listed on 22 Oct 2025 and entitled to distributable income from 1 Jul 2025, impacted DPU. Had the preferential offering not taken place, 3Q25/9M25 adjusted DPU would have been 2.74/7.87 cents.
- Portfolio occupancy remained stable at 95.8% QoQ. With no major lease renewals in 3Q25, rental reversions eased to 10% (vs. 51% in 1H25), still healthy. The 2.8% DPU accretive acquisition of Tokyo DC 3 is on track for completion by end-2025.
- We maintain NEUTRAL with a higher DDM-derived TP of S$2.40 (prev. S$2.33). We cut our FY25e DPU by 2% to reflect the impact of the preferential offering, but raised our FY26e DPU by 4% to reflect the expected full-year contribution from Tokyo DC 3 and lower interest rates. The potential recovery of >S$45mn in overdue rent from Bluesea remains a key catalyst, though still unresolved. We expect high single-digit rental reversions in 4Q25 for the 1.7% of leases expiring, with no major renewals in Singapore. The stock trades at an FY25e DPU yield of 4.3%.
Keppel DC REIT – Yet another quarter of exceptional rental reversion
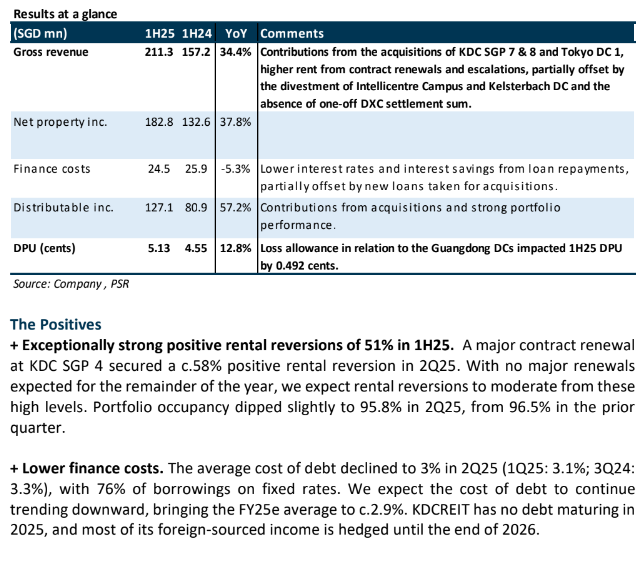
- 1H25 DPU of 5.133 Singapore cents (+12.8% YoY) was in line with our expectations, forming 51% of our FY25e estimates. The YoY increase was driven by the acquisitions of KDC SGP 7 & 8 and Tokyo DC 1, stronger contributions from contract renewals and escalations, and lower finance costs due to reduced interest rates and loan repayments.
- KDCREIT delivered another quarter of exceptionally strong positive rental reversions, achieving 51% for 1H25 (2Q25: c.58%). The bulk of the uplift stemmed from a major contract renewal at KDC SGP 4. There are no major contract renewals in 2H25, with just 2.6% of leases by GRI expiring. Gearing remains low at 30%, though it is expected to rise to c.35% with the planned debt drawdown to finance the land lease extensions for KDC SGP 7 and 8.
- We downgrade from ACCUMULATE to NEUTRAL with a higher DDM-derived target price of S$2.33 (prev. S$2.25) due to the recent share price performance. We raise our FY25e/FY26e DPU estimates by 2%/1% as we factor in stronger rent reversions in our forecasts. The collection of over S$40mn in overdue rent from Bluesea is a potential catalyst, although it remains unresolved. We expect rental reversions to moderate in 2H25, with no major contract renewals in Singapore, the only location capable of achieving >50% reversions, supported by supply constraints and strong demand. The stock is currently trading at an FY25e DPU yield of 4.5%. With the recent acquisitions, KDCREIT’s enlarged portfolio and market capitalisation have led to its re-entry into the Straits Times Index, effective June 23, 2025.
Keppel DC REIT – Accretive acquisitions power growth
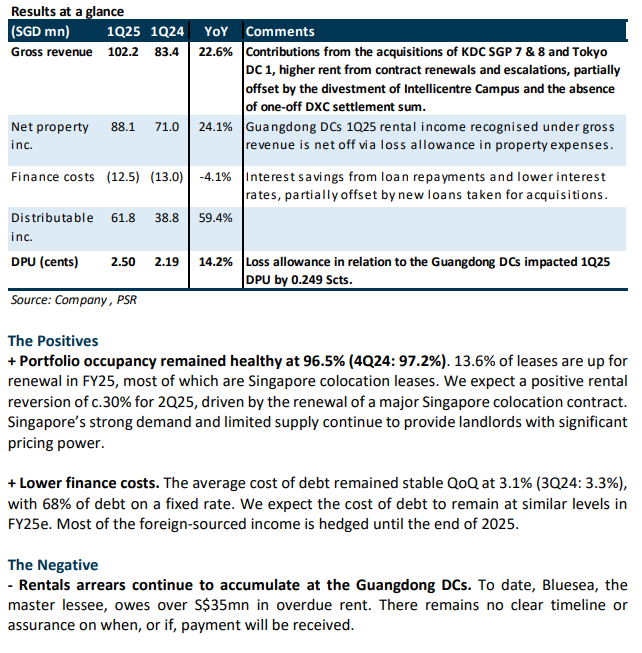
- 1Q25 DPU of 2.503 Singapore cents (+14.2% YoY) was in line, forming 25% of our FY25e estimates. The YoY growth in DPU was driven by the acquisitions of KDC SGP 7 & 8 and Tokyo DC 1, as well as lower finance costs from reduced interest rates and loan repayments.
- KDCREIT achieved healthy portfolio rental reversions of +7% in 1Q25, despite no major contract renewals during the quarter. Gearing improved to 30.2% following the completion of the divestment of Kelsterbach Data Centre in March 2025. It is expected to rise to c.35% with the planned debt drawdown to finance the land lease extensions for KDC SGP 7 and 8.
- We upgrade to ACCUMULATE with an unchanged DDM-derived target price of S$2.25 due to the recent share price performance. We expect rental reversions to be strong in 2Q25, possibly exceeding 30%, as major colocation contracts in Singapore are up for renewal. The collection of c.S$35mn in overdue rent from Bluesea is a potential catalyst, but it remains unresolved. The share is currently trading at an FY25e DPU yield of 5%. Our estimates remain unchanged.
Keppel DC REIT – Strong rental growth expected in 2025
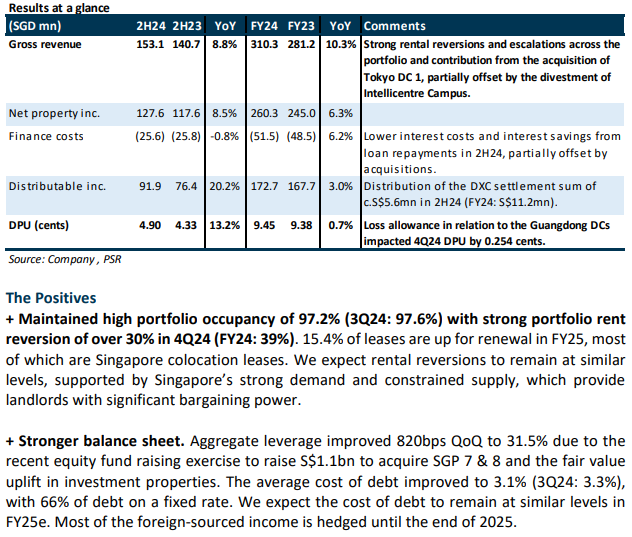
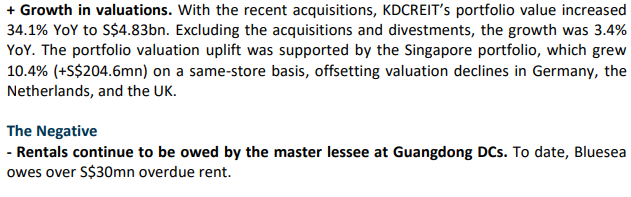
- FY24 DPU of 9.451 Singapore cents (+0.7% YoY) met our FY24e expectations. This was driven by the distribution of the DXC settlement sum of S$11.2mn, exceptionally strong positive portfolio rental reversions of 39% in FY24, and the contribution from the acquisition of Tokyo DC 1. However, it was partially offset by loss allowances for the Guangdong DCs and the depreciation of foreign currencies against the SGD.
- Completed the acquisition of a 99.49% economic interest in Keppel DC Singapore 7 & 8 (KDC SGP 7 & 8) in December. These AI-ready hyperscale data centres strengthen KDCREIT’s foothold in Singapore’s thriving data centre market, characterised by strong demand and constrained supply.
- We maintain NEUTRAL with a higher DDM-derived target price of S$2.25 from S$2.16. We lower our FY25e DPU estimates by 4% as we roll forward our forecasts, incorporating recent acquisitions, the expanded share base from the equity fund raising, and the continued non-collection of rental income from the Guangdong DCs. We expect rental reversions to remain strong, exceeding 30% for most of the 15.4% of leases due for renewal in FY25 by rental income, primarily from Singapore colocation renewals. The collection of overdue rentals from Bluesea remains potential catalyst. The share is currently trading at an FY25e DPU yield of 4.5%.
Keppel DC REIT – Acquisition of KDC SGP 7 and 8
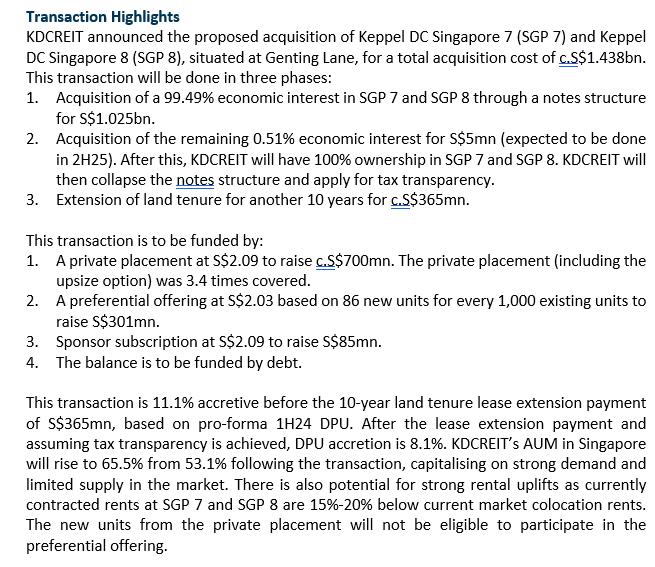
- KDCREIT is proposing to acquire Keppel DC Singapore 7 (SGP 7) and Keppel DC Singapore 8 (SGP 8), situated at Genting Lane, for a total consideration of c.S$1.438bn (including 10-year land lease tenure extension).
- The transaction is 8.1% accretive based on 1H24 pro-forma DPU, assuming the extension of the land lease and tax transparency is achieved.
- We maintain NEUTRAL with an unchanged TP of S$2.16, post rights issue, our target price is S$2.14. While the transaction will provide immediate accretion to DPU, we believe there will be a share price overhang in the near term from the private placement new shares (c.15% of total units currently outstanding) of S$2.09. The current FY24e/25e DPU yields are 4.3%/4.7% (before acquisition).
Keppel DC REIT – Rental reversions remain robust in 3Q24
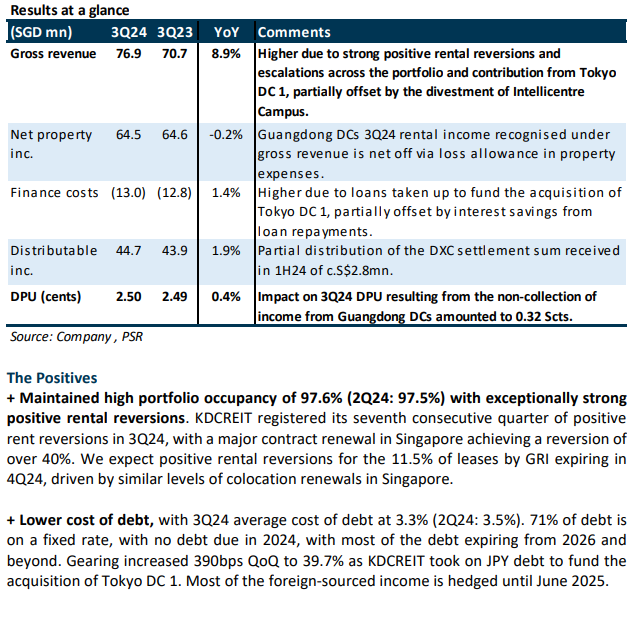
- 3Q24 DPU of 2.501 Singapore cents (+0.4% YoY) exceeded our expectations, achieving 27% of our FY24e forecast. This was due to the exceptionally strong positive portfolio rental reversions, continuing the trend from 2Q24. A major contract renewal in Singapore secured a positive reversion of over 40%.
- Tokyo DC 1 has commenced contributions following the acquisition completion on 31 July 2024. The rental income from the Guangdong DCs continues to be net off via loss allowances, and the impact to 3Q24 DPU was 0.32 Scents.
- Upgrade to NEUTRAL from REDUCE with a higher DDM-derived target price of S$2.16 from S$1.93. We raise our FY24e/25e DPU estimates by 5%/9% after factoring in stronger positive rental reversions for the portfolio and lower finance costs. We lower our risk-free rate assumption to 2.5% from 3%, and as a result our cost of equity has fallen from 7% to 6.83%. We expect rental reversions to remain at similar levels, particularly the Singapore leases, given the strong demand and limited supply. Our FY24e forecast already assumes no rental contribution from the Guangdong DCs, so further loss allowances will not affect our forecasts. Potential catalysts include accretive acquisitions and the collection of rentals in arrears from Bluesea. Due to the recent share price rally, the FY24e/25e DPU yields are only at 4.2%/4.7%.
Get access to all the latest market news, reports, technical analysis
by signing up for a free account today!
Login
The full article is only available for premium content subscribers. To continue reading this article, please log in:
Not a Premium Content Subscriber yet? Sign up here!
- Home >
- Phillip Research Report