HRnetGroup Limited – Becoming a high yield stock
- 1H26 revenue met expectations at 48% of FY26e forecast, but adj. PATMI was below at 44%. Adj. PATMI declined 18% YoY due to lumpy government grants in the prior year. Operating profit rose 9% YoY to S$20.1mn. Interim dividend increased 10% to 2.20 cents with a payout ratio of 103%.
- Revenue was marginally lower by 1.1% YoY in 1H26. Singapore’s revenue contracted for the 5th consecutive quarter with a 4.9% YoY decline. SE Asia rose 23%, followed by North Asia at 2.5%. Semiconductor and AI-related roles were the growth areas, with Taiwan the strongest geography.
- We maintain our FY26e forecast on expectations of stronger 2H26. Our target price of S$0.82 and ACCUMULATE recommendation are maintained. Growth in professional recruitment will be led by manufacturing and AI. Flexible staffing outside Singapore is building scale and momentum. HRnet has announced plans to return its surplus capital progressively, especially as operations stabilise. The company generates FCF of around S$46mn with cash and securities worth S$332mn (46% of market cap). It is sufficient to sustain its dividend payout of around S$44mn. The company is currently trading at a dividend yield of 5.9%.
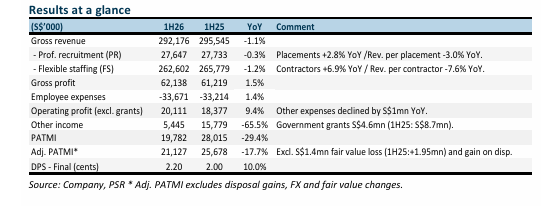
The Positive
+ Stabilising Singapore earnings. Gross profit in Singapore grew 2% YoY to S$32mn, marking
the first increase in at least three years. PR has begun to stabilise after a massive contraction in
FY22. There is greater confidence in hiring activity, particularly in technical roles in the
semiconductor and life sciences sectors.
The Negative
- Surprising softness in North Asia. North Asia gross profit contracted 1.1% in 1H26 to S$26mn
due to a drag in PR revenue. We believe China was the source of weakness, in line with the
overall weakness in the economy. FS technical roles in the semiconductor industry are gaining
ground in North Asia following the recent filling of senior positions.
HRnetGroup Limited – Overseas levers of growth
- FY25 revenue met expectations but adj. PATMI was below our FY25e forecast at 100%/92%. Government grants and interest income were lower than modelled. Full-year dividends rose 5% to 4.2 cents with a payout ratio of 78%. Adjusted PATMI declined 20% YoY due to the timing of government grants.
- Revenue grew 3% in 2H25, supported by 26% and 12% rise in North Asia and SE Asia, respectively. Singapore was the weakest, with a 3% contraction in revenue due to sluggish hiring activity. Taiwan was the bright spot in semiconductor, technology and F&B roles.
- We lower our FY26e adj. PATMI forecast by 3% to S$48mn due to lower government grant assumptions. Our target price is raised to S$0.82 (prev. S$0.78) as we rollover valuations to FY26e. Our ACCUMULATE recommendation is maintained. Activity in Singapore remains soft with candidates less mobile and competition more intense, especially in the middle market. Countries such as Taiwan and Malaysia are the core growth geographies. HRnet is building on its senior executive search roles through its regional network of 18 cities, consistent experience and preferred pricing structure. The company is paying an attractive dividend yield of 5.7%, backed by a cash pile and securities worth S$337mn (47% of market cap). Excluding cash and interest income, the underlying business is valued at 10x PE FY25.


HRnetGroup Limited – Pockets of growth
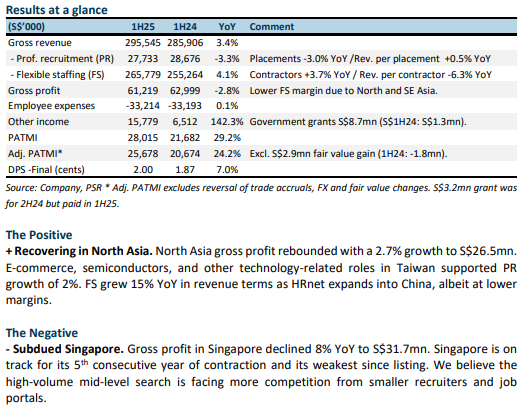
- Results were within our expectations. 1H25 revenue and adjusted PATMI were 51%/52% of our FY25e forecast. There was a pull forward of government grants in 1H25 of S$4.2mn compared to a year ago. Grants pushed adjusted PATMI up 24% YoY to S$25.7mn. Interim dividends rose 11% to 2 cents with a payout ratio of 67%.
- Singapore remains weak for HRnet, with gross profits down 8% YoY to S$33mn. FY25e is likely the 4th consecutive year of decline. North Asia turned around with a growth of 2.7% YoY to S$26.5mn, led by professional recruitment in Taiwan.
- We maintain our FY25e forecast and target price of S$0.78. Our ACCUMULATE recommendation is maintained. The company’s footprint across 18 Asian cities gives it access to identify and capture vertical opportunities in professional recruitment. HRnet is tapping into hiring opportunities in technology roles in Taiwan. With intense competition in mid-level search and increased demand for C-suite roles, HRnet is pivoting toward senior executive opportunities. On flexible hiring, HRnet is leveraging its balance sheet and process excellence to expand geographically into China, Malaysia, and Indonesia. The company is paying an attractive dividend yield of 5.8% backed by a cash pile of S$232mn.
HRnetGroup Limited – Collecting income, no growth yet
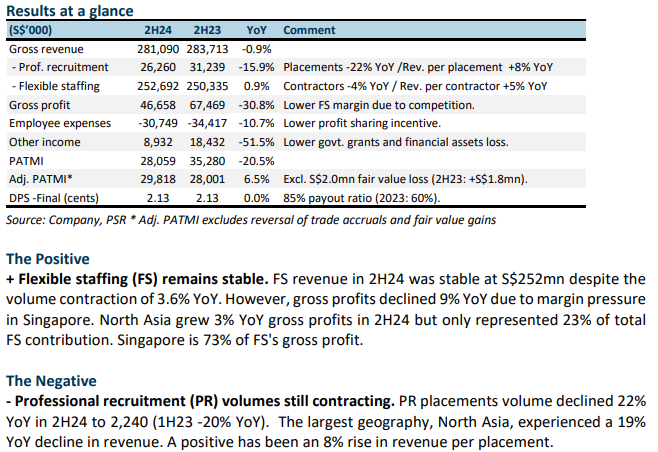
- Results were below our expectations. FY24 revenue and adjusted PATMI were 95%/85% of our FY24e forecast. Adding back the S$3.1mn delay in progressive wage credit scheme (PWCS) payment, the results will be 91%. Dividends were maintained at 4 cents in FY24, with a payout ratio of 85%.
- Professional recruitment remains the weakest segment, declining 16% in 2H24. It has been on a decline for the past 2.5 years. Weak and uncertain macro conditions are causing delays or hesitancy in hiring. Flexible staffing revenue is stable with 1% growth in 2H24.
- HRnet is widening its strategy to access a larger recruitment market share. The company is targeting more C-suite roles and entering the recruitment of foreign manpower in the service industry. We are lowering FY25e earnings by 14%. Recovery in recruitment has been delayed and may worsen with the current macro uncertainty. We are still forecasting modest growth in FY25e including the delayed PWCS payment and additional growth from new target segments. Our recommendation is downgraded from BUY to ACCUMULATE and the target price lowered to S$0.78 (prev. S$0.82). The company is paying an attractive dividend yield of 5.8% with planned share buyback of S$11.2mn (~16mn shares) backed by a net cash of S$258mn.
HRnetGroup Limited – Hiring still sluggish
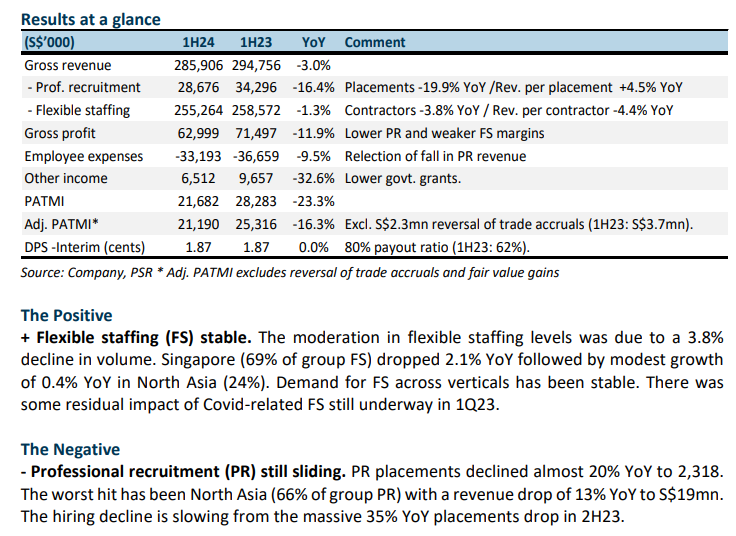
- Earnings were below our expectations. 1H24 revenue and adjusted PATMI were 47%/37% of our FY24e forecast. 1H24 adjusted PATMI declined 16% YoY to S$21mn. Professional recruitment remains the weakest segment with revenue declining 16% YoY and volumes down 20%.
- Flexible staffing revenue was more stable with a 1.3% YoY decline. Clients have become more careful in hiring decisions and rely more on flexible staffing for their hiring needs.
- The two largest markets for professional recruitment are Singapore and China. Both markets are facing clients cautious about their hiring plans and candidates cautious about switching jobs. The hiring environment has been weaker than expected. We decreased our FY24e adjusted PATMI by 6% to S$53.5mn, with revenue lowered by 2%. Our BUY recommendation is maintained but the target price lowered from S$0.85 to S$0.82. We benchmark our valuations to 11x PE ex-cash FY24e. It remains a discount to global peers trading at an average PE of 21x PE and 9x EV/EBITDA.
HRnetGroup Limited – Expecting growth to creep up
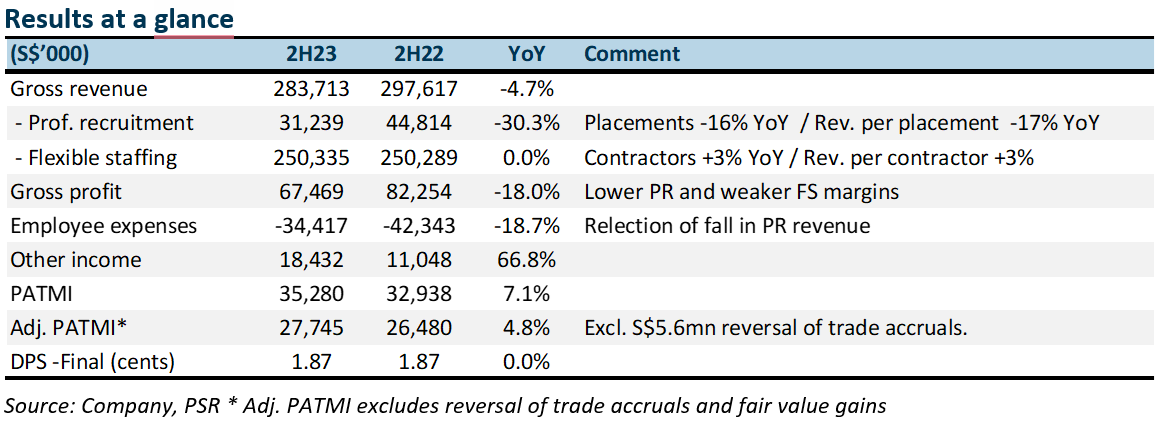
- Results were marginally below expectations. FY23 revenue and adjusted PATMI were 97%/95% of our forecast. 2H23 grew 5% YoY to S$27mn. Professional recruitment revenue was weaker than expected with a decline of 30% YoY. Placements were the lowest since listing.
- Flexible staffing remained resilient. Margins were softer with the absence of pandemic-related roles. Growth was from finance and manufacturing.
- Hiring in technology roles from start-ups to semiconductors has been a growth vertical for HRnet. However, the pace of hiring in this segment has slowed significantly. Growth will now come from capturing a larger share of customer budgets. HRnet office network and sphere of service including solutions in instant pay and claims, can raise the support of client needs in the region. Flexible staffing is benefiting from a rising wage environment, tight supply of local manpower and increased outsourcing. General hiring conditions are weak, particularly in China. We lowered our FY24e earnings by 11% to S$57mn. Our BUY recommendation is maintained. With the more tepid growth, we are reducing our valuation metric to 11x PE ex-cash FY24e (prev. 12x PE). Target price lowered from S$0.88 to S$0.85. It remains at a huge discount to global peers trading at an average PE of 19x.
The Positive
+ Flexible staffing (FS) is the key performer. Around 94% of FS revenue is from Singapore. 2H23 FS revenue in Singapore rose 1.8% YoY. Despite the decline in number of contractors, the rise in wages supported revenue. Government policy to drive up wages of the lower income also pushed income from government subsidies to S$6.6mn in 2H23 (2H22: S$1.2mn).
The Negative
- Professional recruitment (PR) is still the weak spot. The number of PR hirings in 2H23 fell 17% YoY to 2,856, due to hiring freezes and cautious sentiment. Revenue per placement declined 17% YoY as more placements were completed for junior roles.
Outlook
We are forecasting a 5% contraction in volumes for PR. There are limited indications corporates are ramping up their hiring of managerial roles in this region. FS revenue is expected to grow stronger from higher wages and improvement in volumes especially in Taiwan. The FS operations in Taiwan is beginning to hit scale and gain more traction with corporates.
Maintain BUY and lower TP of S$0.85 (prev. S$0.88).
HRnetGroup enjoys net cash of S$303mn with barriers of scale with more than 500 full-time recruitment consultants across 17 cities. There is another S14mn outstanding in their committed share buyback programme.
HRnetGroup Limited – Stability creeping in
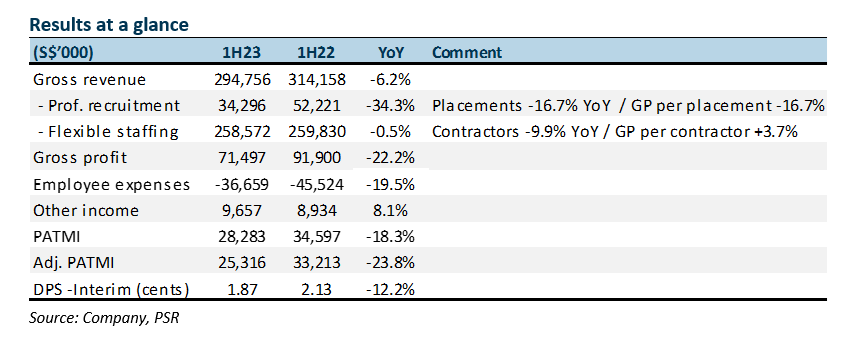
- The results were below expectations. 1H23 adjusted PATMI was 40% of our FY23e forecast. Weakness in earnings was largely due to professional recruitment contracting 34% YoY in revenue. North Asia experienced a major decline in technology hiring.
- Flexible staffing was resilient with revenue suffering a modest 0.5% YoY decline. The reduction in pandemic-related roles was replaced with luxury retail, consumer and logistics.
- We lowered our FY23e earnings by 11% to adj. PATMI of S$56mn. We cut our professional recruitment volume and price assumptions. Our BUY recommendation is maintained with a lower target price of S$0.88 (prev. S$0.98). The target price is 12x PE FY23e ex-cash. We believe hiring activities will trend sideways in 2H23 after the stellar growth in FY22, propped up by technology and pandemic-related placements.
The Positive
+ Flexible staffing (FS) resilient and flexible staff cost. Despite the absence of pandemic-related hiring, FS revenue was resilient. Sectors supporting FS in 1H23 were banking, luxury retail, consumer and logistics. FS is also expanding outside Singapore, namely Taipei, Hong Kong and Jakarta. In line with the weaker revenues, employee cost was down 19% YoY, from lower bonus payout and headcount reduction of 83.
The Negative
- Steep drop in North Asia and Singapore professional recruitment (PR). The drag on 1H23 earnings was the 37% and 31% YoY decline in North Asia and Singapore PR respectively. There was a severe drop in semiconductor and technology type placements. PR hiring will now be driven by industrial, engineering, lifescience and consumer sector roles.
Outlook
We expect FS to remain the near-term growth driver as corporates pivot towards contingent workers in an uncertain macro backdrop. Another FS growth pillar is expansion overseas, where its advantages are the track record, technology and capital. The strength of the ownership model was reflected by the flexibility to reduce employee expenses. From the $30mn share buyback plan announced in June 2022, there is a balance of S$16.6mn to be completed. In PR both business and candidate confidence is weak, negatively impacting demand and supply.
Maintain BUY and lower TP of S$0.88 (prev. S$0.98).
Our FY23e forecast is cut by 11% to adj. PATMI of S$56mn. The target price is a huge discount to global peers trading at 17x PE. HRnetGroup enjoys net cash of S$303mn with barriers of scale from its nearly 700 recruitment consultants across 16 cities.
HRnetGroup Limited – China speedbump
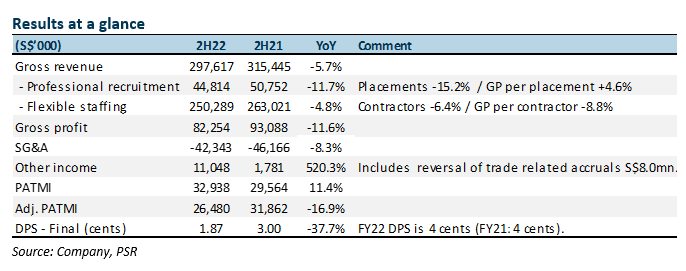
- FY22 revenue met expectations but PATMI was below (at 90% of our FY22 forecast). The loss of COVID-related staffing revenue and the lockdown in China affected 2H22 margins and earnings.
- Professional recruitment declined 12% YoY to S$44.8mn. Placement volume was down 15% YoY with pricing up 5%. Flexible revenue dropped a more modest 5% YoY, led by a 6% fall in volume. Margins suffered from a 9% decline in gross profit per contractor.
- We expect a softer 1H23 as economic conditions soften and hiring decisions to get delayed. Recovery in 2H23 will come from the re-opening and normalization of activities in China. We lowered our FY23e PATMI forecast by 6%. Our BUY recommendation is maintained but we have lowered our target price to S$0.98 (prev. S$1.18), 12x PE FY23e ex-cash.
The Positive
+ Transitioning well from COVID staffing needs. Revenue from Covid-related staffing was a drag on growth. For instance, in FY21, the average monthly number of contractors jumped 36% to 16.92k. It managed to still grow by 2% in FY22, and remains 45% above pre-pandemic levels. Margins from such staffing needs were higher due to the urgency in demand.
The Negative
- Professional recruitment softer in Singapore and China. 2H22 experienced a major 15% fall in placement volume. The weakest countries were Singapore and China. Demand has moderated in Singapore as confidence in the macro environment has waned. China’s lockdown created much uncertainty in hiring decisions. Strength was from Taiwan and Hong Kong.
HRnetGroup Limited – Faster growth outside Singapore
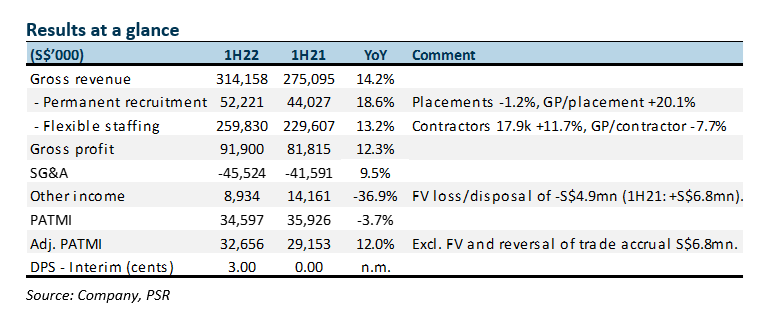
- Results were within expectations. 1H22 revenue and PATMI was 51%/48% of our FY22e forecast. 1H22 PATMI grew 12% YoY to S$32.6mn, excluding fair value losses and one-off reversal of trade accruals.
- Revenue growth of 14% was from both permanent recruitment (+19% YoY) and flexible staffing (+13% YoY). Maiden interim DPS of 3 cents was announced.
- Growth in 1H22 was a mixture of pricing and volumes driven by a 30% revenue growth in Rest of Asia. Expanding the franchise outside Singapore is a key growth driver. Rest of Asia is now 40% of revenue from 28% in FY20. We maintain our FY22e forecast. Our BUY recommendation and target price of S$1.18 is maintained, 12x PE FY22e ex-cash. Flexible staffing demand is driven by new geographies and re-opening sectors. Permanent hiring is supported by the demand for unfilled job vacancies and an increase in full-time consultants.
The Positives
+ Strong growth outside Singapore. Revenue from Rest of Asia grew 30% to S$107.8mn. These regions now account for 40% of total revenue, a jump from the 26% in FY18. Revenue has grown in region from increasing the number co-owners to build the franchise and expanding into flexible staffing services.
+ Returning S$100mn cash, as it piles up. FCF generated in 1H22 was S$33.1m (1H21: S$3.5mn). Net cash on the balance sheet is S$312.7mn (1H21: S$297.1mn). HRnet announced a maiden interim dividend of 3 cents per share (S$30mn). Together, with planned share buyback of S$30mn, FY21 final dividend of 3 cent (S$30mn) and special dividend of 1 cent (S$10mn), HRnet is returning around S$100mn to shareholders this year.
The Negative
- Weak equity market hurt book value. In 1H22 there was a decline of S$12.6mn in financial assets, namely equity shares in listed recruitment companies. There was S$5.7mn loss recognised in the income statement and another S$6.9mn in the balance sheet.
Outlook
Weaker economic conditions in the region may have a dampening effect on volume. In Singapore, we expect the high job vacancy rates and re-opening of borders to drive revenue growth. For instance, there has been a decline in COVID-19 related vaccination roles but replaced but other non-COVID medical needs as foreign tourist and elective procedures return. The sustainability of growth in North Asia can improve if lockdowns ease. Another strength of HRnet is the ability to veer into faster growing segments of the economy. Despite the slower economic growth and lockdown in North Asia in 1H22, revenues expanded 28% YoY in 1H22. HRnet capitalized on the strong demand from semiconductor headcount by local and multinational companies
HRnetGroup Limited – Resilient demand, buy-backs and more regional expansion
- Demand for jobs remains robust in Singapore with record job vacancies.
- The franchise is expanding further regionally with new co-owners in Indonesia, Shenzhen, Hong Kong and Shanghai. HRnet announced on 13 June 22 that it is undertaking a S$30mn share buyback, equivalent to almost six months average daily volume.
- While the barrier to entry in the recruitment industry may be low, we believe the barriers to scale are immense. HRnet possesses a network of more than 700 recruiters across 14 Asian cities. These barriers allow HRnet to maintain an asset-light model with minimal fixed assets of S$1.5mn. The reported return on equity is 16% but arguably much higher. Total attributable equity is S$370mn, almost equivalent to the net cash of S$327mn. In other words, HRnet could return a large chunk of capital to shareholders and still sustain profitability, especially with S$114mn working capital already tied as trade debtors.
- We maintain our BUY recommendation with an unchanged target price of S$1.18. Our valuation is benchmarked to the mid-range of the historical 5-year range, 12x PE FY22e ex-cash. HRnet dividend yield is 5% based on their guided payout of 50% of a recurrent net profit.
Investment Thesis
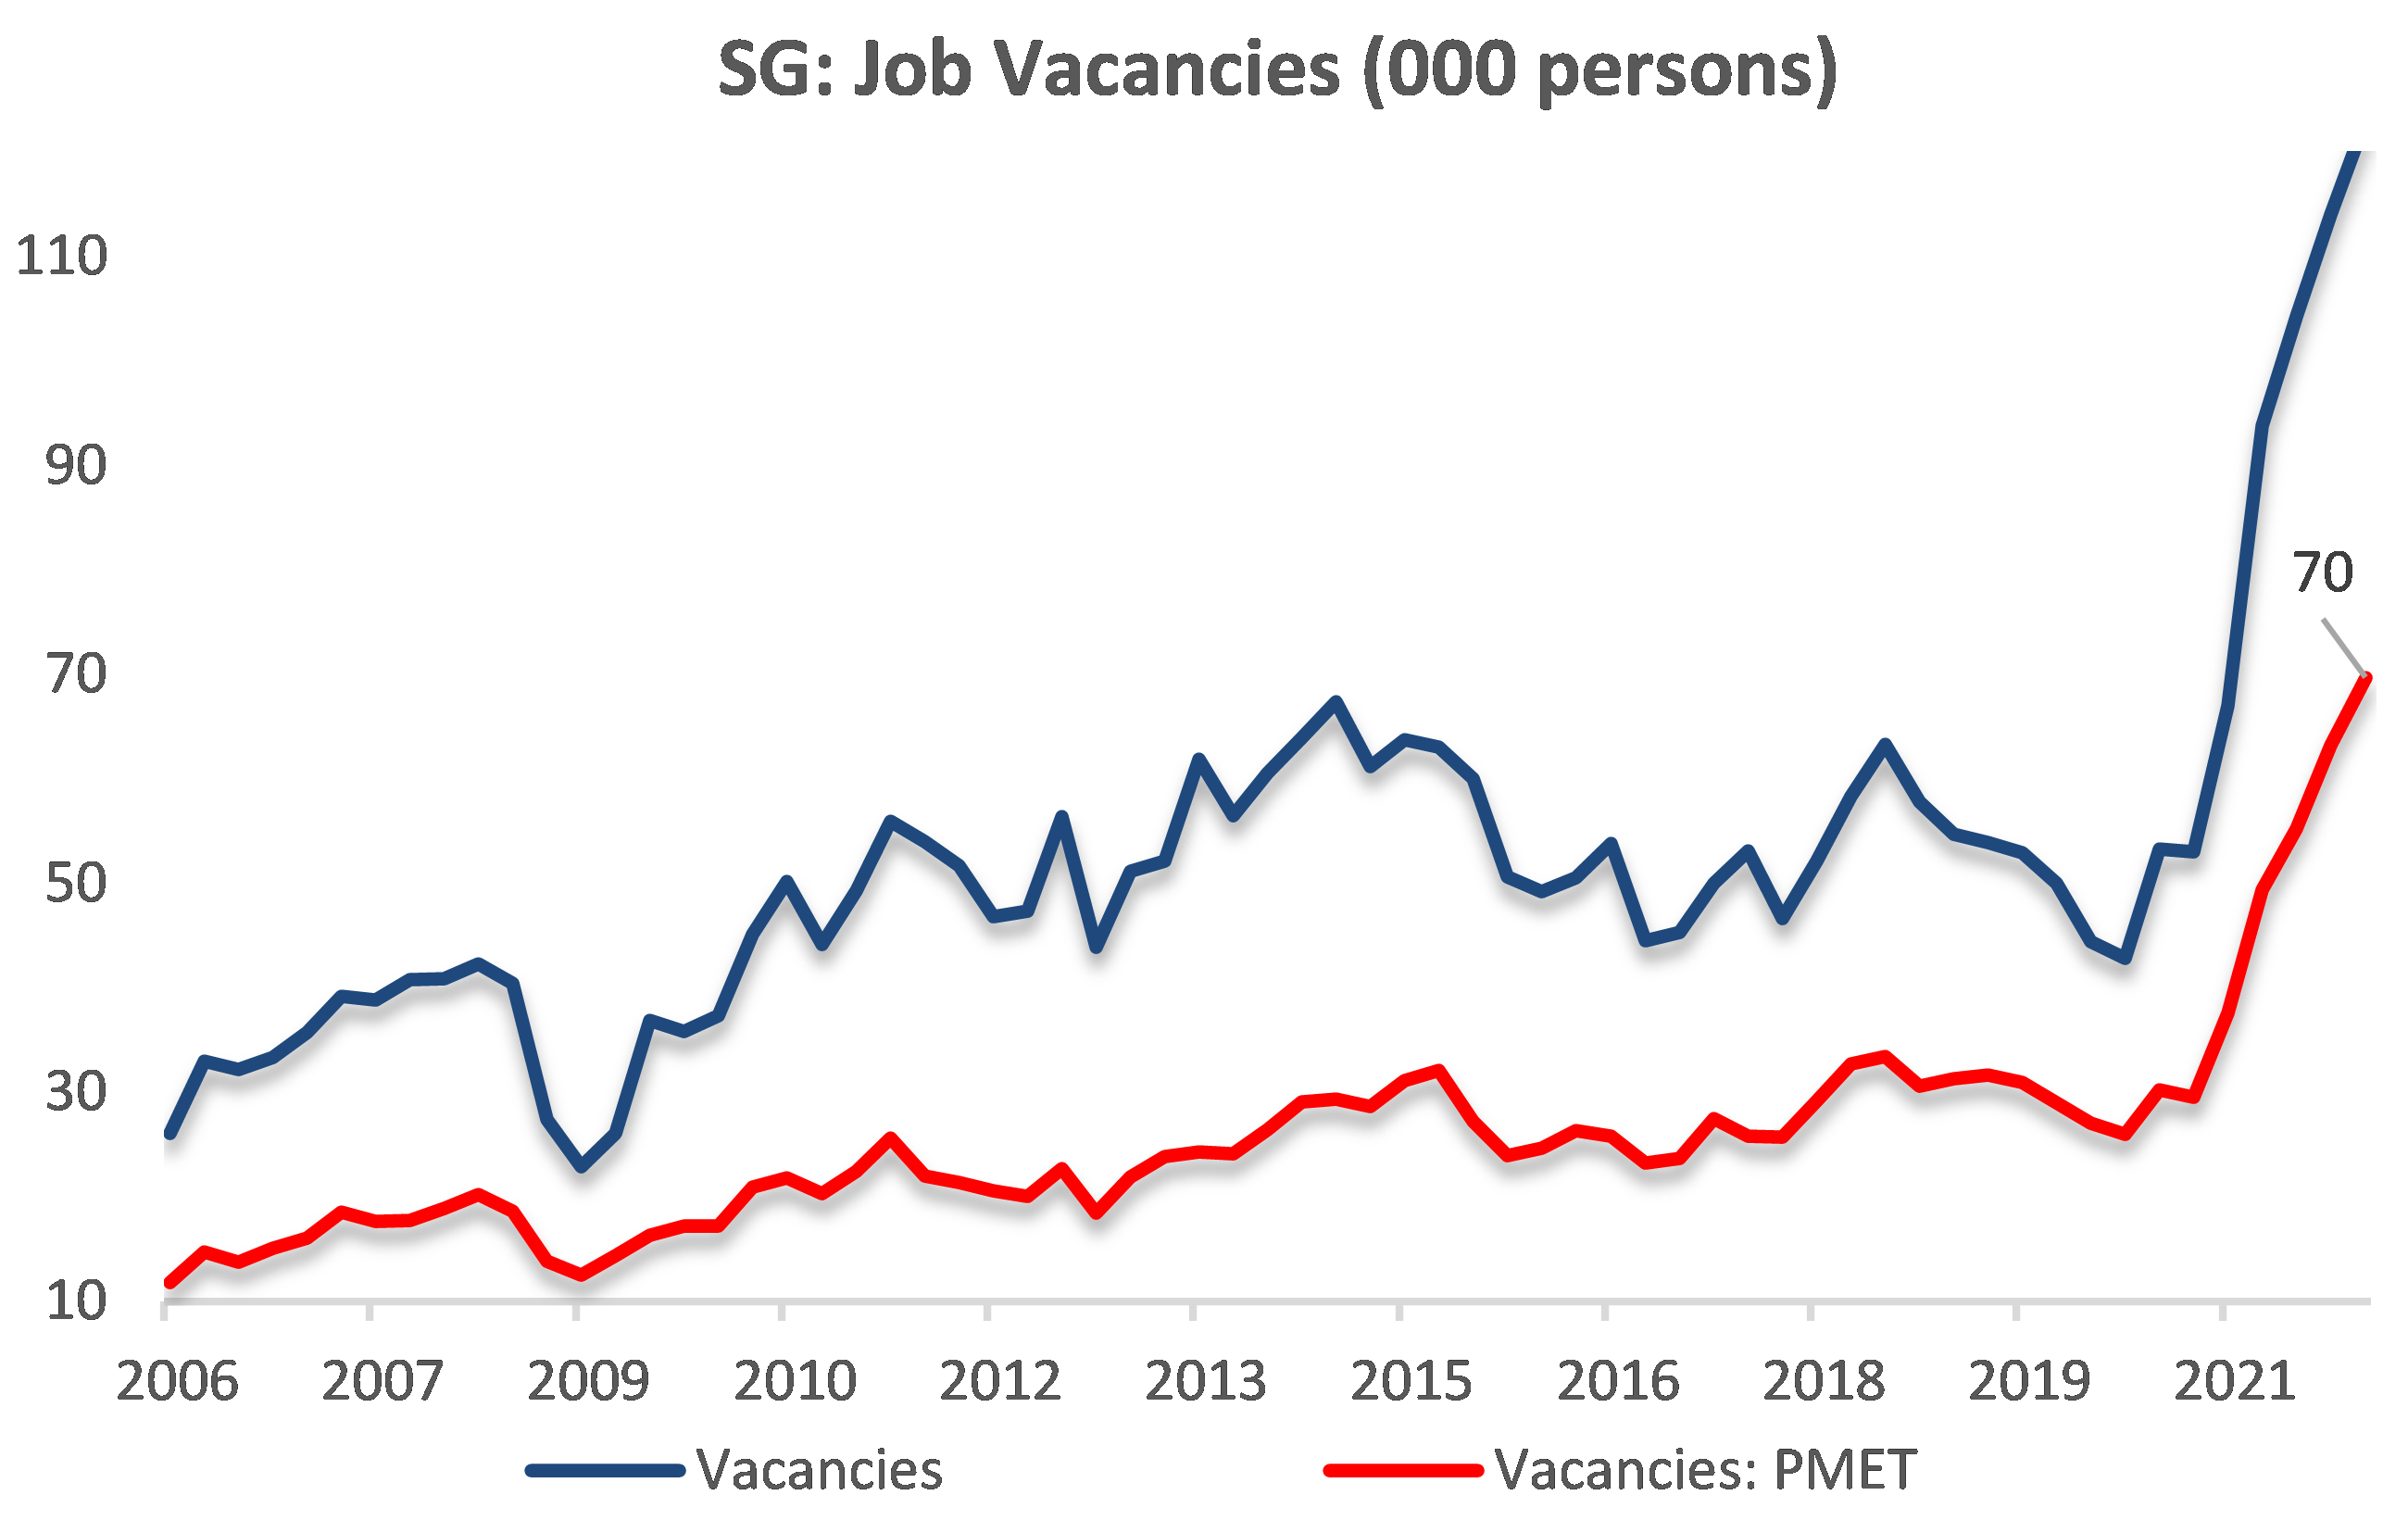
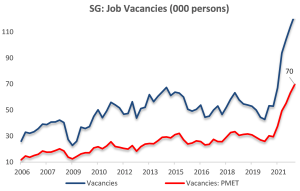
Robust demand for jobs in Singapore. Singapore is experiencing a robust recovery in jobs. In 1Q22, employment rose by 42,000. Employment growth was across all sectors including 17,500 from services. Financial and professional services enjoyed the largest growth in employment in more than a decade. PMET vacancies were the highest on record, at around 70,000. A tight labour market and difficulty in sourcing candidates invariably led to higher reliance on recruitment agencies. Hiring managers have no desire to spend hours interviewing and assessing candidates. It is a waste of a hiring manager’s precious time. Clients want recruiters to identify the best one or two options for them. The ratio of job vacancies to unemployed persons in 1Q22 was 2.4, the highest since 3Q97.
Figure 1: Surge in vacancies in Singapore
Get access to all the latest market news, reports, technical analysis
by signing up for a free account today!
Login
The full article is only available for premium content subscribers. To continue reading this article, please log in:
Not a Premium Content Subscriber yet? Sign up here!
- Home >
- Phillip Research Report