Frasers Centrepoint Trust – Record FY26 DPU, AEIs to drive growth
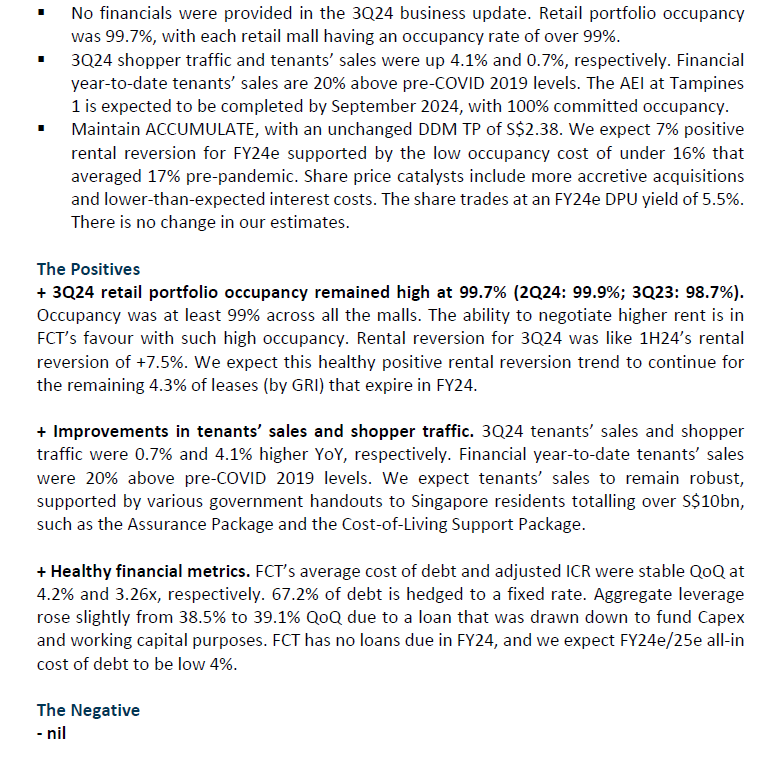
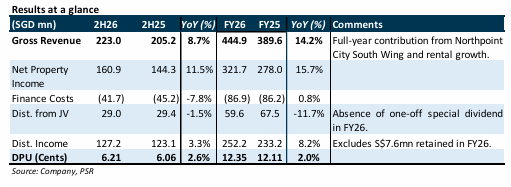
- 2H26/FY26 DPU of 6.21/12.35 Singapore cents was 2.6%/2% higher YoY, in line with our estimates and forming 50%/99% of our FY26e forecast, despite S$7.6mn in distributable income retention in FY26. 2H26/FY26 NPI grew 12%/16% YoY, driven by the full-year contribution from Northpoint City South Wing following its acquisition in May 2025 and organic rental growth.
- FY26 rental reversions remained healthy at +6.6% (FY25: +7.8%), with committed occupancy across the retail portfolio at 99.7%. Shopper traffic grew 1.8% while tenants’ sales increased 1.3%, with occupancy cost remaining stable at 16.3%, providing room for further rental growth. The AEI at Hougang Mall has been completed, achieving a c.8% ROI, above target, and adding >13k sqft of NLA across prime retail floors.
- Maintain BUY with a lower TP of S$2.50 (prev. S$2.70) as we roll forward our forecasts. We trim our FY27e DPU estimate by 4% to 12.37 cents to reflect the impact of major AEIs and raise our cost of equity assumption by 25bps to reflect the higher interest rate environment. Longer-term DPU growth drivers include AEI completions and sustained mid-single-digit positive rental reversions. We expect FCT to maintain broadly stable DPU in FY27e despite upcoming AEIs, supported by the distribution of S$7.6mn in DI retained in FY26 and a higher proportion of management fees paid in units (FY26: 54%). FCT trades at a forward FY27e distribution yield of 5.7%.
The Positives
+ Healthy financial position. Aggregate leverage improved 1.7 ppts QoQ to 38.7% and is
expected to decline further to 36.8% following repayment of higher-cost debt using proceeds
from the White Sands divestment. 4Q26 average all-in cost of debt was 3.1% (3Q26: 3.0%;
4Q25: 3.5%), bringing FY26 cost of debt to 3.2% (FY25: 3.8%). The proportion of fixed-rate
debt is expected to increase from 68.6% to 75.9% following the debt repayment. FCT has no
refinancing requirements in FY27, and we expect FY27e all-in cost of debt to inch up to c.3.3%
amid a gradual increase in base rates.
+ Increase in portfolio valuation. NAV rose 4% YoY to S$2.32, supported by S$66mn in fair
value gains from investment properties. Including FCT’s 50% share of NEX and Waterway
Point, portfolio valuations increased 1.7% YoY, reflecting stronger asset performance and
AEI uplift, with cap rates remaining unchanged.
Frasers Centrepoint Trust – Recycling capital into future growth
- No financials were provided in this 3Q26 business update. Retail portfolio occupancy declined marginally by 20bps QoQ to 99.6% due to tenant churn as FCT optimised its tenant mix. Shopper traffic increased by 2.4% YoY, while tenants’ sales grew a modest 0.2% YoY, reflecting the impact of tenancy churn and ongoing tenant refresh initiatives.
- FCT will divest its smallest mall, White Sands, for S$467mn, representing an 8.4% premium to valuation and a 4.6% exit yield. In addition, FCT will hold a 50% stake in the retail component of the Bayshore Drive integrated development (comprising ~170,000 sqft of retail NLA costing S$613mn on a 100% basis). The project is expected to deliver a 5% yield on cost and is scheduled for completion by end-2030. We estimate it could increase DI by c.3% upon stabilisation.
- Maintain BUY with an unchanged TP of S$2.70 and no changes to our forecasts. We expect FY26e rental reversions to remain healthy at +5%, supported by limited new retail supply and resilient tenant demand. FCT remains our top pick in the retail sub-sector, underpinned by its defensive suburban mall portfolio anchored by essential services, which should continue to perform well amid global uncertainties. Organic growth is expected to be driven by completed AEIs, supporting higher asset yields and sustainable long-term income growth. FCT's maiden Bayshore retail development adds a new long-term growth driver. FCT is trading at an attractive forward FY26e dividend yield of 5.5%.
The Positives
+ Operational metrics remain healthy. Portfolio occupancy stayed high at 99.6% in 3Q26,
down 20bps QoQ, excluding Hougang Mall and NEX, which were affected by ongoing AEI.
YTD26, the portfolio has welcomed 69 new-to-portfolio tenants, supporting the continued
enhancement of its tenant mix.
+ Strong financial position with lower cost of debt. The average all-in cost of debt declined
20bps QoQ to 3% in 3Q26 following the expiry of higher-cost interest rate swaps, with 65.7%
of borrowings now hedged to fixed rates. Aggregate leverage stood at 40.4% but is expected
to fall to 36.5% post completion of the White Sands divestment. FCT has no debt maturing
in FY26, with only 4% of borrowings due for refinancing in FY27.
The Negative
- nil
Frasers Centrepoint Trust – Defensive malls weather macro uncertainty
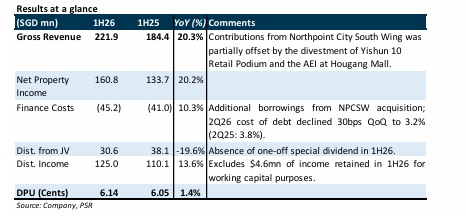
- 1H26 DPU rose 1.4% YoY to 6.14 Singapore cents, in line with expectations and forming 49% of our FY26e forecast. NPI increased 20.2% YoY to S$160.8mn, driven by the acquisition of Northpoint City South Wing (NPCSW) and higher passing rents. This was partly offset by the divestment of Yishun 10 Retail Podium and AEI-related disruption at Hougang Mall. Excluding NPCSW and Hougang Mall, NPI would have grown 2.2% YoY.
- Retail portfolio occupancy improved 1.7 ppts QoQ to 99.8%, driven by the backfilling of cinema spaces at Causeway Point and Century Square. Rental reversions remained healthy at +6.5% in 1H26 (FY25: +7.8%).
- Maintain BUY with a lower TP of S$2.70 (prev. S$2.74) as we trim our FY26e DPU forecast by 1% to account for the partial downtime from the NEX AEI. We expect FY26e rental reversions to remain healthy at +5%, supported by limited new retail supply and resilient tenant demand. FCT remains our top pick in the retail sub-sector, underpinned by its defensive suburban mall portfolio anchored by essential services, which continue to perform well amid global uncertainties. Organic growth should be driven by successful AEI completions, supporting higher asset yields and long-term income growth. FCT is trading at a forward FY26e yield of 5.4%.
The Positives
+ Healthy portfolio operations. Portfolio occupancy improved 1.7 ppts QoQ to 99.8%, driven
by the backfilling of cinema spaces at Causeway Point and Century Square. Golden Village
has also exited Tiong Bahru Plaza as of 29 March, with the space to be taken up by Xventure,
a new indoor sports and adventure park concept. Despite macro uncertainty, shopper traffic
rose 2.4% YoY, and tenants’ sales increased 3.6% YoY in 2Q26, compared with FY25 growth
of 1.6% and 3.7%, respectively, underscoring the resilience of FCT’s portfolio anchored by
essential services.
+ Stable capital and cost management. The average all-in cost of debt improved by 30 bps
QoQ to 3.2% in 2Q26, with 66% of borrowings hedged to fixed rates. Aggregate leverage also
improved slightly to 40% from 40.3% QoQ. Having refinanced all FY26 maturities, the all-in
cost of debt is expected to be around 3.3% for FY26e (FY25: 3.5%). On utilities, FCT is fully
hedged for the remainder of FY26 and partially hedged for FY27, supporting cost stability.
Frasers Centrepoint Trust – Back to 99.9% occupancy
- No financials were provided in the 1Q26 business update. Retail portfolio occupancy was unchanged QoQ at 98.1% but improved to 99.9% post-1Q26 following the backfilling of cinema spaces at Causeway Point and Century Square.
- Phase 1 of the Hougang Mall AEI was successfully completed in November 2025, introducing 33 new-to-Hougang retail concepts. The AEI at NEX is scheduled to commence in 2Q26, adding c.44k sqft of NLA with a targeted 7% ROI. 1Q26 shopper traffic and tenants’ sales remained healthy at +1.3% and +2.7%, respectively (FY25: +1.6% and +3.7%).
- Upgrade to BUY from ACCUMULATE with an unchanged TP of S$2.74 due to the recent share price performance. There is no change to our forecast. We expect FY26e rental reversions to remain healthy at +5%, supported by limited new retail supply and a low occupancy cost of c.16%, below historical averages (pre-COVID: c.17%). FCT remains our top pick in the retail sub-sector, underpinned by its resilient suburban mall portfolio anchored by essential services that continue to perform well even amid consumption slowdowns. Organic growth is expected from successful AEI completions, driving higher asset yields and income growth. FCT is trading at a forward FY26e yield of 5.6%.
The Positives
+ Portfolio occupancy improved to 99.9% post-1Q26 with healthy operating metrics. The
cinema spaces at Causeway Point and Century Square have been successfully backfilled by
SAS Cineplex and Golden Village, respectively. Shopper traffic and tenant sales remained
resilient, increasing by 1.3% and 2.7% in 1Q26, respectively.
+ Stable financial metrics. In 1Q26, the quarter average all-in cost of debt remained stable
at 3.5% QoQ, with 81.2% of borrowings hedged to fixed rates. Aggregate leverage increased
slightly from 39.6% to 40.3% QoQ, reflecting ongoing capex at Hougang Mall. With interest
rates still trending lower, the all-in cost of debt is expected to decline further in FY26e,
potentially reaching 3.3% (FY25: 3.5%).
The Negative
- nil
Frasers Centrepoint Trust – Continued positive rental reversions expected
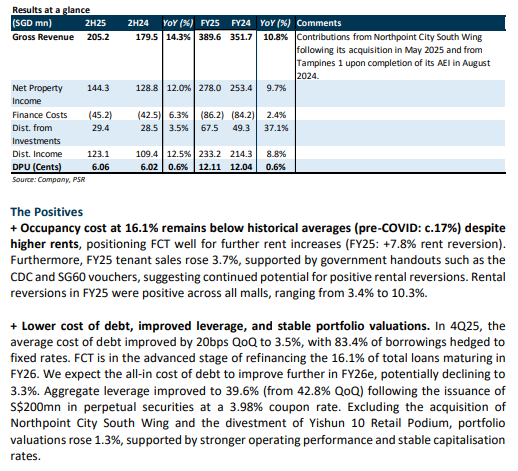
- 2H25/FY25 DPU of 6.06/12.11 Singapore cents was 0.6%/0.6% higher YoY, in line with our estimates and formed 50%/100% of our FY25e forecast. 2H25/FY25 NPI increased 12%/9.7% YoY from the contributions from Northpoint City South Wing following the completion of its acquisition in May 2025, +7.8% positive rental reversions, and Tampines 1 following the completion of its AEI. This was partially offset by a lower occupancy of 98.1% (3Q25: 99.9%) due to the exit of Cathay Cineplexes at Causeway Point and Century Square.
- Excluding Hougang Mall due to its ongoing AEI, 4Q25 shopper traffic and tenants’ sales saw healthy YoY growth at +1.5% and +3.9%, respectively (FY25: +1.6% and +3.7%). The average cost of debt fell 20bps QoQ to 3.5%, down from the 4% peak in 1Q25.
- We maintain ACCUMULATE with a higher TP of S$2.74 (prev. S$2.44). We raise our FY26e DPU forecast by 2% on lower interest rate assumptions and reduce our cost of equity from 6.9% to 6.38% on a lower risk-free rate as we roll forward our forecasts. We expect FY26e rental reversions to remain similar to FY25’s +7.8%, supported by limited new retail supply and a low FY25 occupancy cost of 16.1%, which remains below historical averages. FCT remains our top pick in the retail sub-sector, underpinned by its resilient suburban mall portfolio anchored by essential services that continue to perform well even amid consumption slowdowns. It is trading at a forward FY26e yield of 5.2%.
Frasers Centrepoint Trust – 99.9% retail portfolio occupancy
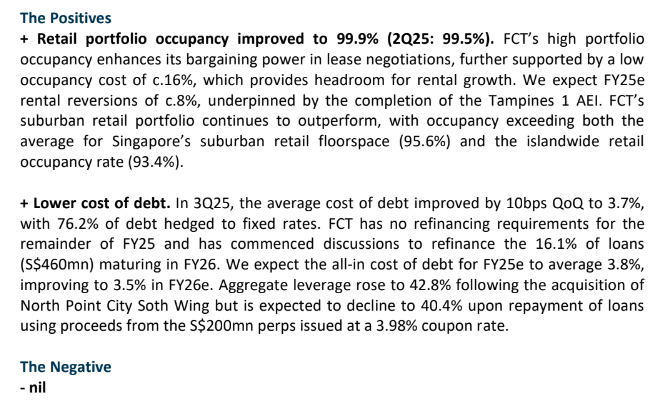
- No financials were provided in this 3Q25 business update. The acquisition of Northpoint City South Wing was completed on 26 May 2025 and will start contributing from 2H25 onwards.
- Retail portfolio occupancy was at 99.9% (2Q25: 99.5%). 3Q25 shopper traffic and tenants’ sales saw healthy YoY growth at +2.1% and +4.4%, respectively (1H25: +1% and +3.3%). The average cost of debt continues to trend down, falling 10bps QoQ and 50bps YoY to 3.7%.
- We maintain ACCUMULATE with an unchanged TP of S$2.44. There are no changes to our estimates. We expect FY25e rental reversions to be similar to FY24’s 7.7%, supported by limited upcoming retail supply and a low occupancy cost of c.16% which remains below historical averages. Trading at a yield of 5.5%, FCT remains our top pick in the retail sub-sector, backed by its resilient suburban mall portfolio anchored by essential services that tend to perform well even in a consumption slowdown.
Frasers Centrepoint Trust – Defensive earnings from suburban malls
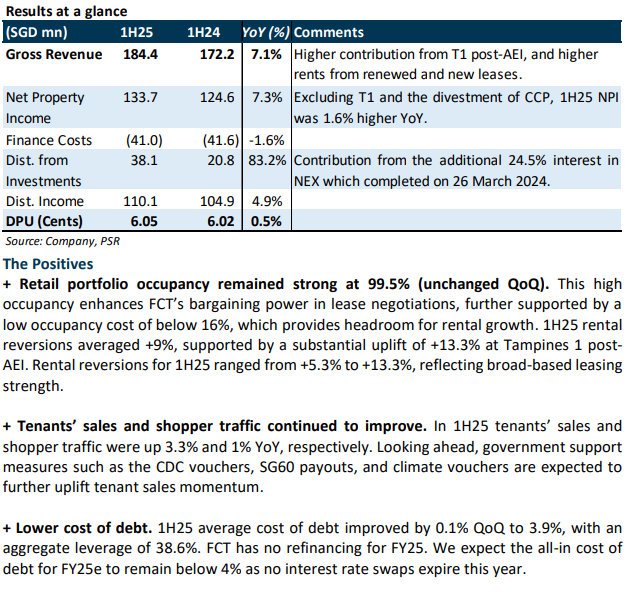
- 1H25 DPU of 6.054 Singapore cents was 0.5% higher YoY, in line with our expectations and formed 49% of our FY25e forecast. NPI grew 7.3%, driven by higher rents at Tampines 1 following AEI completion and stronger rents across the portfolio. Excluding Tampines 1 and the divestment of Changi City Point, 1H25 NPI was up 1.6% YoY.
- Portfolio occupancy remained high at 99.5%. 1H25 shopper traffic and tenants’ sales saw healthy YoY growth at +1% and +3.3%, respectively. Rental reversions were strong at +9% (FY24: +7.7%), supported by a 13.3% rent increase at Tampines 1 following the completion of its AEI. The placement and preferential offering to fund the proposed acquisition of Northpoint City South Wing were 4x and 1.2x oversubscribed, respectively, raising S$421mn.
- We downgrade FCT to ACCUMULATE from BUY with an unchanged TP of S$2.44 following recent share price performance. We trim our FY25e/26e DPU estimates by 1%/3%, factoring in the enlarged unit base from the equity fund raising, a three-month contribution from Northpoint City South Wing in the last quarter of FY25e, and occupancy disruptions at Hougang Mall due to ongoing AEI. We expect a healthy mid-single-digit positive rental reversion in FY25e, supported by limited upcoming retail supply and a low occupancy cost of <16%. The share trades at an FY25e DPU yield of 5.4%. FCT remains relatively resilient in an economic slowdown due to its suburban mall portfolio anchored by essential services.
Frasers Centrepoint Trust – Key metrics remain healthy
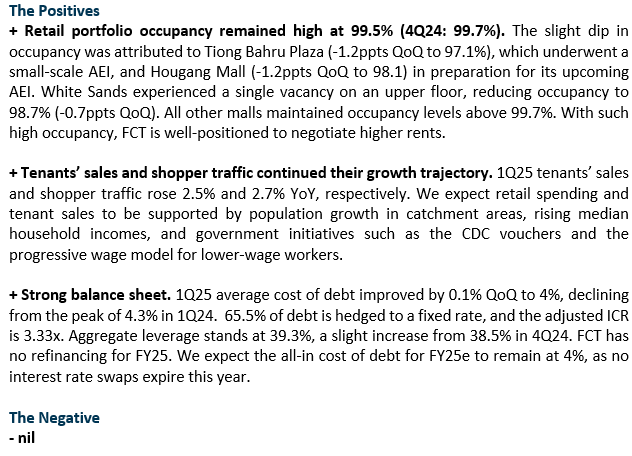
- No financials were provided in the 1Q25 business update. Retail portfolio occupancy remained high at 99.5% (4Q24: 99.7%).
- 1Q25 shopper traffic and tenants’ sales registered healthy YoY growth at +2.7% and +2.5%, respectively. Rental reversions remained strong, similar to FY24’s +7.7%. The AEI at Hougang Mall has achieved c.50% pre-commitment and the Mall continues to operate during the AEI. FCT targets a 7% ROI on a S$51mn Capex for this project.
- Upgrade to BUY with an unchanged TP of S$2.44 due to the recent share price weakness. Our estimates remain unchanged. We expect a healthy c.5% positive rental reversion for FY25e, supported by limited retail supply in the coming years. Share price catalysts include accretive AEIs and the acquisition of Northpoint City South Wing. The share trades at an FY25e DPU yield of 5.8%.
Frasers Centrepoint Trust – Upside from Tampines 1 AEI completion
- 2H24/FY24 DPU of 6.02/12.04 Singapore cents was unchanged/0.9% lower YoY, in line with our expectations and formed 50%/99% of our FY24e forecast. 2H24/FY24 NPI was down 0.6%/4.6% YoY but excluding the divestment of Changi City Point and the lower contribution from Tampines 1 due to its AEI works, NPI was 4.7%/3.4% higher YoY.
- Retail portfolio occupancy remains high at 99.7%. Rental reversions for FY24 were robust at +7.7% (FY23: +4.7%). In FY24, shopper traffic and tenants’ sales were up 4.2% and 1.2% YoY, respectively. Tenants’ sales are now at 20% above pre-COVID 2019 levels. The AEI at Tampines 1 was completed on schedule with a return on investment exceeding the 8% initial target. Portfolio valuation rose 1.2% YoY to S$7bn with unchanged cap rates.
- Maintain ACCUMULATE with a higher DDM TP of S$2.44 (previously S$2.38) as we roll forward our forecasts. We lower our FY25e/26e DPU estimates by 1% to reflect partial downtime at Hougang Mall from the planned AEI. We expect c.5% positive rental reversion for FY25e supported by the low occupancy cost of 16% that averaged 17% pre-pandemic. Share price catalysts include more accretive acquisitions and lower-than-expected interest costs. The share trades at an FY25e DPU yield of 5.4%.


Frasers Centrepoint Trust – Low occupancy cost to drive rental reversion
Get access to all the latest market news, reports, technical analysis
by signing up for a free account today!
Login
The full article is only available for premium content subscribers. To continue reading this article, please log in:
Not a Premium Content Subscriber yet? Sign up here!
- Home >
- Phillip Research Report