City Developments Limited – Strong 1H26 with strategic review catalyst
- 1H26 revenue and PATMI grew 61% and 231% YoY, ahead of expectations and forming 67% and 70% of our FY26e forecasts, respectively. Growth was driven by property development, where revenue/PBT surged 166%/122% on the full recognition of the fully sold Lumina Grand EC, alongside contributions from well-sold projects, including Newport Residences (launched in Jan 26) and Norwood Grand. 1H26 interim dividend doubled YoY to 6 cents/share.
- Hotel operations turned around from a pre-tax loss of S$84.4mn in 1H25 to a pre-tax profit of S$42mn, driven by higher revenue (+6.4% YoY), supported by a 4.9% YoY increase in global RevPAR, acquisition of Holiday Inn London - Kensington High Street, and net exchange gains of S$38mn in 1H26 versus a S$63mn loss in 1H25.
- Maintain BUY with an unchanged RNAV target price of S$11.32, representing a 25% discount to our RNAV of S$15.09. Our FY26e forecasts are unchanged despite the strong 1H26 earnings beat, as 1H26 benefited from the full recognition of Lumina Grand. The strategic review, to be announced by end-September, should provide greater clarity on the future strategic direction, capital allocation framework, and implementation roadmap. We see re-rating potential from an accelerated pace of asset recycling and deleveraging, as well as expanding its fund management business to grow recurring income alongside its development exposure.

The Positive
+ Property development delivered strong growth; robust launch pipeline ahead. In 1H26,
the Group and its JV associates sold 352 units worth S$892mn, anchored by the launch
of the ultra-luxury Newport Residences on Anson Road (83% sold). Other projects,
including The Orie, The Myst, Zyon Grand and Norwood Grand, also sold more than 90%.
The Group acquired two prime GLS sites at Tanjong Rhu Road and Peck Hay Road in 1H26,
bringing its launch pipeline to around 2,200 units across five projects.
The Negative
- Increase in net gearing. Net gearing increased from 71% in FY25 to 75%, mainly due to
payments for the Tanjong Rhu and Peck Hay Road GLS sites. The strategic review should
provide greater clarity on the roadmap to reduce net gearing towards its medium-term
target of 60%, with further divestments likely. The cost of borrowing declined from 3.7%
in FY25 to 3.4% in 1H26.
City Developments Limited – Strong start to the year
§ No financial information was provided in this operational update. The ultra-luxury freehold Newport Residences, launched in January 2026, is 78% sold to date (57% sold on launch weekend), while other projects, including The Orie, The Myst, Zyon Grand, and Norwood Grand, continue to see strong sales momentum.
§ Hotel operations remained strong despite geopolitical tensions, with RevPAR increasing 4.3% YoY to S$144.8. Separately, all 27 strata units previously held by the Group at Fortune Centre in Singapore have been fully sold.
§ Maintain BUY with an unchanged RNAV target price of S$11.32, representing a 25% discount to our RNAV of S$15.09. We expect strong residential sales from the Group’s upcoming Singapore launches (1,302 units), supported by resilient demand. We also expect further asset divestments, including a potential exit from its legacy UK portfolio, as part of ongoing portfolio optimisation. An outcome of the strategic review is expected in the coming months and may include fund management initiatives to recycle non-core assets into private funds, thereby enhancing capital efficiency and unlocking embedded asset value.

City Developments Limited – Unlocking value through faster recycling
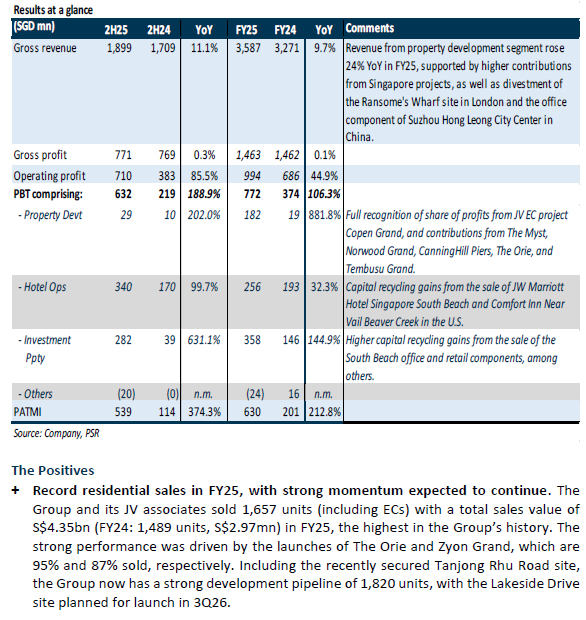
-FY25 PATMI of S$630mn (+213% YoY) exceeded our expectations, coming in at 88% above our FY25e estimate. Growth was driven by strong Singapore residential sales and substantial capital recycling gains, with c.S$2bn in divestments in FY25, including the sale of its 50.1% stake in South Beach.
- The dividend policy has been revised to a minimum of 35% of reported PATMI (previously unspecified), which would include gains from divestments. A final dividend of 25 cents per share has been declared, bringing total FY25 dividends to 28 cents per share, representing a 40% payout.
- Maintain BUY with a higher RNAV TP of S$11.32 (prev. S$9.62), implying a 25% discount to our RNAV of S$15.09. We raise our RNAV by 17% after accounting for recent investments/divestments and higher valuation of the living sector portfolio. Strong residential sales momentum in Singapore is expected to continue into FY26. We also expect more asset divestments, with immediate plans to exit its legacy UK portfolio (c.S$800mn carrying value, comprising development sites and residential projects). A strategic review is ongoing, with an update expected by mid-2026. Fund management initiatives could involve recycling non-core assets into private funds.
City Developments Limited – Divestment momentum continues
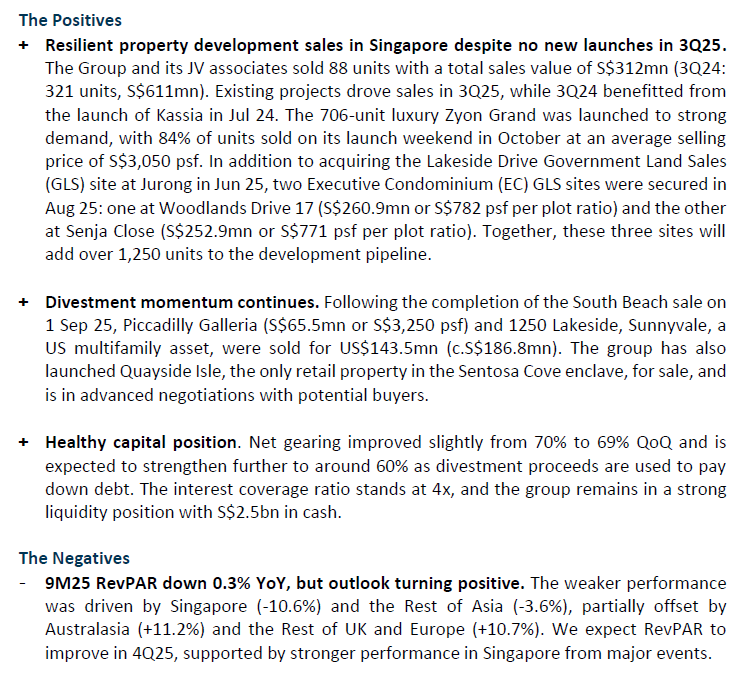
- No financials were provided for the 3Q25 operational update. Asset divestments remain a key focus, with momentum continuing following the completion of the South Beach sale on 1 Sep 2025, followed by the sales of Piccadilly Galleria (S$65.5mn or S$3,250 psf) and 1250 Lakeside, Sunnyvale, a US multifamily asset, for US$143.5mn (c.S$186.8mn).
- Under property development, sales were supported by existing projects as there were no new launches in Singapore in 3Q25. For 9M25, the hotel segment recorded a slight 0.3% YoY decline in RevPAR, mainly due to softer performance in Asia, particularly in Singapore (RevPAR down 10.6%), reflecting the high base in 2024 and the shift of the F1 Singapore Grand Prix from 3Q24 to 4Q25.
- Downgrade from BUY to ACCUMULATE with an unchanged RNAV TP of S$8.34 due to the recent share price performance, representing a 35% discount to our RNAV of S$12.82. There is no change to our forecasts. Strong take-up rates at launched projects, together with the accelerated pace of capital recycling and divestments, may help narrow the RNAV discount. A recovery in Singapore’s hospitality segment is expected in 4Q25, supported by significant events such as the F1 Singapore Grand Prix and the Blackpink concert. A special dividend at FY25 results is likely, fuelled by divestment proceeds.
City Developments Limited – All aboard the divestment train
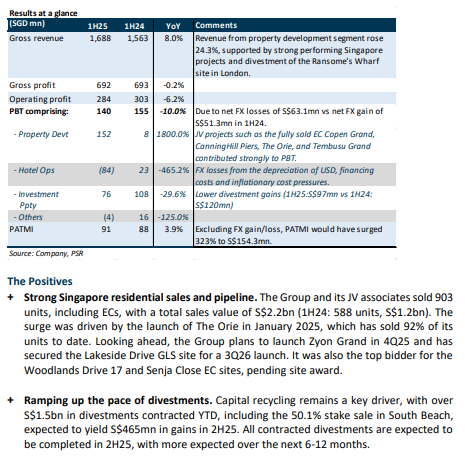
- 1H25 PATMI rose 3.9% YoY to S$91mn, but came in below expectations at 33% of our FY25e forecast, weighed down by a S$63.1mn unrealised net FX loss from USD depreciation. Excluding FX effects, PATMI would have jumped 323% YoY to S$154.3mn.
- Over S$1.5bn of divestments have been contracted YTD, including the sale of a 50.1% stake in the hotel, office, and retail components of South Beach, which is expected to generate a gain of S$465mn upon completion in 2H25. In 1H25, property development was the standout, with PBT surging 1800% YoY to S$152mn, underpinned by strong Singapore residential sales and the full profit recognition of Copen Grand EC.
- Maintain BUY with a higher RNAV TP of S$8.34 (prev. S$6.02), representing a 35% (prev. 45%) discount to our RNAV of S$12.82. We raise our FY25e PATMI by 20% to account for the announced divestments that are expected to be completed in 2H25, including South Beach, partially offset by FX losses and higher interest expenses. Strong take-up rates of launched projects, together with the accelerated pace of capital recycling/divestments, may help narrow the RNAV discount. CDL declared a special interim dividend of 3 cents, with potential for a special dividend at FY25 results, fueled by divestment proceeds.
City Developments Limited – Strong residential sales in Singapore
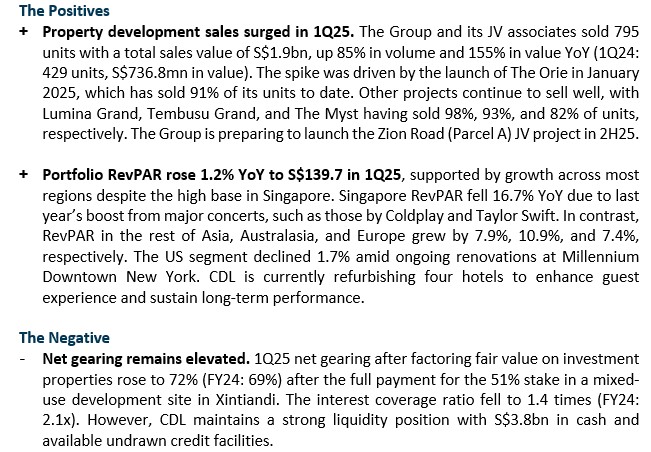
- No financial information was provided in this operational update. The Orie, launched in January 2025, has seen strong demand with 91% of its 777 units sold to date. Other projects continue to sell well, with Lumina Grand, Tembusu Grand, and The Myst 98%, 93%, and 82% sold to date, respectively.
- On 13 May, CDL launched an off-market equal access scheme to repurchase up to 26.8mn preference shares (10% of outstanding) at S$0.78 per share. This follows a similar buyback completed in May 2024, which was oversubscribed by four times the maximum allowable amount.
- Maintain BUY with an unchanged RNAV TP of S$6.02, representing a 45% discount to our RNAV of S$10.95. Our estimates remain unchanged. We believe establishing a fund management franchise, strengthening recurring income streams, and strong take-up rates of launched projects are key earnings drivers for CDL, potentially supporting its share price recovery. In addition, continued asset monetisation and the completion of development projects could help narrow the discount to RNAV.
City Developments Limited – Road to recovery
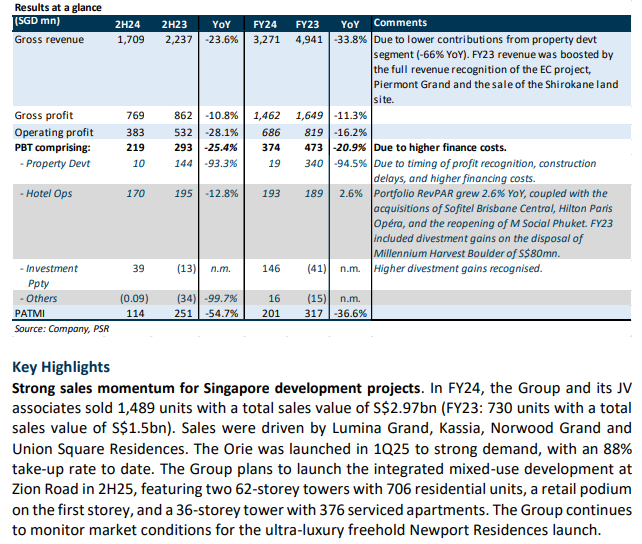
- FY24 PATMI of S$201mn (-36.6% YoY) was below our expectations, forming 70% of our FY24e forecast. This was due to the timing of profit recognition under the property development segment and a 21% rise in interest expenses. FY24 revenue fell 34% YoY due to lower contributions from property development as FY23 included the full recognition of the EC project, Piermont Grand, and the sale of the Shirokane land site.
- The Orie, launched in 1H25, had a take-up rate of 88% at an average selling price of S$2,704. Other launched projects in 2024 continue to sell well, with Norwood Grand, Kassia, and Lumina Grand having sold 84%, 71%, and 89% of units, respectively. CDL missed its S$1bn divestment target for FY24, achieving just over S$600mn in divestments in Singapore, Suzhou and London.
- Maintain BUY with a lower RNAV TP of S$6.02 (previous S$6.87), representing a 45% discount to our RNAV of S$10.95. We lower our FY25e PATMI by 38% to factor in higher interest costs and construction delays. We believe asset monetisation, unlocking value through AEIs and redevelopments, establishing a fund management franchise, strengthening recurring income streams, and strong take-up rates of launched projects are key earnings drivers for CDL, potentially supporting its share price recovery. A final dividend of 8 cents was declared, bringing FY24 DPS to 10 cents or a dividend yield of 2%.
City Developments Limited – Improving residential demand
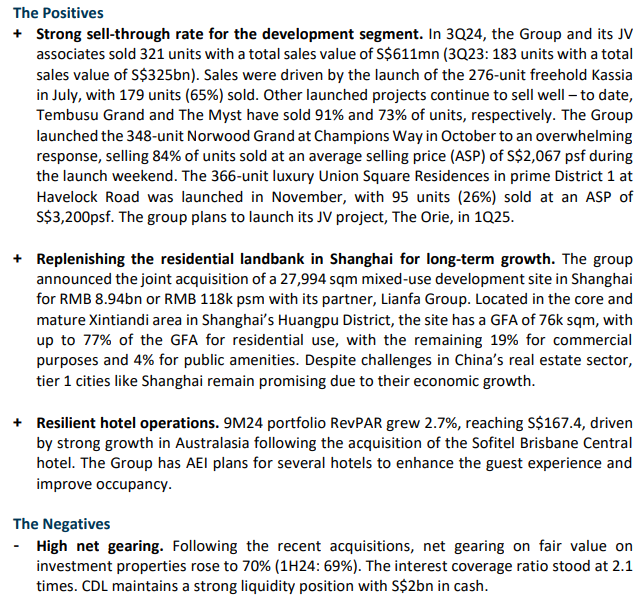
- No financials were provided for the 3Q24 operational update. The net gearing ratio stood at 70%, following several acquisitions, including the Hilton Paris Opéra hotel and four Japan PRS properties.
- Strong sell-through rate for new launches—Kassia, launched in July, and Norwood Grand, launched in October, have sold 65% and 84% of units, respectively. Other projects continue to sell well, with Tembusu Grand and The Myst having sold 91% and 73% respectively.
- Maintain BUY with an unchanged TP of S$6.87, representing a 45% discount to our RNAV of S$12.50. There is no change to our estimates. We believe asset monetisation, unlocking value through AEIs and redevelopments, establishing a fund management franchise, and the continuous recovery in the hospitality portfolio are potential catalysts for CDL, which could help drive the share price recovery.
City Developments Limited – Accelerating capital recycling efforts
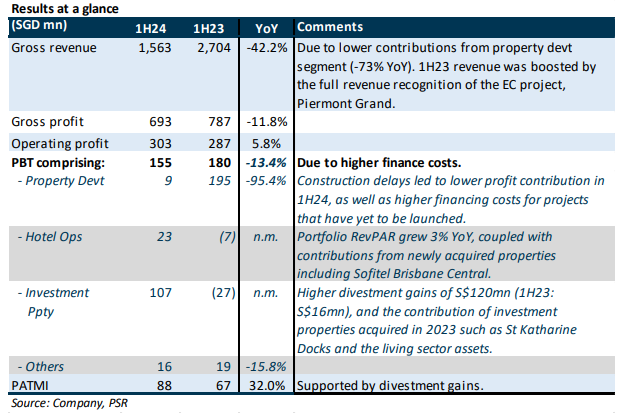
- 1H24 PATMI of S$87.8mn (+32% YoY) was below expectations, forming 31% of our FY24e forecast. The shortfall was due to construction delays, which pushed back the timing of profit recognition of property development projects. The increase in PATMI YoY was driven by higher divestment gains as part of CDL’s capital recycling efforts.
- Year-to-date, CDL has achieved c.S$271mn in divestments, short of management’s S$1bn target for FY24e. Divestments for FY24e are likely to range between S$400mn and S$500mn, unless the larger assets in the UK are sold, which could bring the total closer to the S$1bn target.
- Maintain BUY with an unchanged TP of S$6.87, representing a 45% discount to our RNAV of S$12.50. There is no change to our estimates. CDL’s share price has underperformed since its deletion from the MSCI Singapore Index on 31 May. We believe asset monetisation, unlocking value through AEIs and redevelopments, establishing a fund management franchise, and the continuous recovery in the hospitality portfolio are potential catalysts for CDL, which could help drive the share price recovery.
The Positives
+ Resilient sales under the property development segment. In 1H24, the Group and its JV associates sold 588 units with a total sales value of S$1.2bn (1H23: 508 units with a total sales value of S$1.1bn). Sales were driven by the launch of Lumina Grand, with 399 units
(78%) sold to date. The group plans to launch two projects in 2H24 - Union Square Residences (366 units) and Norwood Grand (348 units). To replenish its development landbank, CDL and its JV partner acquired a GLS site at Zion Road for S$1.1bn or S$1,202 psf ppr in April 2024. Additionally, CDL has submitted two joint bids for the Jurong Lake District (JLD) master developer site with four other partners.
+ Hospitality segment continues to improve, albeit with slower growth. 1H24 portfolio RevPAR increased by 3% YoY to S$156, driven by strong growth in Australasia, where RevPAR surged 30% following the acquisition of the Sofitel Brisbane Central hotel. Occupancy continued its upward trajectory, improving by 1.9%pts, while the average room rate increased slightly by 0.1% YoY to $217.1. All markets experienced RevPAR growth YoY, except for London (-2.4%) and Regional US (-0.5%). Portfolio RevPAR growth is expected to remain at similar levels in 2H24, with its Europe portfolio benefitting from the Paris 2024 Olympics.
The Negatives
- Higher gearing. Following the recent acquisitions (1H24: S$1.1bn in acquisitions and investments) and the share buyback of CDL’s ordinary shares and preference shares, net gearing on fair value on investment properties rose to 69% (1Q24: 63%). The interest coverage ratio fell to 2x in 1H24 from 2.8x in FY23. 40% of debt is at a fixed rate and the average cost of debt is expected to increase to c.4.8% for FY24e (1H24: 4.5%) as some loans get refinanced. Nevertheless, CDL maintains a strong liquidity position with S$1.7bn in cash. CDL aims to bring gearing down to below 60% by 2025.
- Behind on its S$1bn divestment target for 2024. Year-to-date, CDL has divested c.S$271mn of assets, primarily strata units in Singapore. Management is currently engaged in discussions to divest certain large assets but will not proceed with divestments at undervalued prices merely to comple the transaction. Cautious buying sentiment persists in the market, making divestments challenging.
City Developments Limited – Buying back shares
- No financials were provided in this operational update. The launch of Lumina Grand was well received, with 381 units (74%) sold to date. Hotel operations continue to improve, with portfolio RevPAR growing 5.3% YoY to S$139.4.
- Bought back 13mn shares (1.4% of issued shares) since 8 March 2024 for a total consideration of S$76.4mn. In April 2024, CDL announced an off-market equal access scheme to buy back up to 30mn preference shares (10% of total) at an offer price of $0.78.
- Maintain BUY with an unchanged TP of S$6.87, a 45% discount to RNAV of S$12.50. We view CDL as a proxy for the Singapore residential market and hospitality recovery. Asset monetisation, unlocking value through AEIs and redevelopments, establishing a fund management franchise, and the continuous recovery in the hospitality portfolio are potential catalysts for CDL, which could help narrow the discount between CDL’s share price and RNAV.
The Positives
- Strong sales under the property development segment. In 1Q24, the Group and its JV associates sold 429 units with a total sales value of S$737mn (1Q23: 88 units with a total sales value of S$213mn). Sales were driven by the launch of Lumina Grand, with 381 units (74%) sold to date. Tembusu Grand and The Myst continued to sell well, with 62% (4Q23: 60%) of its 638 units and 59% (4Q23: 51%) of its 408 units sold to date, respectively. The group plans to launch two projects in 2H24 - Union Square Residences (366 units) and a project at Champions Way (348 units). To replenish its development landbank, CDL secured a 164,451 sq ft GLS site with JV partner Mitsui Fudosan (Asia) Pte. Ltd. in April 24, for S$1.1bn or S$1,202 psf ppr. Located along Zion Road, this site is directly connected to Havelock MRT station. The plan is to develop the site into an integrated mixed-use project comprising two blocks (69 and 64 stories) with 740 residential units and a retail podium.
- Initiated share buyback programme. On 8 March 24, CDL initiated a share buyback programme for its ordinary shares, and since then, a total of 12.9mn shares (1.43% of issued shares) have been bought back for a total consideration of S$76.4mn. The ordinary shares will be held as treasury shares and may be used for CDL’s long-term incentive plans. In April, CDL announced an off-market equal access scheme to buy back up to 29mn preference shares (10% of total preference shares in issue) at the offer price of $0.78 in cash. The low trading volume of preference shares gives preference shareholders an exit opportunity to partially monetise their holdings. All preference shares acquired by the company pursuant to the off-market equal access offer will be cancelled.
- Hospitality segment continues to improve. 1Q24 portfolio RevPAR rose 5.3% YoY to S$139.4, due to strong growth in Australasia and Singapore. With higher room rates (+0.7% YoY), occupancy (+3.1%pts), and cost optimisation, 1Q24 GOP margins improved 1.7% points YoY to 26.7%. CDL will be refurbishing several hotels in FY24, and they include 1) Millennium Hotel London Knightsbridge, 2) M Social Phuket, 3) Millennium Downtown New York, and 4) The M Social Hotel Sunnyvale in California for a total cost of S$278mn. Additionally, CDL acquired the 268-room Hilton Paris Opera Hotel for €240mn (S$350mn) in May 24. This acquisition complements its expansion plans in Europe ahead of the upcoming Paris 2024 Olympics.
The Negatives
- Higher gearing and lower interest cover. Net gearing on fair value on investment properties inched up to 63% (FY23: 61%). The interest coverage ratio fell to 1.2x in 1Q24 from 2.8x in FY23. Nevertheless, CDL maintains a strong liquidity position with S$2.4bn in cash.
Outlook
CDL is targeting S$1bn in divestments in 2024 to recycle capital, and successful divestments could translate into significant divestment gains as it carries assets at cost in its books - some of which have been held at book value for several decades. The property cooling measures introduced in 2023 continue to stifle demand – foreign buyers have disappeared since the ABSD hike to 60%. The hospitality segment should continue to improve on the back of mega-concerts and MICE events in Singapore, as well as the upcoming Paris 2024 Olympics.
Maintain BUY with an unchanged RNAV TP of S$6.87
We view CDL as a proxy for the Singapore residential market and hospitality recovery. CDL is trading at an attractive 53% discount to our RNAV/share of S$12.50.
Get access to all the latest market news, reports, technical analysis
by signing up for a free account today!
Login
The full article is only available for premium content subscribers. To continue reading this article, please log in:
Not a Premium Content Subscriber yet? Sign up here!
- Home >
- Phillip Research Report