Apple Inc. – Strong demand, yet too many headwinds in the near term
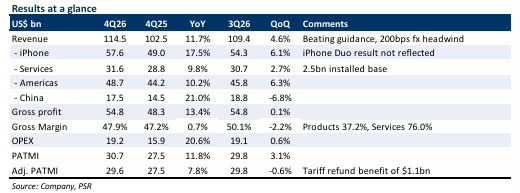
· 4Q26 revenue was within our expectations, while PATMI outperformed due to a US$1.1bn tariff refund benefit and a favourable product mix. Revenue grew 12% YoY, with growth in iPhone (+18% YoY) and MacBook (+24% YoY). FY26 revenue/PATMI were 100%/104% of our FY26e forecasts.
· Strong demand for iPhone 17 and MacBook continues, with demand exceeding supply. Management guided 1Q27 revenue growth of 7–10% YoY, weighed by slowing Services growth and FX headwinds. Memory prices continue to increase, a meaningful headwind going forward.
· We roll over another year of valuations and maintain our recommendation of REDUCE, with a raised DCF target price of US$310 (prev. US$300). Our assumptions remain unchanged, with a WACC of 6.5% and a terminal growth rate of 3.5%. There is still no obvious sign of AI driving product upgrades. Softening service growth, elevated memory costs, and regulatory hurdles are all near-term headwinds for AAPL. With inflated valuation (FY27e forward P/E of 36x VS historical 10 year P/E of 31x), we remain cautious
The Positives
+ Strong iPhone and Mac cycle. 4Q26 iPhone revenue grew 17% YoY. Notably, the higher
priced iPhone 18 Pro and Pro Max were only available for nine days during the quarter, while
iPhone Duo was not included in the quarter at all, suggesting that the majority of the growth
is supported by resilient demand for the iPhone 17 lineup near the end of its run, which is
usually when sales slow down as people hold out for the new model. Mac revenue also surged
24% YoY, despite price increases. Growth was supported by strong demand for both the
affordable MacBook Neo and premium MacBook Pro, a promising sign that AAPL can charge
loyal buyers more with premium products while bringing in new customers through entry
level offerings.
Apple Inc. – Exciting new foldable, but outlook remains complicated
AAPL hosted its “Surprise and Shine” launch event on 9 September, one of the most significant hardware launches in recent years, headlined by the iPhone Duo, AAPL’s first foldable smartphone. Alongside the Duo, AAPL introduced the iPhone 18 Pro and Pro Max, Apple Watch Series 12 and Ultra 4, and AirPods 5.
- iPhone Duo starts at US$1,999, establishing an entirely new price tier above the Pro Max, while the iPhone 18 Pro and Pro Max received a US$100 price increase, starting at US$1,199 and US$1,299. This should provide further support to iPhone ASPs.
- We expect the new lineup to generate strong initial demand, particularly for the iPhone Duo due to its novelty. However, the sustainability of demand at increasingly premium price points remains to be tested. Meanwhile, AI remains the weaker part of AAPL’s investment story, and execution and adoption will likely determine whether Apple Intelligence becomes a meaningful driver of replacement cycles.
- We maintain our REDUCE recommendation, with an increased DCF target price of US$300 (prev. US$290). We raise our FY27e revenue/PATMI estimates by 1%/2% to reflect higher iPhone ASPs and a stronger product mix following the launch of iPhone Duo and price increases across the Pro lineup. Our WACC of 6.5% and terminal growth of 3.5% remain unchanged. Supply constraints, rising memory costs, and AI regulations weigh on the near term, and so far, no clear evidence of Apple Intelligence meaningfully driving product upgrades.
Apple Inc. – Supply constraints and rising memory weigh on near term
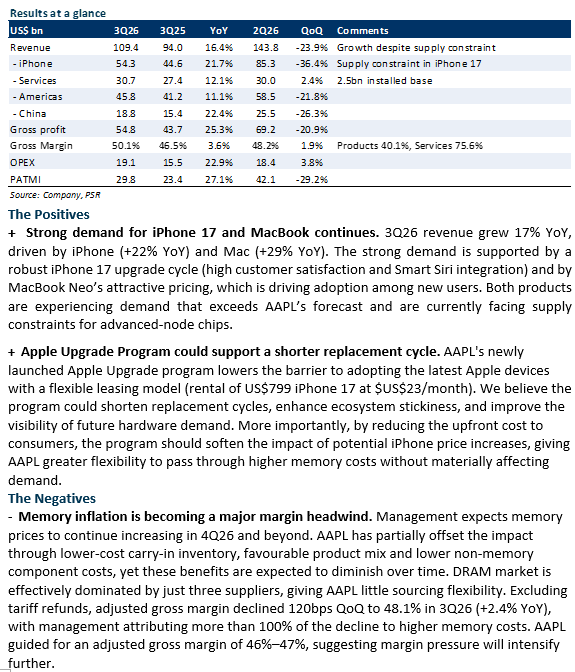
- Both 3Q26 revenue and PATMI are within our expectations. Revenue grew 17% YoY, with strong growth in iPhone (+22% YoY) and MacBook (+29% YoY). 9M26 revenue/PATMI were at 77%/80% of our FY26e forecasts.
- Strong demand for iPhone 17 and MacBook continues, with demand exceeding supply. Management guided 4Q26 revenue growth of 9–11% YoY, weighed by supply constraints and FX headwinds. Memory prices continue to increase, a meaningful headwind going forward.
-
We downgrade our recommendation from NEUTRAL to REDUCE, with an unchanged DCF target price of US$290. We keep our FY26e revenue and PATMI assumption unchanged, with WACC of 6.3% and terminal growth of 3.5%. Supply constraints and rising memory and AI regulations weigh on the near term, and so far, there is no clear evidence that Apple Intelligence is meaningfully driving product upgrades.

Apple Inc. – More visibility into AI strategy
- AAPL held its annual Worldwide Developers Conference (WWDC) on 8 Jun, unveiling updates to Apple Intelligence, an enhanced Siri leveraging Gemini, and broad iOS performance upgrades aimed at improving the user experience across both old and new devices.
- The updates strengthen AAPL’s ecosystem advantage, which could drive a more robust upgrade cycle and improve services revenue potential, all while requiring comparatively modest Capex investment compared to hyperscalers.
- We maintain our NEUTRAL recommendation, with a higher DCF target price of US$290 (prev. US$280). We raise our FY26e revenue and PATMI assumptions by 2% and 1%, respectively, to account for continued iPhone 17 growth. We also lower our beta assumption from 1.00x to 0.95x, reflecting increased confidence in AAPL's long-term competitive positioning and the durability of its ecosystem. Terminal growth of 3.5% remains unchanged. WWDC provided greater visibility into AAPL's AI strategy yet successful execution and broader user adoption will be critical to translating these into sustained earnings growth.
Key announcements
• Siri AI Assistant Enhancements. AAPL introduced Siri AI, a next-generation version
of Siri powered by Apple Intelligence. The enhanced assistant features personal
context understanding, on-screen awareness, visual intelligence, and improved
conversational capabilities, enabling it to better understand user intent and execute
complex tasks across applications. Siri can also leverage information from users'
photos, notes, messages, and other content to provide relevant assistance. It
transforms from a traditional command-based voice assistant into a more capable
and proactive AI-powered digital assistant.
• Apple Intelligence Expansion. AAPL expands Apple Intelligence across its
ecosystem. New capabilities include AI-powered tab organization and page
monitoring in Safari, natural-language event creation in Calendar, context-aware
suggestions in Messages, AI-assisted automation through Shortcuts, and enhanced
image generation and photo editing tools. Apple Intelligence also combines
personal context, world knowledge, and on-screen awareness to deliver more
personalized and contextually relevant experiences.
• Ecosystem and Privacy Strategy. AAPL continued to emphasise its privacy-first AI
strategy. It highlighted its approach of performing AI inference directly on-device
whenever possible, while leveraging Private Cloud Compute only when additional
processing power is required. Apple also positioned Apple Intelligence as a system
wide capability integrated across its installed base rather than a standalone AI
subscription service.
Apple Inc. – Great earnings shadowed by rising memory cost
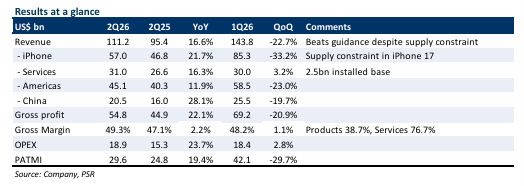
- Both 2Q26 revenue and PATMI exceeded our expectations. Revenue grew 16.6% YoY, the fastest growth in four years, mainly driven by faster-than-expected growth in iPhone (+22% YoY) and the China market (+28% YoY). 2Q26 revenue/PATMI were at 55%/56% of our FY26e forecasts.
- Strong demand for iPhone 17 and MacBook continues, with demand exceeding supply. Management guided 3Q26 revenue growth of 14–17% YoY, supported by continued strength in iPhone and MacBook. However, rising memory costs are expected to intensify in the coming quarters, presenting a longer-term margin headwind.
- We maintain our NEUTRAL recommendation, with a higher DCF target price of US$280 (prev. US$260). We raise our FY26e revenue and PATMI assumptions by 2% and 1%, respectively, to account for stronger-than-expected iPhone 17 growth. WACC of 6.5% and terminal growth of 3.5% remains unchanged. AAPL’s ability to sustain product-led growth while translating its AI investments into meaningful user adoption and monetisation will be key to supporting its valuation.
The Positives
+ Strong iPhone 17 and MacBook momentum expected to carry into next quarter. 2Q26
revenue grew 17% YoY, driven by iPhone (+22% YoY) and Mac (+6% YoY). The strong demand
is supported by a robust iPhone 17 upgrade cycle (high customer satisfaction, new features,
and Apple Intelligence integration) and by MacBook Neo’s attractive pricing, which is driving
new user adoption. Both product lines are currently supply-constrained. iPhone is impacted
by tight advanced-node (3nm-class) SoC capacity (expected to ease in 3Q26), while Mac
constraints are likely to persist for several months. Management guided 3Q26e revenue
growth of 14–17% YoY.
+ Continued shareholder returns support valuation and capital discipline. AAPL announced
an additional US$100bn share repurchase authorization and a 4% dividend increase,
reinforcing its commitment to returning excess cash. This signals confidence in the durability
of cash flows and provides valuation support and downside protection, particularly in a period
of rising costs and elevated investment. Importantly, it also reflects Apple’s disciplined capital
allocation, balancing ongoing reinvestment in AI and product development with consistent
shareholder returns.
Apple Inc. – Booming iPhone 17 VS soaring memory costs
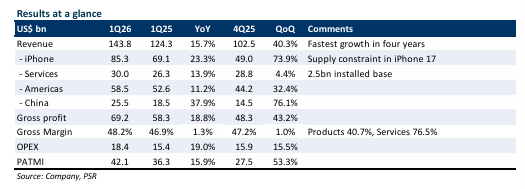
- 1Q26 revenue and PATMI were within our expectations. Revenue grew 16% YoY, fastest growth in four years, mainly driven by growth in iPhone (+23% YoY) and China market (+38% YoY). 1Q26 revenue/PATMI were at 31%/34% of our FY26e forecasts.
- Demand for the iPhone 17 lineup remains strong, with current demand outpacing supply. Management guided 2Q26e revenue growth of 13–16% YoY, supported by continued iPhone sales momentum. Rising memory costs are expected to become more pronounced in the coming quarters, posing a margin headwind in the long run.
- We raise our FY26e revenue and PATMI assumption by 2% and 3%, respectively, to account for the strong growth in iPhone 17. We have also increased our terminal growth rate from 3.0% to 3.5% to reflect the long-term monetization potential from AAPL’s collaboration with Gemini, which strengthens Apple Intelligence and supports sustained ecosystem engagement. We upgrade our recommendation from REDUCE to NEUTRAL, raising the DCF target price to US$260 (prev. US$230). WACC of 6.5% remains unchanged. We remain cautious on AAPL, as the stock is still in a “prove-it” phase, particularly at a ~30.7x forward FY26 P/E. Ultimately, AAPL’s ability to sustain product-led growth and execute a successful Siri rollout will be critical to underpinning its current valuation.
The Positives
+ Strong iPhone 17 cycle continues. AAPL delivered a record quarter, with total revenue of
US$143.8bn (+16% YoY), driven by iPhone revenue of US$85.3bn (+23% YoY), an all-time high
for the product. Demand remains strong, leaving AAPL with very lean channel inventory and
a constrained supply (mainly due to constrained advanced-node (3nm-class) SoC capacity).
The strength of the cycle is broad-based, supported by record upgraders across geographies
and double-digit growth in switchers. AAPL expects iPhone-led momentum to continue and
guided 2Q26E revenue growth of 13–16% YoY. We see the iPhone 17 cycle as durable. The
upcoming Siri rollout (supported by AAPL’s collaboration with Google Gemini) will further
reinforce the upgrade narrative and provide additional upside. We forecast iPhone sales +14%
YoY in FY26.
+ China market rebound a pleasant surprise. China revenue +37.9% YoY, marking a sharp
rebound after four years of flat to negative growth. The iPhone 17 lineup has resonated
strongly with Chinese consumers, evidenced by double-digit growth in in-store traffic and
robust upgrader and switcher activity. Notably, this strength was achieved despite the later
release of the iPhone 17 Air, and Apple Intelligence not yet being available in the Chinese
market. iPhone ranked among the top three smartphones in China during the quarter. Given
that China contributes ~18% of AAPL’s total revenue, a rebound in the region represents a
meaningful upside for AAPL.
Apple Inc.-Strong outlook, yet no real game changer
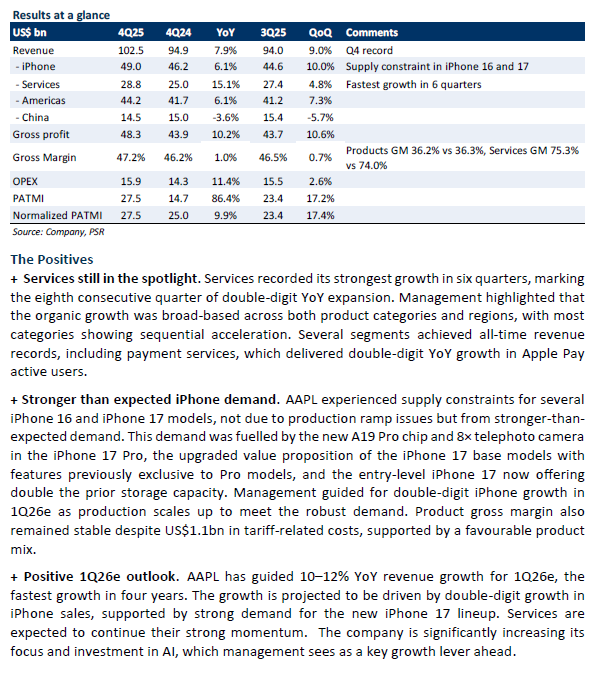
- 4Q25 PATMI was within our expectations, while revenue underperformed slightly due to supply constraints in iPhone 16 and 17. FY25 revenue/PATMI were at 98%/100% of our FY25e forecasts. Revenue grew 8% YoY, mainly driven by growth in iPhone (+6% YoY) and Services (+15% YoY).
- China revenue fell 4% YoY. Management remains positive, expecting the China market to return to growth in 1Q26e, with overall revenue projected to rise 10–12% YoY (the fastest pace in four years), supported by double-digit iPhone sales growth.
- We raise our FY26e revenue and PATMI assumption by 1% and 5% respectively, to account for the higher-than-expected growth in iPhone. We roll over another year of valuations and maintain our recommendation of REDUCE, with a raised DCF target price of US$230 (prev. US$200). WACC of 6.5% and a terminal growth rate of 3% remain unchanged. Apple’s AI rollout thus far has been disappointing, with no game-changing AI to trigger a major product upgrade cycle. We continue to remain cautious.
Apple Inc.- Thin on design, thinner on investor sentiment
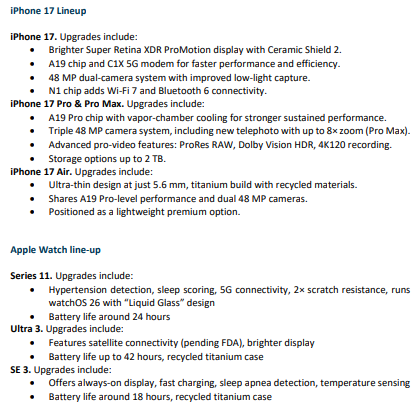
Apple hosted its “Awe-Dropping” launch event on 9 September, unveiling the iPhone 17 line up, including the ultra-thin iPhone Air (5.6 mm vs normal iPhone 16 7.8mm and 16 Pro 8.3mm)
- Upgrades include the new A19 Pro chip, C1X 5G modem, N1 networking chip, enhanced cameras, and tougher Ceramic Shield 2.
- Apple also introduced AirPods with on-device AI features, including real-time language translation and voice isolation, as well as the Apple Watch Series 11 with improved health tracking and a thinner design.
- Apple is absorbing the tariff impact by keeping prices unchanged or slightly lower (for same-series, same-storage iPhones), which adds pressure on margins.
- Our valuations remain unchanged. Our DCF target price remains unchanged at US$200, with a WACC of 6.5% and a terminal growth rate of 3%. We downgrade our recommendation from NEUTRAL to REDUCE due to the recent share price rally. We maintain a cautious outlook on Apple, due to near-term headwinds from tariffs, elevated CAPEX, and no significant AI innovation to help with persistent weakness in products and the China market.
Apple Inc.- Good results, but still cautious
-
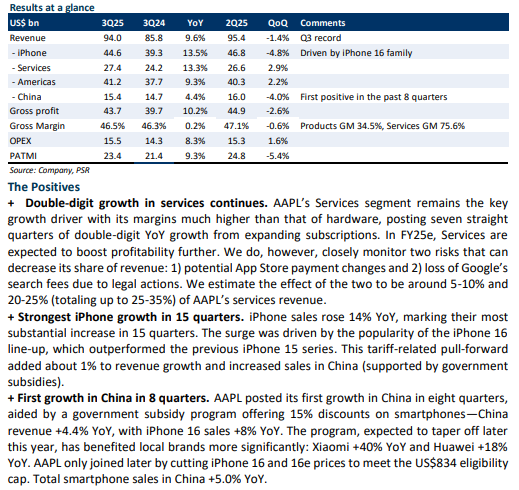
3Q25 results were within our expectations. 9M25 revenue/PATMI were at 75%/76% of our FY25e forecasts. Revenue grew 10% YoY, mainly driven by growth in iPhone (+14% YoY) and Services (+13% YoY).
-
China market +4.4% YoY, first positive in the past eight quarters, driven by accelerated iPhone sales supported by Chinese government subsidies. Management expects a tariff cost of US$1.1bn in 4Q25e
-
We keep our FY25e revenue and PATMI assumption unchanged. We maintain our recommendation of NEUTRAL, with the same DCF target price of US$200. WACC of 6.5% and a terminal growth rate of 3% remain unchanged. We maintain a cautious outlook on AAPL, as near-term tariff headwinds continue to weigh on margins. iPhone sales and the strength of the China market are also unlikely to last.
Apple Inc. – AI is playing catch-up at WWDC
Apple held its annual Worldwide Developers Conference (WWDC) on 10 June, during which it unveiled a redesign across its platforms and updates to iOS 26, iPadOS 26, watchOS 26, macOS 26 (Tahoe), and visionOS 26.
- Upgrades centered primarily on visual enhancements such as the new “Liquid Glass” design, along with minor software refinements
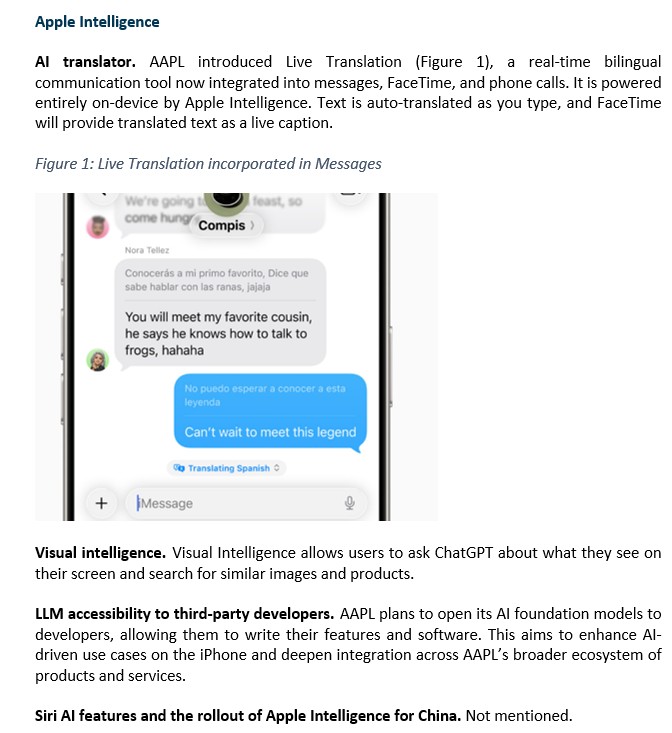
- Few AI innovations were announced (AI translator, LLM accessibility to third-party developers, and Visual Intelligence), most of which trail behind rivals like Google, not enough to address growing competitive pressures.
- Our valuations remain unchanged. We maintain our NEUTRAL recommendation with an unchanged DCF target price of US$200. WACC of 6.5% and a terminal growth rate of 3% remain unchanged. We maintain a cautious outlook on Apple, due to near-term headwinds from tariffs, elevated CAPEX, and no significant AI innovation to help with persistent weakness in products and the China market.
Get access to all the latest market news, reports, technical analysis
by signing up for a free account today!
Login
The full article is only available for premium content subscribers. To continue reading this article, please log in:
Not a Premium Content Subscriber yet? Sign up here!
- Home >
- Phillip Research Report